
UnitedHealth Group (UNH) Stock Looks Like A Bargain After A 30% Rise
UnitedHealth Group has logged a solid share price recovery over the past year, and with the stock last closing at US$407.46, the immediate question is whether that level still lines up with what its earnings can support. With fresh headlines around governance changes and business reshaping, the valuation story has moved back into focus for this large healthcare insurer.
- The stock is up 30.0% over the past year, which puts real pressure on the question of whether recent earnings trends are enough to justify the move.
- Recent commentary around margin repair, disciplined pricing and an earnings outlook reset implies that profit quality and sustainability may now matter more to valuing UnitedHealth than simple revenue scale.
- The analysts covering UnitedHealth Group have run their own numbers. See what analysts think UnitedHealth Group's shares could be worth.
The issue now is whether UnitedHealth Group's current share price is adequately supported by its earnings when judged against the Fair Ratio benchmark.
If you are comparing UnitedHealth Group with other opportunities supported by earnings, it may be useful to see how similar themes appear across 32 high quality undervalued stocks.
Is UnitedHealth Group a Bargain on Earnings?
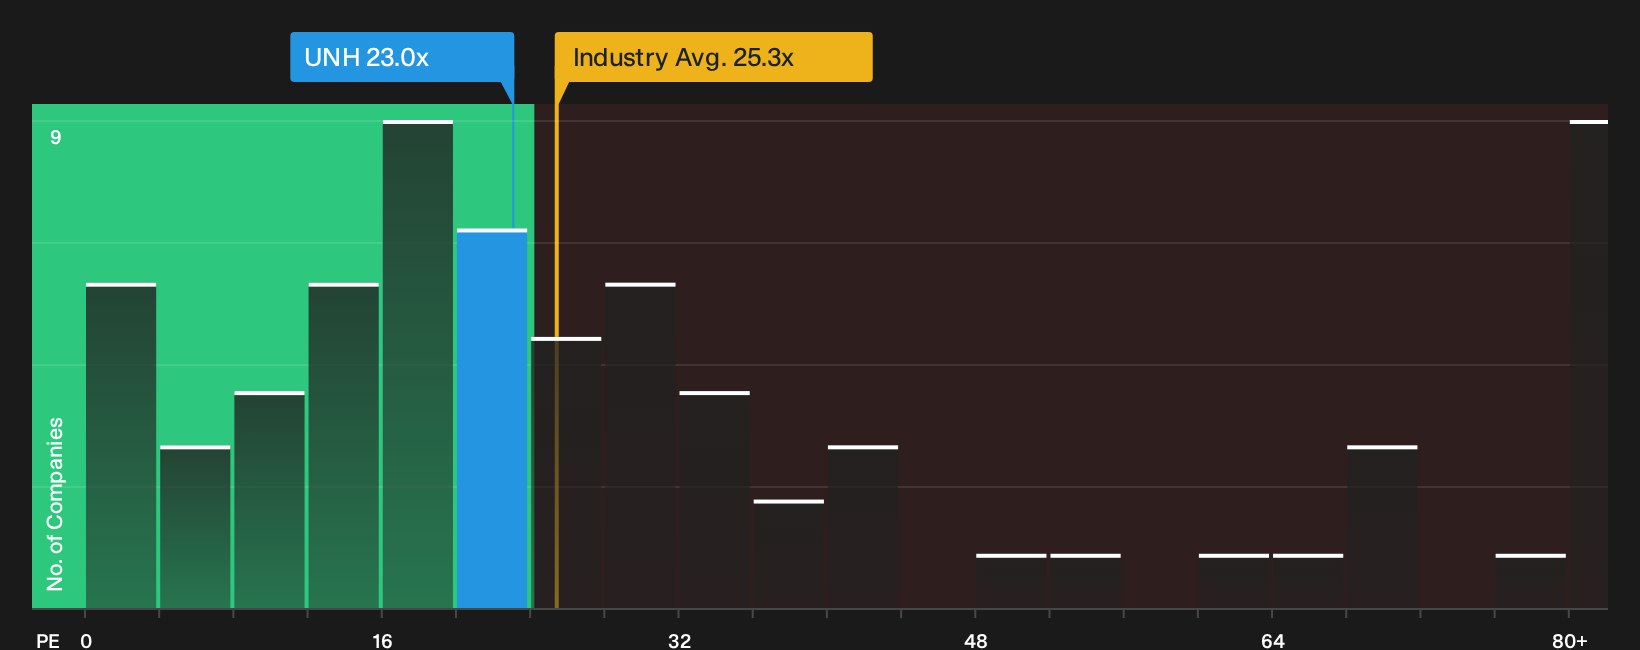
The P/E ratio is a useful metric for UnitedHealth Group because investors often focus on its ability to convert premiums and services into recurring earnings. On that basis, the stock trades at about 23.0x earnings, which is lower than the Healthcare sector average of roughly 25.3x and also below a peer group near 30.4x. This places the current valuation at a discount to both the broader industry and more direct competitors that have similar business models.
On a Fair Ratio basis, which reflects what multiple could be expected for UnitedHealth given its scale, profitability profile and risk mix, the current P/E appears undervalued rather than stretched. Recent commentary around margin repair, medical cost management and disciplined pricing has drawn more attention to the earnings line. However, the multiple still prices UnitedHealth below this more tailored benchmark. Because of that gap, the current P/E level may appeal to investors who want exposure to large managed care while paying less than what this framework suggests is typical for the company. Explore the numbers behind UnitedHealth Group's P/E valuation.
The UnitedHealth Group Narrative: What Would Justify Today's Price?
Narratives for UnitedHealth Group pick up where the valuation question leaves off, by spelling out which paths for revenue growth, profit margins and long term earnings would need to play out for the stock to look meaningfully higher or lower than today’s price on Simply Wall St’s Community page. Rather than a single multiple or model output, each one lays out its underlying assumptions so you can later compare those to the actual numbers the insurer reports.
The two UnitedHealth Group narratives pull in opposite directions on valuation, even though both lean heavily on the same integration and data story.
Bull case: 15% undervalued
According to the analyst consensus Narrative on Simply Wall St, the potential upside depends on execution and efficiency gains across UnitedHealth Group.
"The main thing that has to go right is execution on margin recovery in Medicare, Medicaid and commercial lines, along with delivering the OptumHealth turnaround and AI-enabled cost savings…"
Discover why this Narrative puts UnitedHealth Group at 15% undervalued.
Bear case: 32% overvalued
According to yiannisz, an investor in the Simply Wall St Community, the concern is focused on how regulators respond to the UnitedHealth Group model.
"Regulators and policymakers increasingly question whether vertically integrated insurers reduce competition or steer patients in ways that limit choice…"
Explore why this Narrative puts UnitedHealth Group at 32% overvalued.
The price of UnitedHealth Group is only one question to ask
Valuation work on UnitedHealth Group is just a starting point, because recent checks have also highlighted potential risk factors that investors may want to weigh carefully before making any decision. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com