
What Greencore Group Doubters Overlooked
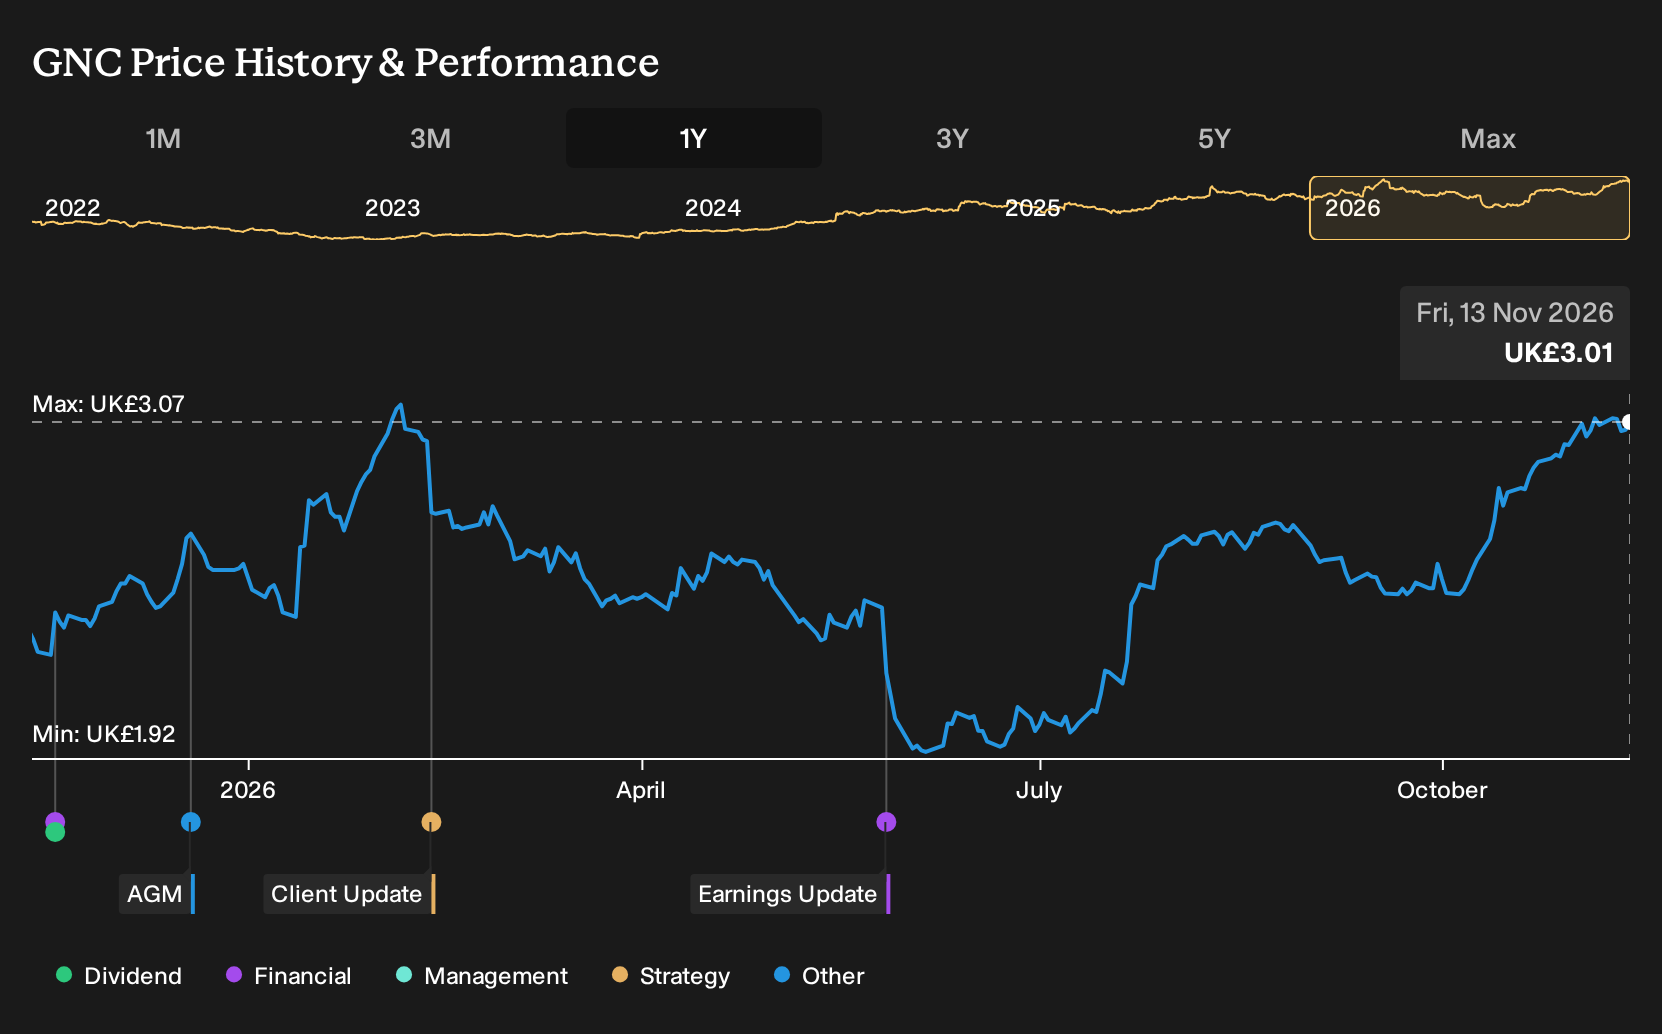
Greencore Group has been busy promising a smoother operation through its Making Business Easier and automation programs, while also lifting profit guidance as volumes ran ahead of the sector and the Bakkavor deal began to bed in. Investors who held Greencore Group over the past year are up 35.1%, including dividends. If you were weighing a purchase back on 13 November 2025, what exactly did you need to believe about these moves before any of that later news arrived?
If the move has made Greencore Group harder to judge, start where the gap is still open and scan 15 high quality undervalued stocks.
The Two Stories Investors Had To Choose Between On Greencore Group
The shares cost £2.29 at the start of the period, and anyone looking at Greencore Group then had to decide which story felt closer to reality.
On the optimistic side, one narrative pointed to a Fair Value of £2.56, a rough guide to what the price might be if the thesis played out. That view leaned on the Making Business Easier program and a wider technology overhaul, which were expected to cut costs and lift future efficiency.
The more cautious narrative anchored on a Fair Value of £1.85 and focused on different pressures. Rising regulatory scrutiny of packaging and heavier reliance on a small group of UK retailers were treated as key risks to earnings stability.
What The Results Changed For The Greencore Group Thesis
Greencore Group raised profit guidance as volumes ran ahead of the sector and highlighted progress integrating Bakkavor, which supported the optimistic efficiency story. The same period brought harder figures to weigh. Revenue moved from £922m in H1 2025 to £1,318m in H1 2026, while net income swung from a £19.8m profit to a £34.8m loss and net margin fell to 2.6% below zero. The evidence cut both ways.
The whole episode turned on one assumption. Cost and automation programs were expected to protect profitability. The simple check at any other business is whether higher sales are matched by a net margin that holds or improves in the reported numbers.
What You Would Be Paying For In Greencore Group Today
Greencore Group now trades at £3.01, after a 35.1% gain over the past year from £2.29. The bearish analyst Narrative on Simply Wall St sees its Fair Value below that level, arguing the recent price already bakes in a lot of the improvement story.
The same Narrative leans on a simple question: Do you believe Greencore can turn Bakkavor synergies and its Making Business Easier and automation work into steady margins and free cash flow, despite cash exceptionals, working capital strain and ongoing inflation pressure?
"While management targets at least £80m of annual cost synergies from the Bakkavor combination with specific phasing through 2029, the recent negative £76m free cash flow on a continuing basis and sizeable working capital outflow of about £86m highlight that integration and alignment of terms may absorb more cash and time than expected, which could hold back free cash flow conversion and delay any improvement in net margins."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Find Your Own Contrarian Opportunity
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 33% below our estimate - manages renewable-focused infrastructure and private equity vehicles directing capital into long-lived assets.
- Company 2 - 29% below our estimate - expands low-cost digital investing platforms that combine trading, custody and investor education tools.
- Company 3 - 24% below our estimate - builds testing and compliance software that plugs into finance and HR system implementations.
Three companies from the same screener. Open every one of the 9 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com