
Etsy (ETSY), Why Is The Latest Attention Raising Bigger Questions?
Etsy Design Awards return and what it could mean for Etsy (ETSY)
The 2026 Etsy Design Awards are returning with 13 new categories focused on emerging creators and artistic makers, raising fresh questions about how Etsy (ETSY) converts community buzz into marketplace activity.
Etsy shares trade at US$89.00 after a 1 month share price return of 7.3% and a 90 day gain of 11.4%. The 1 year total shareholder return of 55.9% hints that investors have been rewarding recent product upgrades and community pushes like the Design Awards, while the 5 year total shareholder return remains down 69.8%.
Scan how Etsy compares with other platforms tapping creator momentum and community-driven commerce by sifting through our hand picked 20 high quality undiscovered gems.
Etsy now trades at a meaningful discount to both analyst targets and some intrinsic value estimates after a sharp 1 year rebound. Is that a bargain, or is the market pricing Etsy’s risks correctly?
Most Popular Narrative: 10% Undervalued
At a last close of $89.00 versus the analyst consensus Narrative fair value of $98.48, Etsy is framed as modestly undervalued, with that gap hinging on how well marketplace improvements and profitability targets hold up against a higher discount rate of 10.15%.
Etsy's increasing investment in AI driven personalization and recommendations, using large language models and machine learning to refine search relevance and ad targeting, is intended to keep lifting conversion rates, order values, and advertising yield, which would support future revenue and earnings.
Expansion of direct marketing and app based engagement, with the Etsy app now representing about 47% of GMS and app GMS growing 11.2% in Q1 2026 and roughly 12.5 to 13% in Q2 versus 5.5 to 8% for the overall marketplace, positions higher lifetime value users and more frequent visits to contribute more meaningfully to revenue and margin resilience.
See why 39 investors see Etsy as 10% undervalued.
The analyst consensus Narrative on Simply Wall St ties that $98.48 fair value to a set of specific building blocks. It uses revenue growth assumptions of about 3.3% a year, an uplift in net profit margin to 18.2%, and a future P/E of 15.1x on projected 2029 earnings, all discounted back at 10.15%.
Those inputs sit beside Etsy’s current fundamentals. The marketplace generated $3,010.07m of revenue and $380.47m of net income, with net income growth of 3.1% year on year and revenue growth of 4.1%. Net profit margins have risen from 9% to 12.6%, while earnings have grown by 55.3% over the last year and by 15.1% per year over five years, supporting the view that profitability has become a more prominent part of the story.
Analysts then add capital allocation to the picture. The Narrative highlights more than $2.5b already available or authorized for buybacks and an 81% conversion of adjusted EBITDA to free cash flow in Q2 2026 with EBITDA margins close to 29% to 30%. That combination feeds the idea that shrinking the share count and higher margins could make earnings per share grow faster than headline profit.
On the risk side, the same framework flags three pressure points that could challenge that $98.48 figure. External AI shopping assistants could redirect purchasing away from Etsy and compress take rates, a rising share of AI generated goods could dilute the marketplace’s reputation with artisans and buyers, and any setback in active buyers or GMS per buyer would question whether discovery, matching, loyalty, and human connection work as durable levers for gross merchandise sales.
The end result is a relatively tight gap between the $89.00 share price and the analyst target. For readers, the key question is whether the revenue growth, margin expansion, and share count assumptions behind the Narrative feel realistic compared with the threats it outlines from AI, competition, and buyer engagement trends.
Result: Fair Value of $98.48 (UNDERVALUED)
Still, Etsy’s story can break if external AI shopping assistants siphon buyers off the platform or if AI generated goods erode the marketplace’s appeal for artisans.
Find out about the key risks to this Etsy narrative.
Another View on Etsy’s Valuation
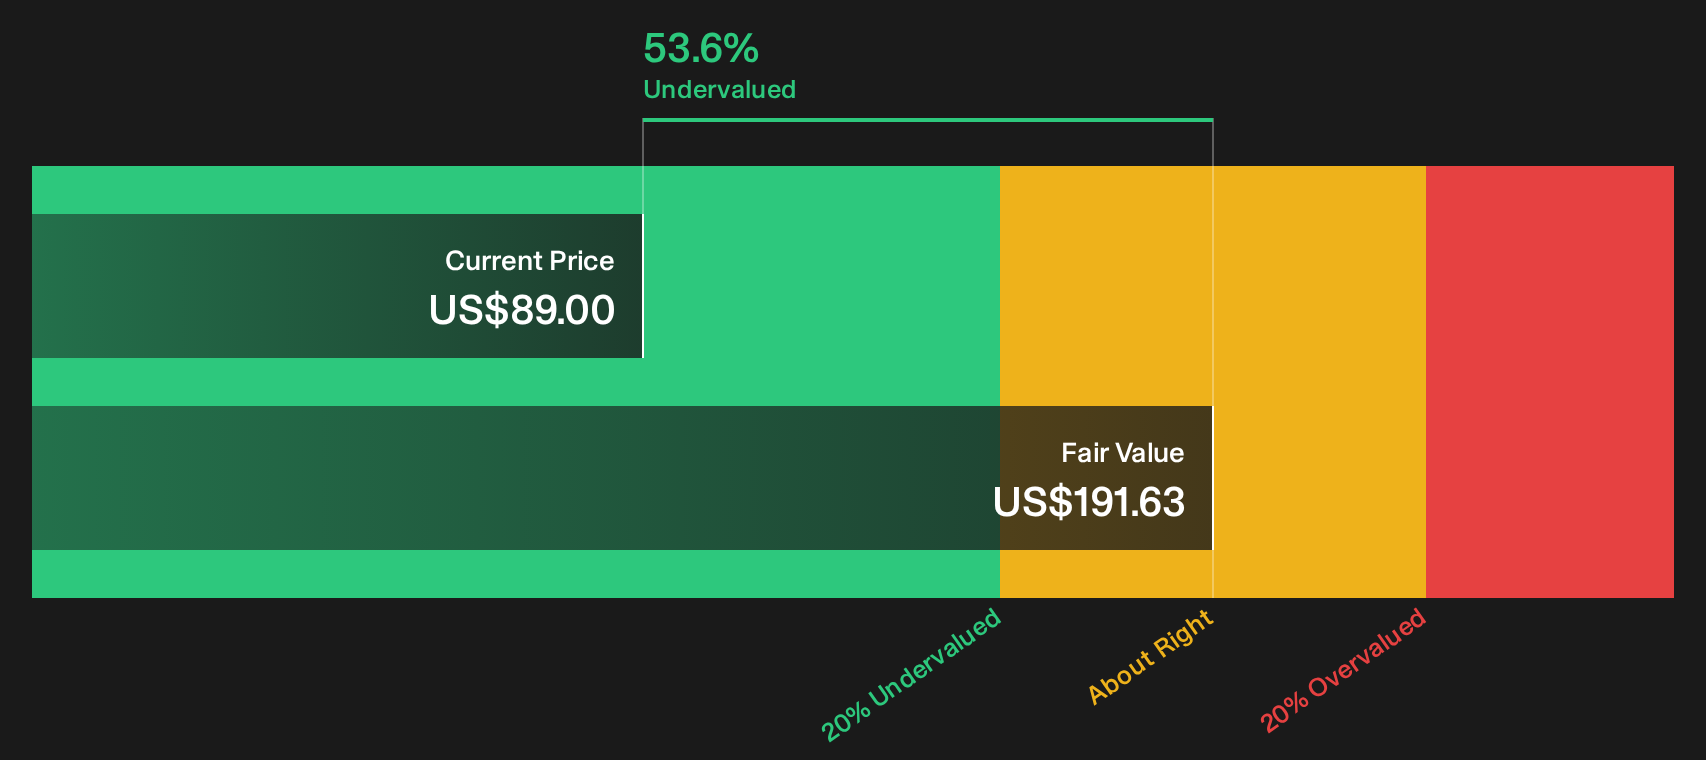
That cash flow based fair value of $191.63 presents Etsy as heavily undervalued, with the stock trading 53.6% below this estimate of its future cash flow value. The gap relative to the $98.48 analyst target is wide. The central question is which set of assumptions you consider more reliable.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If this mix of risks and rewards around Etsy feels finely balanced, consider acting soon and evaluate the same factors yourself using the 2 key rewards and 3 important warning signs.
Looking for more ideas beyond Etsy?
If Etsy has sharpened your focus on valuation, risk, and quality, it is worth lining up a few other candidates that could earn a spot on your watchlist.
- Target resilience first and see which companies combine healthy financial footing with disciplined fundamentals using the list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced quality and scan companies that pair strong fundamentals with appealing valuations through the 32 high quality undervalued stocks.
- Prioritise sleep at night potential and review companies with lower overall risk profiles via the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com