
Dropbox (DBX) Tests Its Valuation After $1.1b Convertible Bond Deal
Dropbox (DBX) has just completed a US$1.1b convertible bond deal, issuing 1.25% senior unsecured notes due 2031, with Citizens Bank, Goldman Sachs, J.P. Morgan and RBC joining the underwriter group.
At a share price of US$33.53, Dropbox has seen short term momentum soften, with the 7 day share price return down 3.26% and the 30 day share price return down 5.87%. This is occurring even as the year to date share price return of 24.51% and 1 year total shareholder return of 10.44% point to a still positive longer run picture that this new convertible bond financing now feeds into through fresh capital for its AI focused product rollout and the planned Tigris acquisition.
Scan how Dropbox’s bond raise and AI push compare with other software players by lining up the numbers against 42 profitable AI stocks that aren't just burning cash in this corner of the market.
Dropbox now trades only modestly below the average analyst target, yet at a much steeper discount to some intrinsic value estimates. Is that gap a margin of safety or a warning signal as valuation work begins?
Most Popular Narrative: 10% Overvalued
Dropbox closed at $33.53 compared with the analyst consensus Narrative fair value of $33.50, a tiny premium that still reflects a detailed forecast of flat revenue, modest earnings growth and ongoing buybacks. The analyst consensus Narrative on Simply Wall St ties that small gap to specific expectations for AI products, margins and capital returns rather than broad market sentiment.
The numbers imply a share price that already reflects a fairly valued, bullish view on Dropbox, with strong cash generation and buybacks offset by questions about how much AI success is realistically embedded in the stock.
See why 10 investors see Dropbox as 0% overvalued.
Result: Fair Value of $33.50 (OVERVALUED)
Still, the narrative can unravel quickly if AI products continue to pressure gross margins or if cybersecurity incidents make it harder for Dropbox to win and retain larger customers.
Find out about the key risks to this Dropbox narrative.
Another View: Market Multiples Point Lower For Dropbox
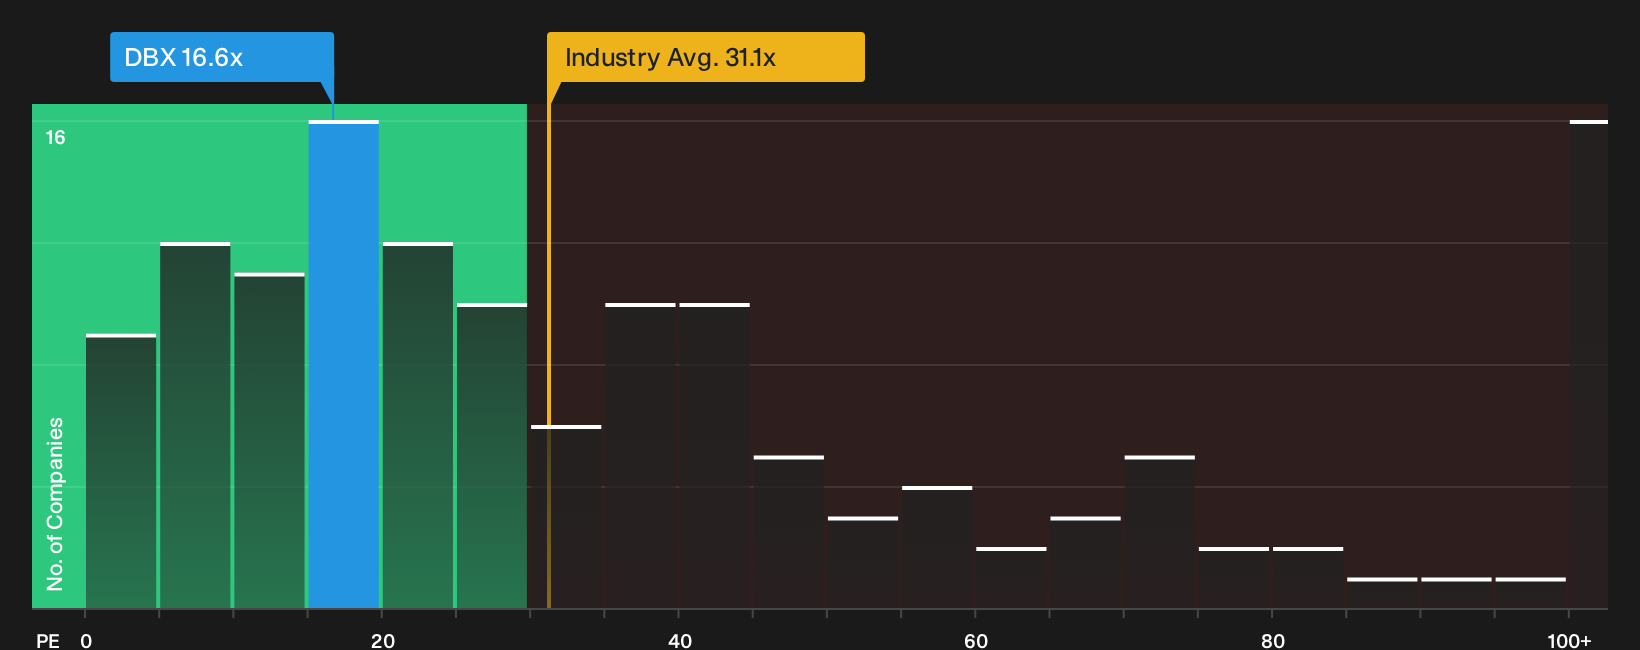
The first Narrative fair value pins Dropbox near $33.50, yet the current P/E of 16.6x sits well below both the US Software industry on 30.9x and peers on 25.5x, and under an estimated fair ratio of 25.2x. That spread frames either a valuation cushion or a signal the market is pricing in real business risk. Which side of that gap do you think is closer to the truth?
To see how that P/E gap lines up with Dropbox’s fundamentals and where the ratio might gravitate over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on Dropbox after all that, or just curious whether the risk or reward side of the story feels stronger to you right now? Take a closer look at the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Dropbox?
If Dropbox has you thinking harder about risk, reward and valuation gaps, do not stop here. Broaden your watchlist with a few focused screens.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (24 results) to cut through weaker financial structures.
- Hunt for quality at a discount by reviewing the 32 high quality undervalued stocks which combine strong cash flows with attractive pricing.
- Prioritise staying power by checking the 31 resilient stocks with low risk scores which score well on resilience while avoiding the most fragile businesses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com