
The Bet Vertex Pharmaceuticals Holders Made
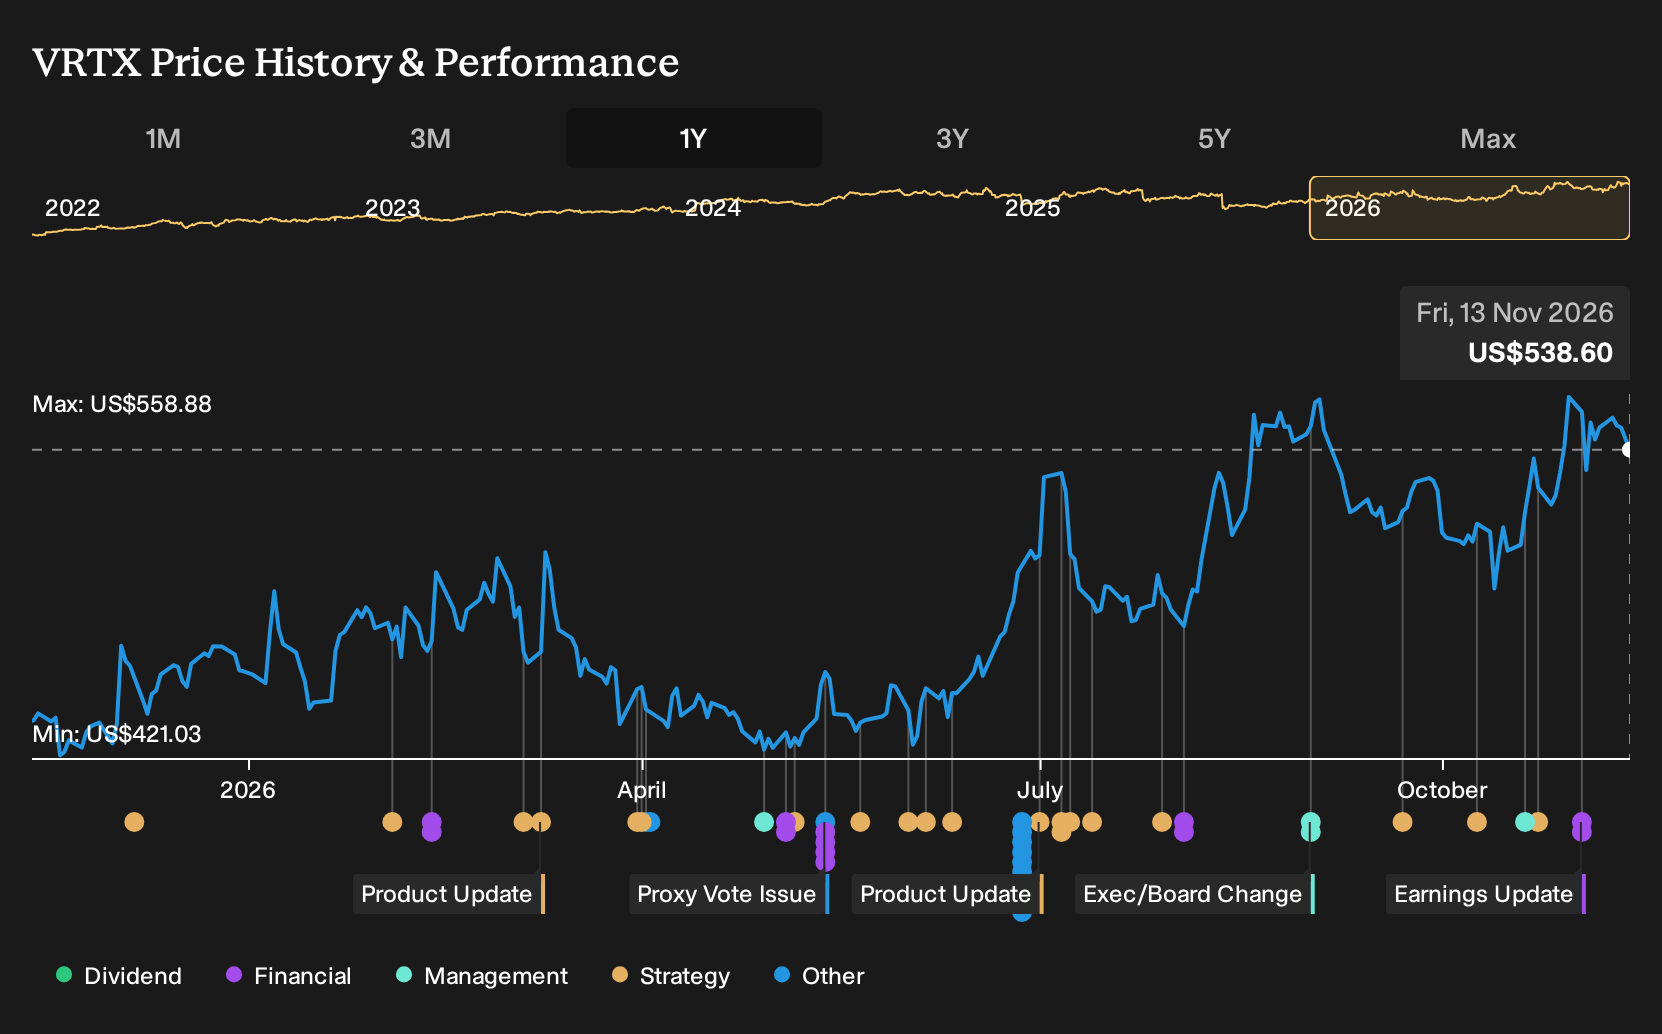
If you only glanced at the headlines on Vertex Pharmaceuticals over the past year, the story might have looked muddled. Revenue pushed ahead while net margin in Q3 2026 dropped to 19.0% from 35.2% the year before, and investors fretted over a US$10b acquisition and gene therapy costs. Holding Vertex Pharmaceuticals over the past year would have returned 23.2%, including dividends. If you were weighing that decision a year ago, what did the early data really suggest about this mix of growth and pressure?
Vertex Pharmaceuticals has already moved. See which of 32 high quality undervalued stocks still trade below our estimates.
The Argument You Would Have Been Weighing On Vertex Pharmaceuticals
The shares cost US$435 at the start of the period, so you were effectively choosing between two very different stories about where Vertex Pharmaceuticals might head next.
On the optimistic side, one camp saw a Fair Value of US$480, a notional price based on assumptions that revenue could grow 9.4% a year and profit margin might reach 37.4% as gene editing and new therapies scaled.
The pessimistic view pointed to a Fair Value of US$330, a scenario where tighter drug pricing, high gene therapy costs, and heavy R&D spending risked compressing returns despite any pipeline progress.
What The Results Changed For Vertex Pharmaceuticals
The Crinetics deal and growing breadth of ALYFTREK, CASGEVY, Journavx and Palsonify supported parts of the optimistic Vertex Pharmaceuticals story around diversification and new franchises. The same period showed pressure on profitability as total revenue reached US$3,440.8m in Q3 2026 while net income was US$653.6m and net margin fell to 19.0%. The evidence pointed in both directions.
The central question here was not headlines about new therapies, but whether expanding into gene therapy and endocrinology could support margins. When you look at another drug developer, test the same claim directly against reported net income and margin rather than only watching top line progress or pipeline headlines.
What Today's Vertex Pharmaceuticals Price Already Assumes
Vertex Pharmaceuticals now trades at US$539, with this Narrative's Fair Value sitting below that level according to the bearish analyst Narrative on Simply Wall St. Over the past year, the share price gain of 23.2% leaves less room for forgiving missteps.
The Narrative argues that at this price, you need confidence that new pillars like CASGEVY, renal programs and Crinetics assets can scale into high margin franchises despite heavier spending. The key assumption a buyer must test is whether broader infrastructure and patient support costs can be absorbed while still lifting long term profitability.
"The main thing that has to go right is that Vertex Pharmaceuticals converts its expanded multi pillar portfolio, including CASGEVY, renal programs, acute pain, and endocrinology assets from Crinetics, into durable high margin franchises that justify the current premium attached to the stock. The numbers on guidance, acquisitions, and pipeline scale imply a share price that already bakes in successful diversification beyond cystic fibrosis and strong long term execution, leaving limited room for disappointment."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Another Pillar Behind Drug Pipelines
Looking past Vertex Pharmaceuticals, you can ask the same question elsewhere. What supports a drug portfolio when one flagship therapy ages?
One large healthcare group is leaning on a crowded pipeline instead. It is advancing treatments in cancer, heart health, respiratory care and infectious disease.
The strategy is not just adding products. Longer lasting regimens and more convenient dosing aim to keep patients on therapy.
This business is also using AI to refine drug discovery. That could reshape how many late stage projects it manages at once.
If that mix of breadth, duration and efficiency holds, your checklist beside Vertex may change significantly.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 26% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com