
Is ePlus (PLUS) A Bargain After Strong Earnings And Raised Guidance?
ePlus (PLUS) just combined three key signals for investors. The company reported higher quarterly revenue and net income, raised its fiscal 2027 earnings outlook, and affirmed a regular cash dividend.
Over the past year, ePlus has paired a 96.44 US$ share price with an 8.22% one year total shareholder return, while a 4.70% 7 day share price gain and 8.93% 90 day share price return suggest momentum has been building around the recent earnings beat, upgraded 2027 guidance, and affirmed dividend.
Scan other tech-focused compounders that show a similar mix of earnings momentum and capital returns with our hand-picked 32 high quality undervalued stocks.
ePlus now trades below analyst targets and at an even wider gap to some intrinsic value estimates after the latest rally. Where does a fair price realistically fall inside that spread?
Most Popular Narrative: 13% Undervalued
On the analyst consensus Narrative on Simply Wall St, ePlus screens as undervalued, with a fair value of $111 against the latest close at $96.44. That gap reflects a view that current pricing does not fully capture the earnings and cash flow profile laid out in the forecasts.
The main factor that has to go right is that ePlus converts its growing managed services and security billings into a larger, higher margin recurring mix, despite current pressure on product and services margins.
The current valuation implies the market is treating ePlus’s shift to a pure technology solutions provider with strong cash generation and capital returns as less valuable than this bullish narrative, which holds that the stock is undervalued.
See why 1 investors see ePlus as 13% undervalued.
Result: Fair Value of $111 (UNDERVALUED)
Still, ePlus faces two clear pressure points: softer professional services demand from delayed retail projects, and tighter margins across product, managed services, and security offerings.
Find out about the key risks to this ePlus narrative.
Another View On ePlus Using Market Ratios
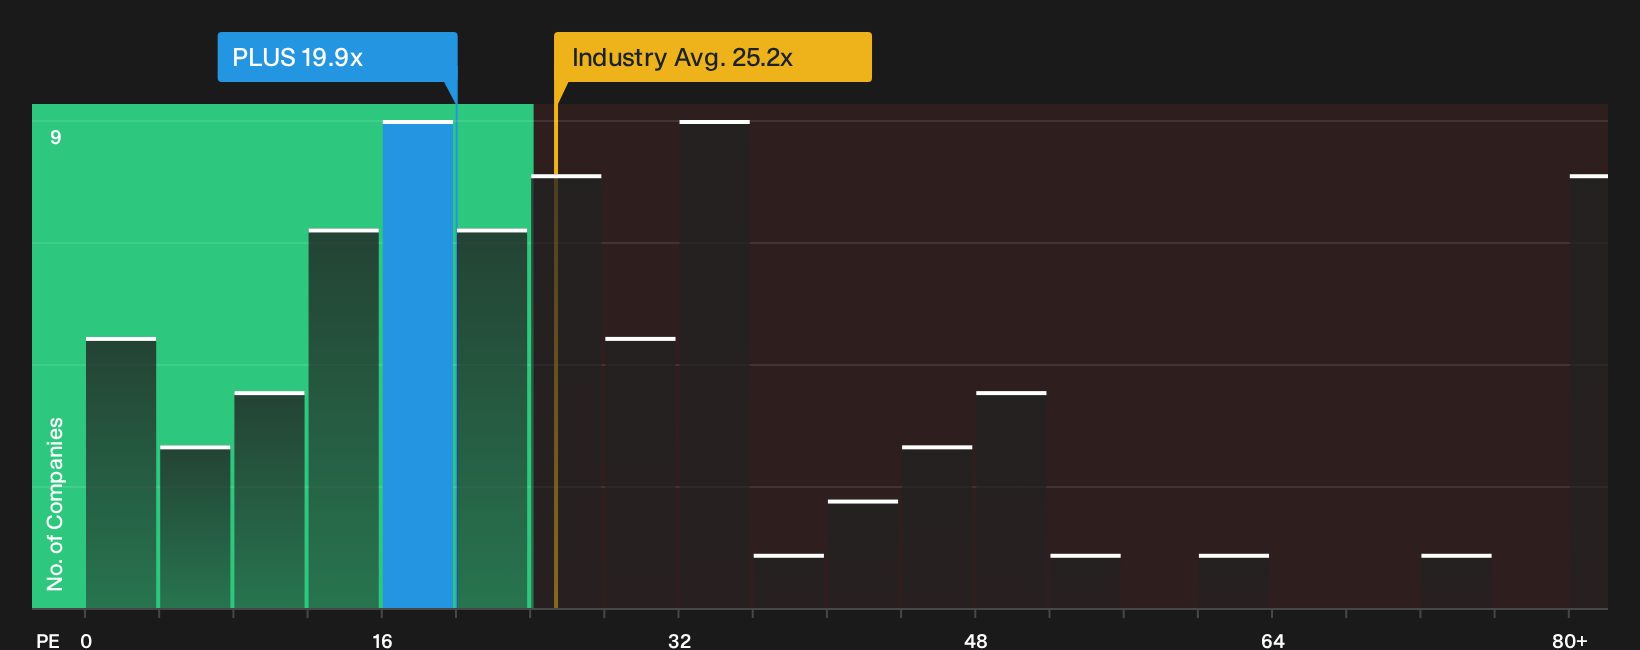
On simple earnings metrics, ePlus looks less generous. The stock trades on a P/E of 19.9x, which is higher than the peer average of 18.4x and above a fair ratio of 18.7x that the market could move toward over time, which raises the question of how much valuation cushion investors really have.
Our P/E work tells a different story to the undervalued fair value of $111, so it is worth stress testing which set of assumptions you trust more for ePlus before leaning too heavily on either signal. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Debate around ePlus is clearly heating up, so move fast, sift through the valuation work for yourself, and pressure test the optimistic signals behind its rewards analysis with 3 key rewards.
Looking for more investment ideas beyond ePlus?
If ePlus has sharpened your focus, do not stop here. Use the Simply Wall St screener to turn today’s interest into a broader, better informed watchlist.
- Target income-focused opportunities and scan for resilient payers through a curated set of 6 dividend fortresses that may help anchor your portfolio.
- Stack the odds toward financial strength and filter for companies on our list of solid balance sheet and fundamentals (24 results) before you commit fresh capital.
- Hunt for overlooked potential and surface 20 high quality undiscovered gems that the wider market might not be paying attention to yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com