
Caught Out By Lands' End's Fall? What The Bears Saw
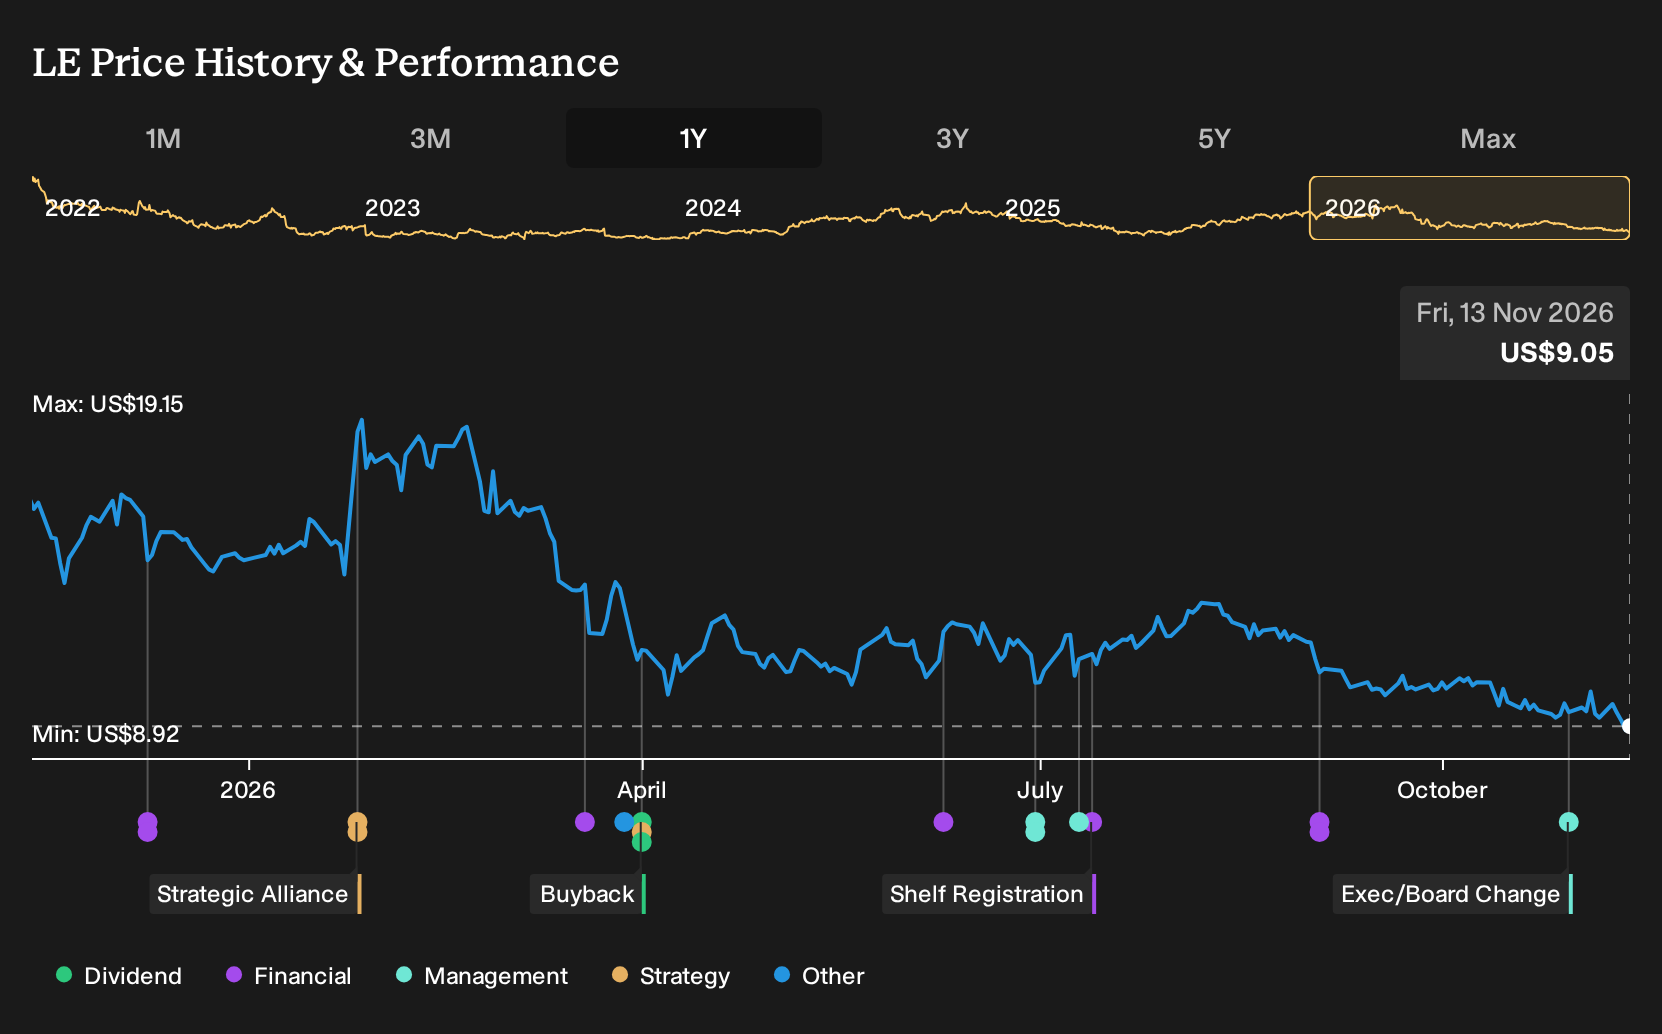
Lands' End just pulled off a rare combination for a troubled retailer. Revenue moved from US$294.079m in Q2 2026 to US$302.038m in Q2 2027, and a quarterly loss of US$3.667m turned into a profit of US$3.451m as net margin shifted from a 1.2% loss to a 1.1% gain. Investors who held Lands' End over the past year are down 44.9%, including dividends. If you had been weighing a position a year ago, which of these signals would have mattered most?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
Lands' End has already moved. See which of 32 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Had To Weigh On Lands' End
The shares cost US$16.21 at the start of the period, and anyone looking at Lands' End then had to choose between two grounded but very different stories.
The bullish case, with a Fair Value of US$17.5, leaned on data-driven personalization and broader marketplace partnerships supporting 2.6% revenue growth and a 4.0% profit margin assumption.
The cautious view, pointing to a Fair Value of US$15, focused on fierce digital competition and tariff pressure as key risks, even while using the same 2.6% growth and 4.0% margin assumptions.
What The Results Changed For Lands' End
The clearest datapoint in this period is the move from a loss of US$3.667m to a profit of US$3.451m, as net margin shifted from a 1.2% loss to a 1.1% gain. That tilt toward profitability supported the bullish Lands' End case that margins could improve, although the modest US$302.038m revenue figure kept the cautious story about potential growth ceilings alive.
The key lesson is simple. When a thesis depends on margins, treat each reported net margin as a checkpoint and test whether it is steadily moving toward the level the narrative assumes.
Has Lands' End Changed More Than Its Share Price?
Lands' End trades at US$9.05 today, and the current bullish Narrative's Fair Value sits above that level based on its own assessment rather than any objective rulebook.
According to woodworthfund, an investor in the Simply Wall St Community who wrote the Narrative, the key question is whether Lands' End has truly reset its balance sheet so a buyer today is assuming a cleaner capital structure and a more resilient profit engine.
"By monetizing its IP, Lands’ End viciously torched its mountain of debt right when skyrocketing interest rates started suffocating its competitors. Today, Lands’ End runs its daily operations and global e-commerce empire seamlessly, all while cruising with a clean, heavily deleveraged balance sheet."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Looking Beyond Lands' End
Lands' End depends on e-commerce and digital merchandising to reach its shoppers. Your portfolio does not have to stop there.
Every online basket needs a place to be filled, processed and delivered. One large platform operator has steadily built out that backbone.
It pours resources into cloud infrastructure, logistics technology and automated retail systems. Those tools help merchants refine pricing, forecasting and personalized offers.
If Lands' End reflects one retailer using such capabilities, a further question remains. Who quietly supplies more of those underlying digital rails?
One Narrative has already put a figure on it. → Uncover the company trading 41% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com