
Is WEBTOON Entertainment (WBTN) A Bargain As Narrower Losses And Guidance Lift Confidence?
WEBTOON Entertainment (WBTN) gave investors fresh numbers to consider after third quarter 2026 results showed lower sales but a smaller net loss, along with new revenue guidance for the coming quarter.
WEBTOON Entertainment’s latest earnings have landed after a choppy stretch, with the share price slipping 2.28% over the past day to US$9.85. The stock is still showing a 6.26% 1 month share price return and an 18.89% 3 month share price return as investors weigh improved loss figures and fresh guidance against a year to date share price return that is down 25.44% and a 1 year total shareholder return that is down 23.23%.
Scan other storytelling and media platforms that display similar turnaround traits by reviewing our hand picked 20 high quality undiscovered gems alongside WEBTOON Entertainment's latest earnings shift.
WEBTOON Entertainment now trades well below its earlier highs, yet has just laid out upbeat revenue guidance and a narrower loss. Do you treat this reset as an entry point or wait for an even cheaper shot at the stock before running the numbers?
Most Popular Narrative: 13% Undervalued
WEBTOON Entertainment's analyst consensus Narrative on Simply Wall St sees fair value at $11.29, compared with the latest close at $9.85. This frames the stock as modestly undervalued while hinging on specific growth levers actually being realised.
The multi year collaboration with Disney that includes Marvel, Star Wars, and 20th Century Studios IP remains in early innings. WEBTOON Entertainment still has to fully translate these franchises into higher engagement and a larger monetizable user base, which would support future revenue growth.
Expansion of higher margin advertising and IP monetization is still at an early stage, with ads around 11% to 12% of revenue and IP adaptations under 10%. Continued growth in these lines and increased cross border consumption of Korean content can have an outsized impact on gross margin and overall profitability.
See why 10 investors see WEBTOON Entertainment as 13% undervalued.
Result: Fair Value of $11.29 (UNDERVALUED)
Still, this narrative breaks quickly if Japan stays weak or if marketing spend keeps climbing without clearer progress on WEBTOON Entertainment’s path toward smaller losses.
Find out about the key risks to this WEBTOON Entertainment narrative.
Another View: What Multiples Say About WEBTOON Entertainment
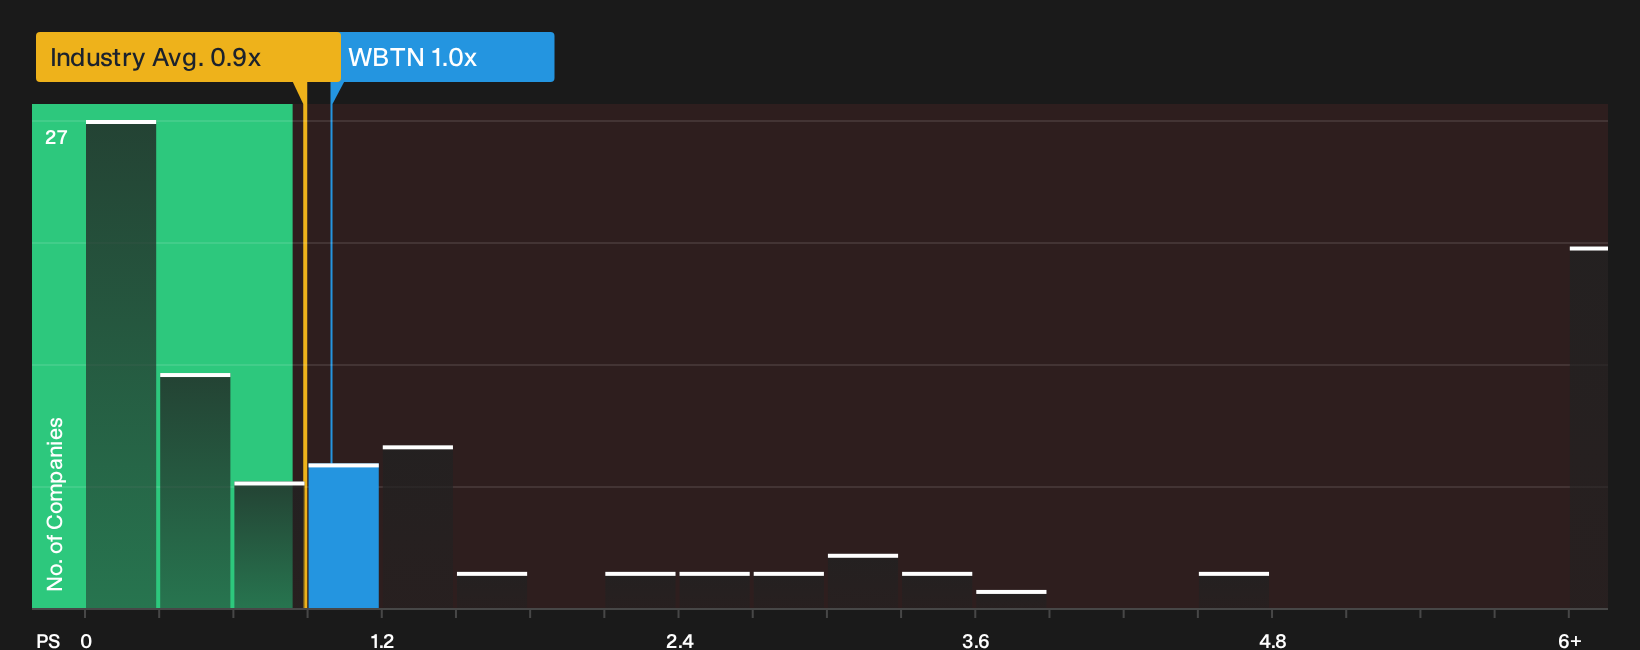
There is a catch. While WEBTOON Entertainment screens as undervalued on future cash flows, the current P/S ratio of 1x looks expensive next to both the US Interactive Media and Services group at 0.9x and the estimated fair ratio of 0.9x. That gap points to less room for error if growth or margins disappoint. Does this premium multiple still feel comfortable after the latest earnings reset?
To unpack what this pricing gap might mean in practice, including how P/S could move toward the fair ratio as expectations adjust, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone so far leaves you torn, use that unease as a prompt to move fast and work through the numbers yourself while sentiment is still divided. To see what other investors view as WEBTOON Entertainment's upside drivers, start with the 2 key rewards.
Looking for more WEBTOON Entertainment style ideas?
If WEBTOON Entertainment has your attention, do not stop at a single ticker. Broaden your watchlist using focused stock lists built from clear, transparent rules.
- Target stronger balance sheets by scanning companies that pass our list of solid balance sheet and fundamentals (24 results) so fragile finances do not quietly cap your upside.
- Pursue mispriced value by using the 32 high quality undervalued stocks to spot businesses where quality metrics and current pricing look out of sync.
- Reduce downside shocks by filtering for 31 resilient stocks with low risk scores that may help smooth portfolio swings when sentiment turns against higher beta trades.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com