
Earnings Beat Might Change The Case For Investing In Constellation Energy Stock (CEG)
- Constellation Energy reported past third quarter 2026 results with sales of US$9.55b and net income of US$1.84b, alongside higher basic and diluted EPS of US$5.19 from continuing operations.
- The business has secured multi decade nuclear power contracts with major technology customers, locking in more than 8,500 MW of capacity in 2026 and deepening its role as a long term clean power supplier.
- The next area of attention is how Constellation Energy's long dated nuclear contracts with hyperscalers may shape the broader investment narrative around baseload power.
Scan how Constellation Energy’s nuclear and data center story compares with other power and infrastructure plays by reviewing a curated group of 43 power grid technology and infrastructure stocks in one place.
Constellation Energy Investment Narrative Recap
To own Constellation Energy, you need to believe, as Andrei_Niculescu, a Simply Wall St Community investor who wrote the Narrative, argues, that scarce 24/7 carbon free baseload will keep mattering as AI data centers and electrification lift power demand. The third quarter beat and higher guidance lean into that view by showing the nuclear and clean portfolio converting into tangible earnings and contracts.
The key near term catalyst is continued progress on long term deals with hyperscalers and large loads, plus smooth execution on the Calpine integration and related regulatory milestones. The biggest immediate risk sits in policy and approval delays, especially around large load connections and the higher debt taken on with Calpine.
The most relevant update for that story is management securing about 8,500 MW of long dated contracts in 2026, including agreements with Amazon and Google. These deals, alongside over 90 million megawatt hours already under long term arrangements, are starting to shift Constellation Energy from a merchant heavy generator toward a more contracted earnings mix.
That contracting progress directly touches both catalysts and risks. It supports visibility on future cash flows if nuclear availability stays high, while still leaving more than 100 million megawatt hours of clean output available for potential premium agreements. Execution on these remaining volumes, amid regulatory and interconnection uncertainty, is where the next leg of the Constellation Energy story is likely to be written.
In Andrei_Niculescu’s narrative, a fair value of US$350.00 for Constellation Energy rests on the business sustaining 19.8% annual revenue growth and reaching an 11.1% future profit margin, which together support higher long run earnings power from its contracted clean baseload portfolio.
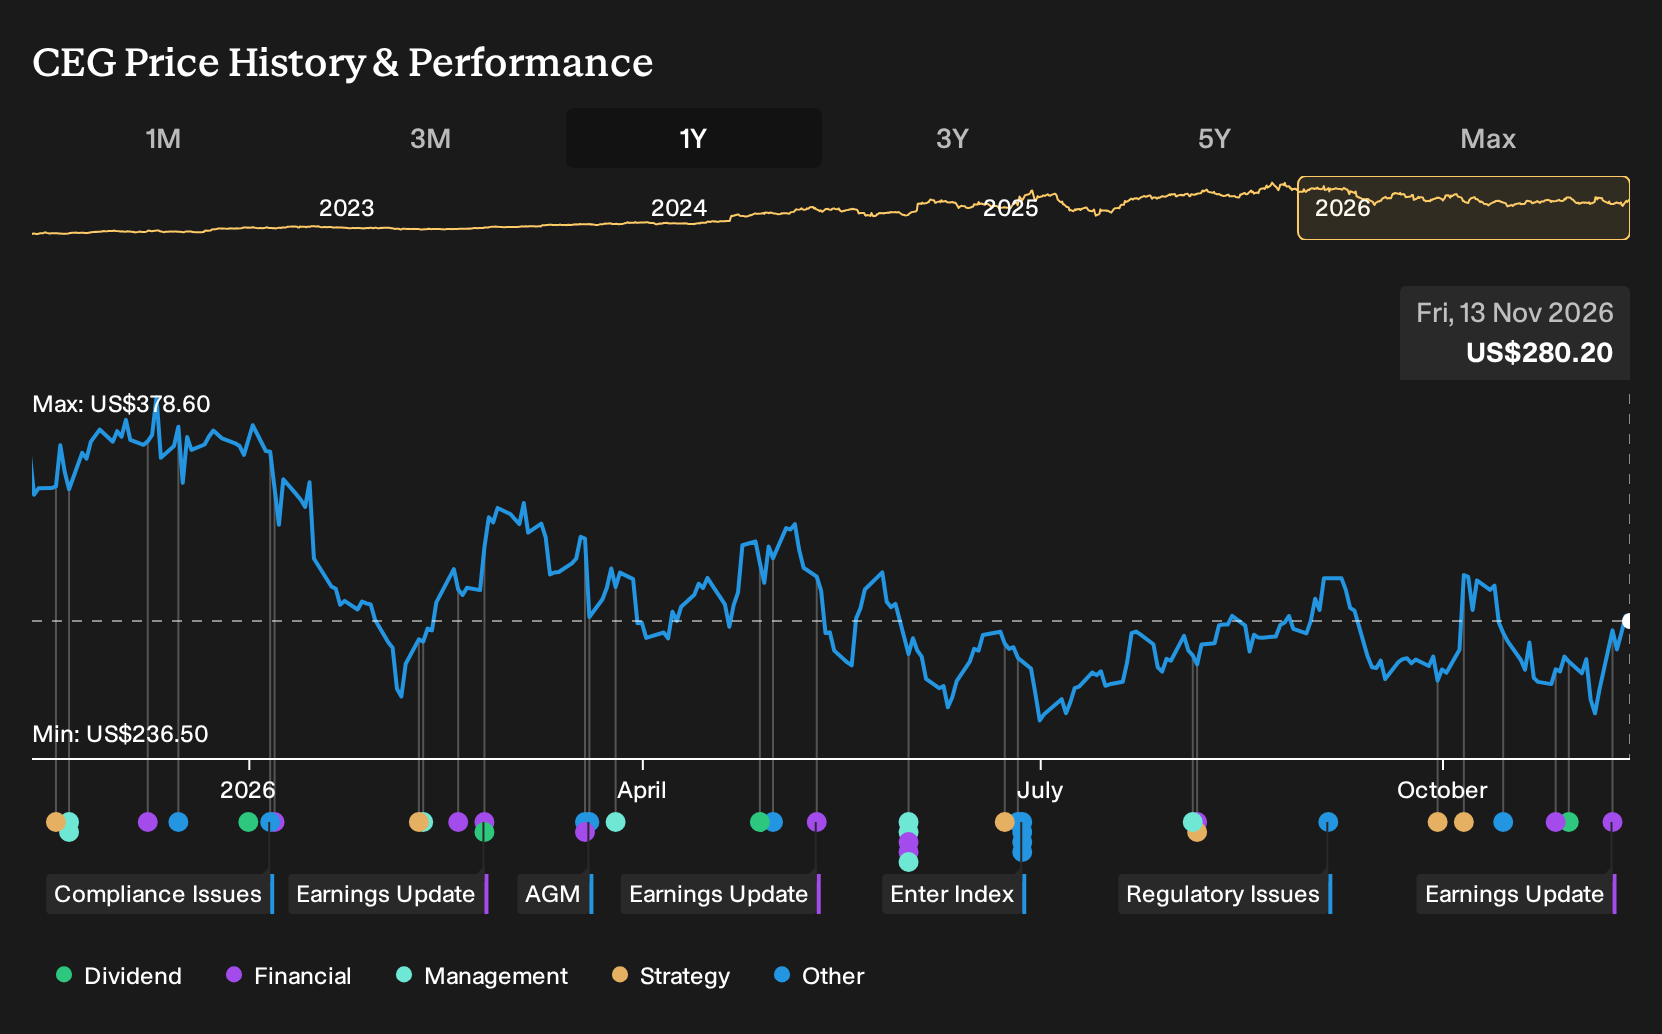
Uncover why Constellation Energy's fair value indicates a 25% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the lowest ranked analysts focus on policy risk rather than nuclear scarcity for Constellation Energy. They worry that changing support schemes and more distributed generation could cap upside. Before this earnings beat, that group was only penciling in about 4.6% annual revenue growth and roughly US$5.5b of earnings by 2029. Their view is much more cautious. These forecasts were set before the latest contracts and results, so you may want to compare them with other narratives and decide which assumptions feel more realistic to you.
Explore 7 other Constellation Energy fair value estimates, including one that suggests up to 6% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis and judgment.
- A great starting point for your Constellation Energy research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Constellation Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Constellation Energy's overall financial profile at a glance.
Looking for more Constellation Energy style investment ideas?
If Constellation Energy has you rethinking how you build a long term portfolio, it can help to line it up against other opportunities with different risk and income profiles using the Simply Wall St Screener.
- If you care most about quality at a reasonable entry point, check out a curated set of 32 high quality undervalued stocks that combine fundamentals with pricing that may appeal to value focused investors.
- If resilience matters more than excitement, filter for stability first and see a group of 31 resilient stocks with low risk scores that aim to keep drawdowns in check.
- If you want balance sheets that can carry growth plans without stretching finances, start with a list of solid balance sheet and fundamentals (24 results) and compare how these businesses stack up on debt and cash strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com