
What Sartorius Bulls Got Right
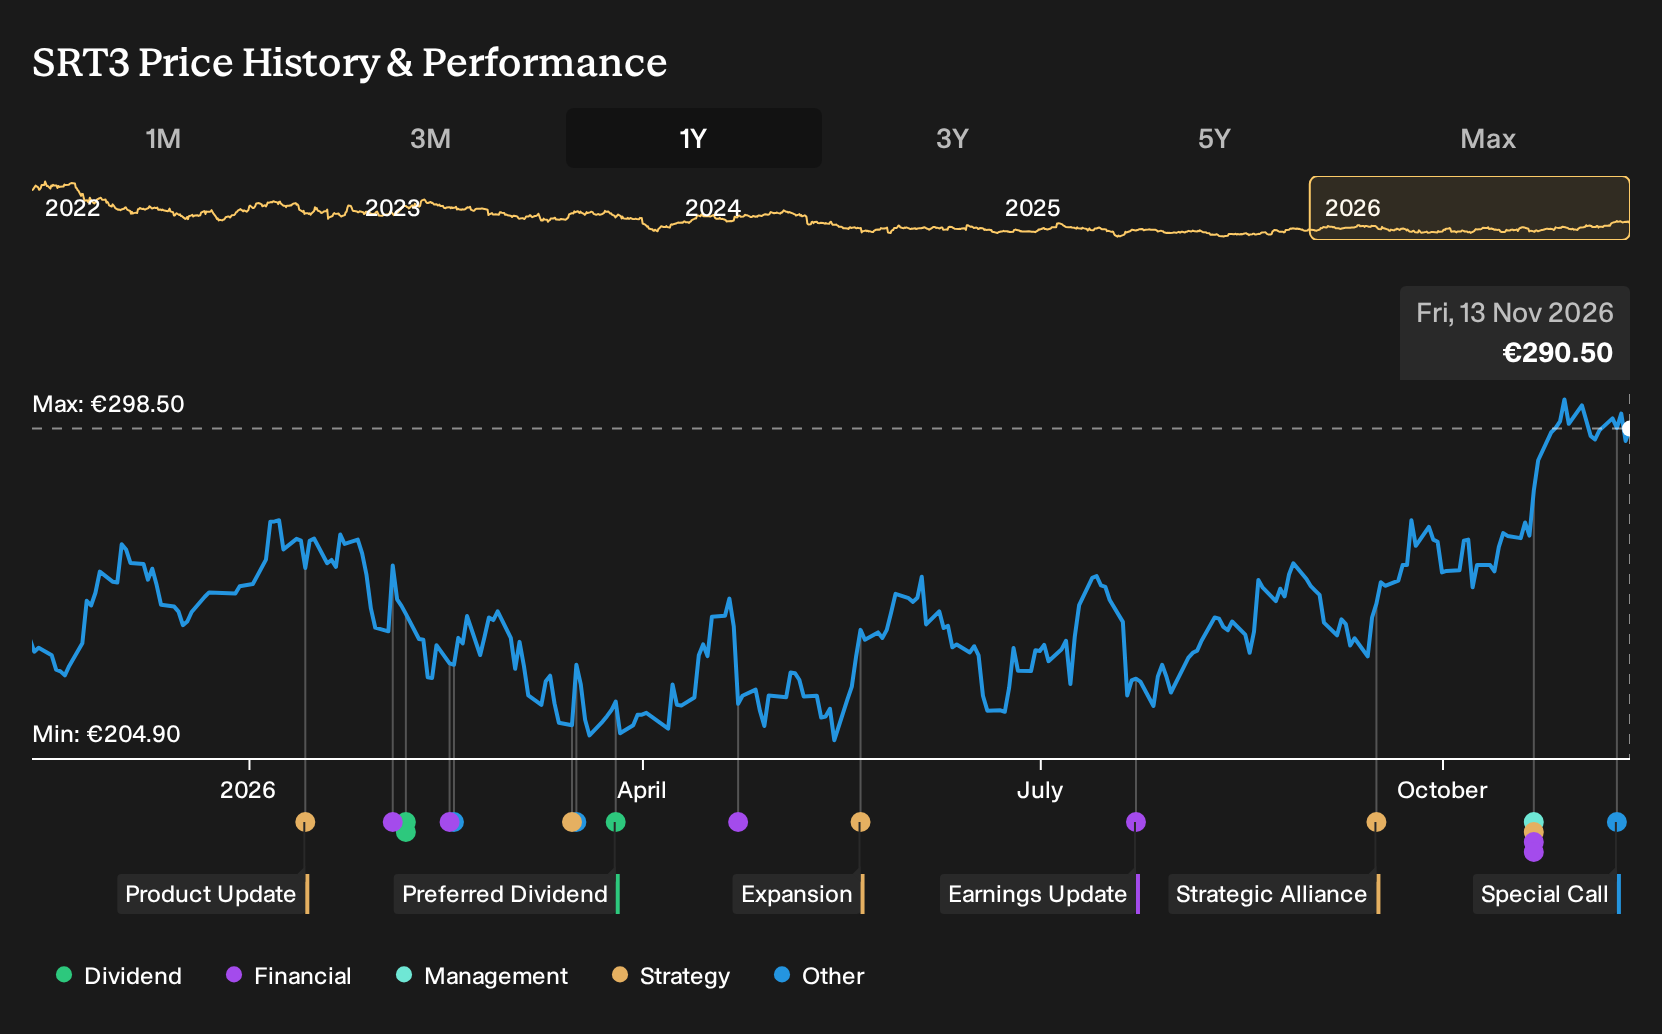
If Sartorius was on your watchlist rather than in your portfolio, the recent move may feel like an opportunity that slipped by. Holding Sartorius over the past year would have returned 26.6%, including dividends. That result now sits next to last year’s split analyst views, with some focused on recurring consumables and cell and gene therapy bioproduction, and others on tariffs and margin pressure. If you were looking back to November 2025, how much weight would you have given to that recurring consumables story?
This theme extends beyond Sartorius. See which of 123 healthcare AI stocks may still merit a closer look.
The Two Sartorius Stories Investors Were Arguing Over
The shares cost €229 at the start of the period, and Sartorius sat between two very different but credible stories about what came next.
On the bullish side, one camp saw cell and gene therapies driving a long runway for bioproduction capacity. Their narrative implied a fair value of €310, a price level that assumed recurring consumables and preclinical services could support higher margins over time.
The bearish view anchored on cost and policy friction. That narrative pointed to a fair value of €175, built around the risk that rising tariffs, regulatory scrutiny, and cheaper rivals would squeeze Sartorius margins and limit market reach.
What The Sartorius Results Put To The Test
The clearest fact was Sartorius reporting Q3 2026 revenue of €926.3m and net income of €66.1m, up from €843.2m and €43.8m a year earlier. Net margin moved from 5.2% to 7.1%. That shift, together with steady updates on recurring consumables and cell and gene therapy capacity, leaned toward the optimistic case, although tariff and competition worries were not removed.
The hinge assumption here was that recurring consumables would support healthier profitability. For any similar stock, track whether net margin and profit per share move in the same direction as the story about repeat revenue.
What Sartorius Investors Are Really Paying For Today
Sartorius now trades at €290, with the business showing Q3 2026 revenue of €926.3m and net income of €66.1m. Net margin at 7.1% compared with 5.2% a year earlier puts more attention on how much of that improvement ties back to recurring consumables and related services.
Shareholders are being asked to judge whether that margin step is durable or more cyclical. The key assumption to test is how consistently Sartorius can convert consumables demand into higher, steady profitability.
We value every stock in the world, every day. See what our valuation says Sartorius is worth now.
Looking One Step Beyond Sartorius
You have Sartorius on your mind, but the story does not stop there.
Bioprocess gear needs a steady stream of complex therapies that are still practical to manufacture.
It also needs medicines that remain usable across markets as pricing rules tighten.
Another large drug maker is leaning on a broader treatment portfolio and recent launches to keep its earnings engine turning.
It is not just chasing one blockbuster, but using a wider therapy mix to navigate patent losses and shifting policy demands.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 26% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com