
We're Hopeful That IZEA Worldwide (NASDAQ:IZEA) Will Use Its Cash Wisely
There's no doubt that money can be made by owning shares of unprofitable businesses. For example, biotech and mining exploration companies often lose money for years before finding success with a new treatment or mineral discovery. But while the successes are well known, investors should not ignore the very many unprofitable companies that simply burn through all their cash and collapse.
So should IZEA Worldwide (NASDAQ:IZEA) shareholders be worried about its cash burn? For the purposes of this article, cash burn is the annual rate at which an unprofitable company spends cash to fund its growth; its negative free cash flow. First, we'll determine its cash runway by comparing its cash burn with its cash reserves.
When Might IZEA Worldwide Run Out Of Money?
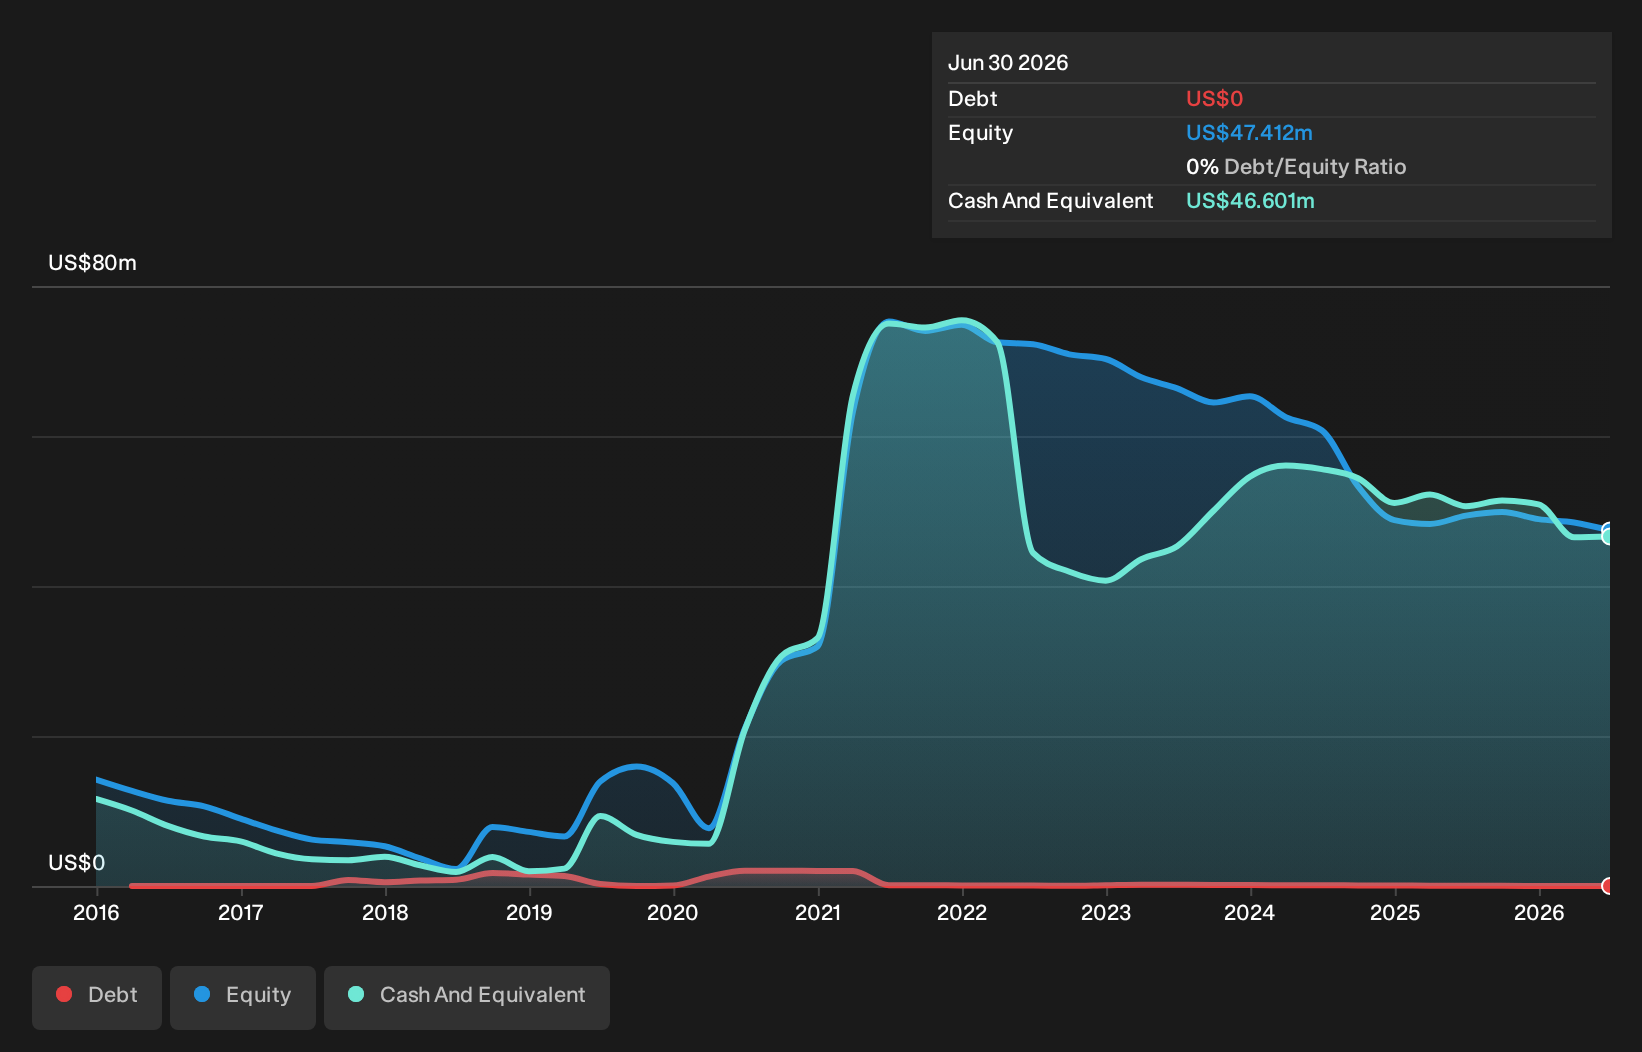
A company's cash runway is the amount of time it would take to burn through its cash reserves at its current cash burn rate. As at June 2026, IZEA Worldwide had cash of US$47m and no debt. In the last year, its cash burn was US$2.6m. That means it had a cash runway of very many years as of June 2026. Even though this is but one measure of the company's cash burn, the thought of such a long cash runway warms our bellies in a comforting way. The image below shows how its cash balance has been changing over the last few years.
See our latest analysis for IZEA Worldwide
How Well Is IZEA Worldwide Growing?
Notably, IZEA Worldwide actually ramped up its cash burn very hard and fast in the last year, by 127%, signifying heavy investment in the business. While that's concerning on it's own, the fact that operating revenue was actually down 27% over the same period makes us positively tremulous. In light of the above-mentioned, we're pretty wary of the trajectory the company seems to be on. In reality, this article only makes a short study of the company's growth data. You can take a look at how IZEA Worldwide has developed its business over time by checking this visualization of its revenue and earnings history.
How Hard Would It Be For IZEA Worldwide To Raise More Cash For Growth?
While IZEA Worldwide seems to be in a fairly good position, it's still worth considering how easily it could raise more cash, even just to fuel faster growth. Companies can raise capital through either debt or equity. Commonly, a business will sell new shares in itself to raise cash and drive growth. We can compare a company's cash burn to its market capitalisation to get a sense for how many new shares a company would have to issue to fund one year's operations.
IZEA Worldwide's cash burn of US$2.6m is about 6.8% of its US$38m market capitalisation. That's a low proportion, so we figure the company would be able to raise more cash to fund growth, with a little dilution, or even to simply borrow some money.
So, Should We Worry About IZEA Worldwide's Cash Burn?
On this analysis of IZEA Worldwide's cash burn, we think its cash runway was reassuring, while its increasing cash burn has us a bit worried. While we're the kind of investors who are always a bit concerned about the risks involved with cash burning companies, the metrics we have discussed in this article leave us relatively comfortable about IZEA Worldwide's situation. On another note, IZEA Worldwide has 2 warning signs (and 1 which is concerning) we think you should know about.
Of course IZEA Worldwide may not be the best stock to buy. So you may wish to see this free collection of companies boasting high return on equity, or this list of stocks with high insider ownership.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.