
Why Vail Resorts (MTN) Is Back In The Spotlight
Vail Resorts (MTN) has been pulled into a high profile governance fight, as Oasis Management and Gregory S. Meyer push competing director slates, incentive plan changes, and pay objections ahead of the December 2026 shareholder meeting.
At a share price of US$152.61, Vail Resorts has delivered a 13.92% year to date share price return. However, the 1 year total shareholder return of 11.32% sits against a 5 year total shareholder return that has fallen 44.14%, signalling improving short term momentum while longer term holders remain deeply under water as the governance dispute unfolds.
Scan how the Vail Resorts saga compares with other companies facing governance pressure and weak multi year returns by reviewing our hand picked 31 resilient stocks with low risk scores that some investors use as potential stabilisers.
Vail Resorts now trades only slightly above the average analyst target while still carrying a sizeable intrinsic value gap. Where might a reasonable fair value actually cluster after this recent rebound?
Most Popular Narrative: 3% Overvalued
On the analyst consensus Narrative on Simply Wall St, Vail Resorts screens as slightly overvalued, with a fair value of $148.36 against the last close of $152.61. This puts the current governance battle against a reasonably full valuation backdrop.
The current valuation implies investors are already pricing Vail Resorts as fairly valued, with its earnings resilience, capital spending plans and dividend profile largely reflected in the share price.
See why 12 investors see Vail Resorts as 3% overvalued.
Result: Fair Value of $148.36 (OVERVALUED)
Still, the narrative around Vail Resorts can break if another weak snow year forces a dividend cut or if governance friction drags on capital allocation decisions.
Find out about the key risks to this Vail Resorts narrative.
Another View: Cash Flows Tell A Different Story
Fair value based on the analyst narrative puts Vail Resorts at $148.36 and slightly overvalued on that lens. The SWS DCF model points in the opposite direction, with an estimated future cash flow value of $231.90, which suggests investors could be underpaying if those cash assumptions hold up.
This kind of gap between a P/E based narrative and a cash flow model often signals either generous long term forecasts in the DCF or a lot of skepticism already embedded in the share price. The key question is which set of assumptions you trust more as the governance fight and snow volatility play out.
Look into how the SWS DCF model arrives at its fair value.
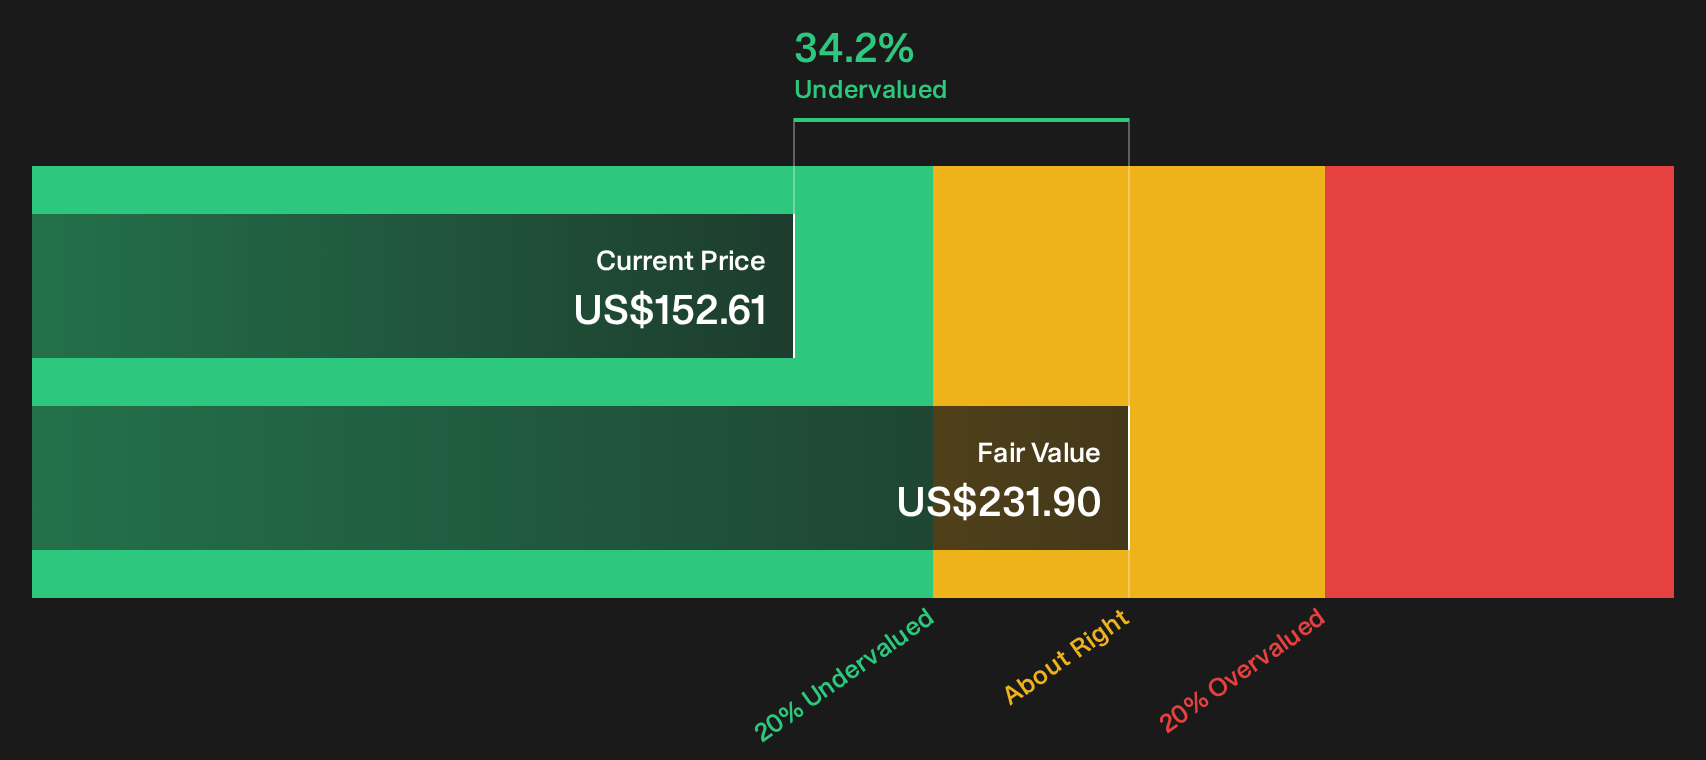
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Vail Resorts for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
There are mixed signals on Vail Resorts so far, and you may be wondering what really matters most for you. Act while the debate is fresh and weigh both sides through the 2 key rewards and 3 important warning signs.
Looking for more ideas beyond Vail Resorts?
If Vail Resorts has you rethinking concentration risk, you may want to widen your opportunity set with fresh stock ideas that match different goals and comfort levels.
- Target quality at a discount by scanning companies that screen as both attractively priced and fundamentally strong through the 32 high quality undervalued stocks.
- Build a steadier income stream by reviewing the 6 dividend fortresses for businesses combining higher yields with more resilient payout histories.
- Consider strengthening downside protection by checking the list of solid balance sheet and fundamentals (24 results) that some investors use when they want sturdier financial foundations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com