
Is Sunrun (RUN) Reasonably Valued After Its Puerto Rico Battery Expansion?
Sunrun has been in the headlines for its large distributed power plants and home batteries, yet the share price around US$8.63 raises a clear question for you as an investor. Is what you are paying today meaningfully supported by the company’s earnings profile, or are recent developments doing more work in the story than the income statement can comfortably back up?
- Over the past 5 years the stock has fallen about 84.3%, which puts the focus squarely on whether the current valuation is now better aligned with the earnings that Sunrun actually produces.
- Recent news on large scale battery programs in Puerto Rico and preferred equity financing for thousands of projects may support expectations for future revenue and cash generation, which matters for how sustainably the business can convert its model into earnings over time.
- There is a second opinion on Sunrun worth weighing. See what analysts think Sunrun's shares could be worth.
The issue now is whether the earnings that Sunrun is producing today, and that investors expect it to produce, are enough to justify the current share price.
If you want to stress test this same earnings question beyond Sunrun and across a wider set of opportunities, scan the 32 high quality undervalued stocks.
Is Sunrun a Bargain on Earnings?
For a business like Sunrun that investors often look at through the lens of earnings power, the P/E ratio gives a direct read on what the market is paying for each dollar of profit.
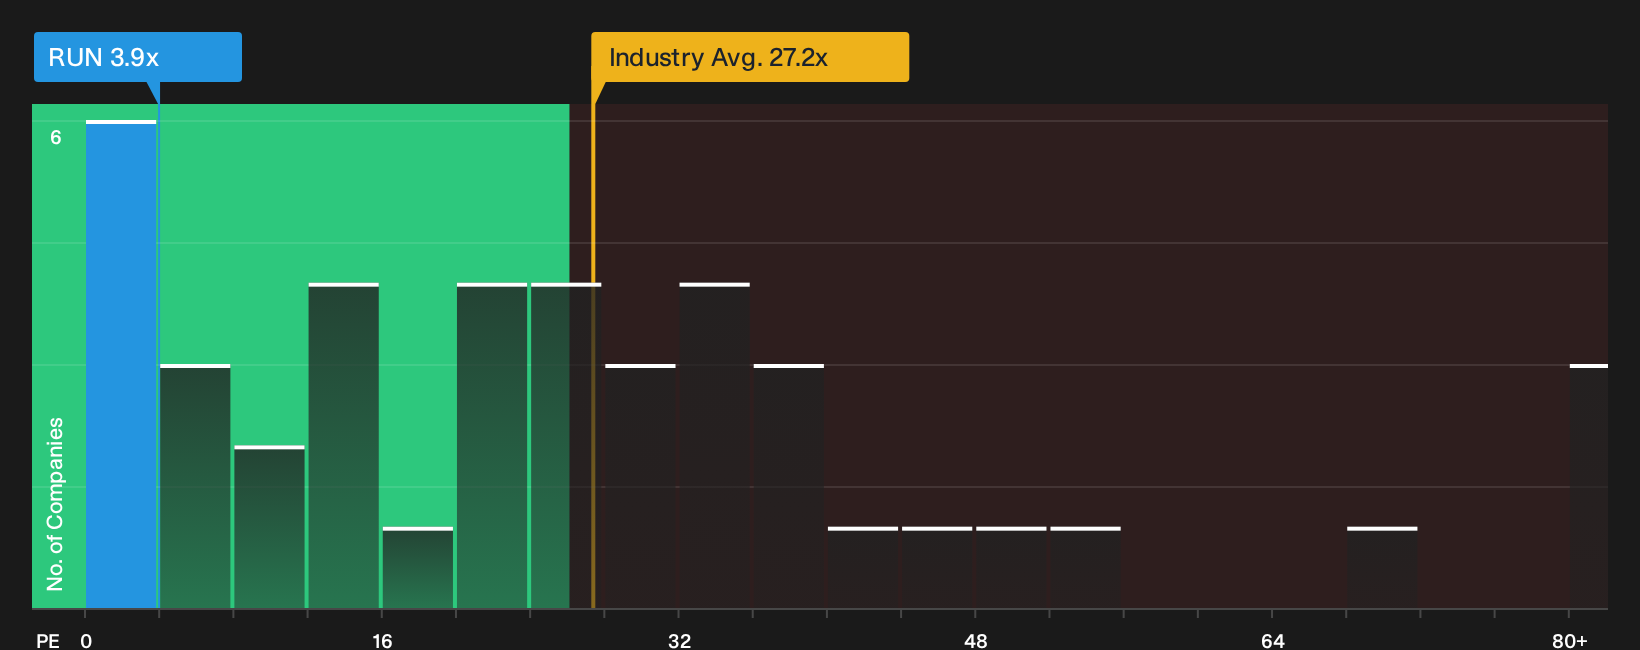
On this measure, Sunrun trades on roughly 3.9x earnings, compared with about 27.2x for the wider Electrical industry and a peer group closer to 29.8x. Because the recent Q3 2026 profit included derivative related gains and tax benefits, you should ask how repeatable those earnings are before leaning too hard on that discount. The fair value model, which blends Sunrun’s growth profile, profitability, sector and risk, points to a higher P/E than where the shares change hands today, so the multiple screens as undervalued against that tailored yardstick. Despite the surge in Puerto Rico battery participation and the positive headlines around Sunrun’s grid support role, the current P/E still prices the stock at a wide gap to sector norms and to what the model suggests as a more typical level for this business. Explore the numbers behind Sunrun's P/E valuation.
The Sunrun Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E puzzle leaves off for Sunrun by spelling out what would need to happen to growth, margins and earnings for the stock to be worth materially more or less than it is today. Each narrative ties a specific fair value estimate to a clear story about Sunrun's possible catalysts and risks, so you can track which scenario is gradually matching the real world data.
Views on Sunrun split between investors who see financing as a temporary drag and analysts who think those same pressures could cap profitability for years.
Bull case: 55% undervalued
According to yiannisz, a Simply Wall St Community investor who wrote the bullish Narrative, the real upside hinges on capital and storage economics.
"This perspective reframes Sunrun less as an energy company and more as a capital allocator operating within the energy transition…"
Discover why this Narrative puts Sunrun at 55% undervalued.
Bear case: 23% overvalued
The bearish analyst Narrative on Simply Wall St argues that rising costs and compliance obligations could absorb more value than the market expects.
"The settlement that requires investigating and remediating consumer fraud claims with no cap on restitution introduces open ended compliance and remediation obligations…"
Explore why this Narrative puts Sunrun at 23% overvalued.
One more Sunrun angle worth checking before you move on
There is a separate lens on Sunrun that sits outside today's P/E and narratives. This is where professional analysts consider where the business could be a few years from now and how that lines up with the current price. Explore where analysts expect Sunrun to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com