
Bloom Energy (BE) Lands NTT DATA Deal With Valuation Back In Focus
Bloom Energy (BE) just landed a 900 megawatt fuel cell deal with NTT DATA for global data centers, a contract that puts AI power demand and on-site generation squarely in focus for investors.
Recent contract wins have come alongside sharp price swings for Bloom Energy, with the share price falling 19.8% over the past month but still delivering a 94.5% year to date share price return and a 1 year total shareholder return of 71.6%. Momentum has been choppy in the last quarter, where the share price declined 16.5%, yet multi year holders have seen very large gains with a 3 year total shareholder return of more than 14x. This suggests the latest data center agreements and sector optimism around AI power demand are now being weighed against higher expectations and changing views on risk.
Scan Bloom Energy’s peers riding the same AI power buildout by zeroing in on our hand picked list of 53 AI infrastructure stocks for potential follow up ideas.
After a near 20% pullback on the heels of large AI and data center contracts, Bloom Energy now forces a timing decision. Is this the moment to lean in, or is it better to wait for a more favorable price before valuing the stock?
Most Popular Narrative: 50.3% Undervalued
On the numbers, the narrative fair value of $386.10 sits well above Bloom Energy’s last close at $191.99, which puts a spotlight on how investors are weighing long term potential against recent volatility. According to JRY, an investor in the Simply Wall St Community who wrote the narrative, the market is still underestimating how wide Bloom Energy’s opportunity set could be.
The Bloom Energy story is still early days. Wall Street cannot seem to comprehend that so many areas for their growth, international, other market segments, even personal or community power (where they started) are largely untapped.
The main constraint on their opportunity is plain and simple ignorance.
See why 52 investors see Bloom Energy as 50% undervalued.
Result: Fair Value of $386.10 (UNDERVALUED)
Still, the fair value story around Bloom Energy could unwind quickly if large data center deals slow or if expectations for AI driven power demand are reset.
Find out about the key risks to this Bloom Energy narrative.
Another View: Bloom Energy Looks Expensive On Earnings
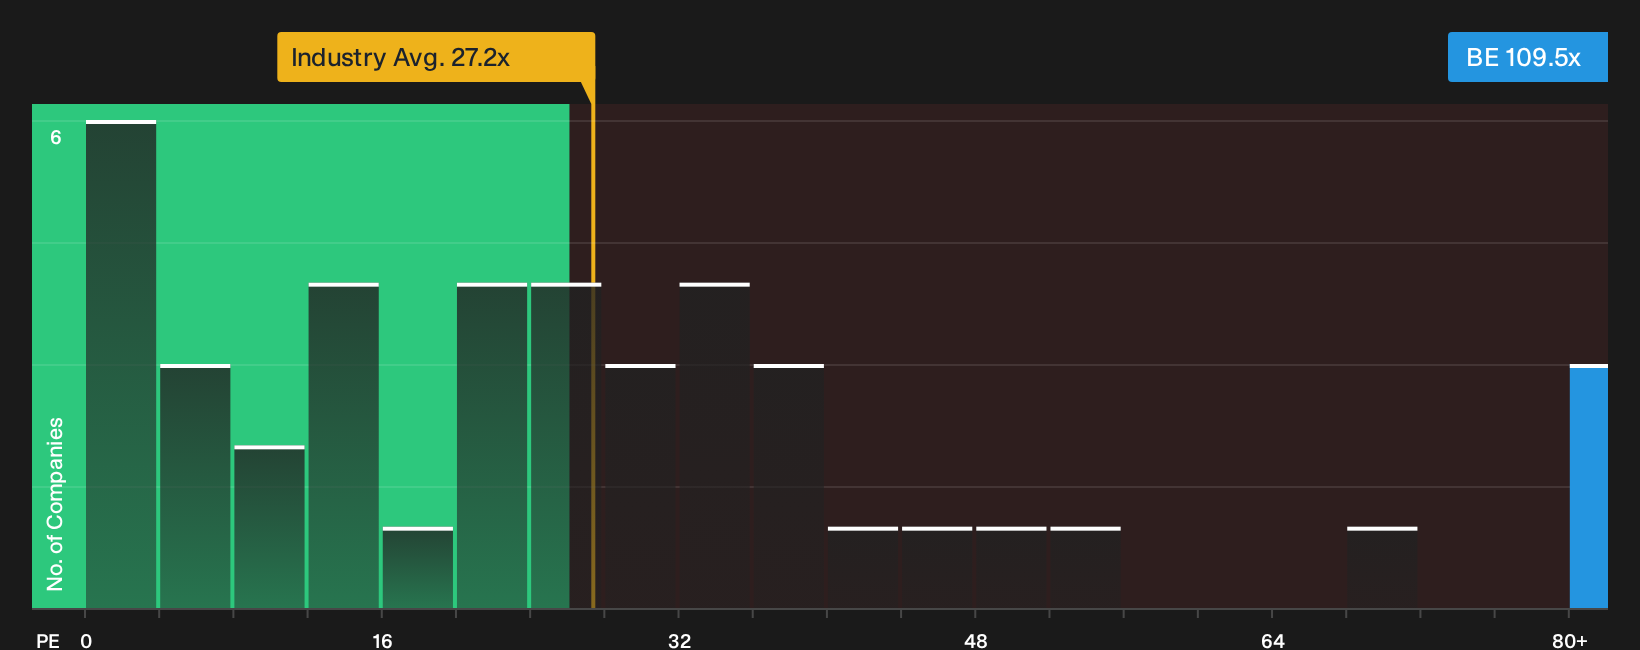
The story changes once you swap community fair value for a simple earnings yardstick. On a P/E of 109.5x, Bloom Energy trades at roughly 4x the US Electrical industry average of 27.2x, about 2x the peer group on 56.7x, and well above its own 72.1x fair ratio.
That kind of gap can reward you if growth stays very strong. However, it also raises the risk that any disappointment in earnings expectations hits the share price hard. It leaves an obvious question: Is this a premium you are comfortable paying for the Bloom Energy story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted about whether the current Bloom Energy enthusiasm lines up with the risks on the table? Act quickly, work through the data for yourself, and pressure test both sides of the story by weighing the 3 key rewards and 3 important warning signs.
Looking for more Bloom Energy investment ideas?
If Bloom Energy has your attention, do not stop here. Broaden your watchlist now, or you risk missing stronger balance sheets, deeper value, and quieter compounders hiding in plain sight.
- Target durability first and scan a list of solid balance sheet and fundamentals (24 results) where financial strength helps support business resilience when sentiment shifts.
- Hunt for mispriced quality by reviewing a 32 high quality undervalued stocks that filters for solid cash generation and attractive valuations.
- Prioritise sleep at night potential and browse a 31 resilient stocks with low risk scores chosen for lower risk profiles and steadier characteristics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com