
Earnings Guidance Raise Could Be A Game Changer For Teleflex Stock (TFX)
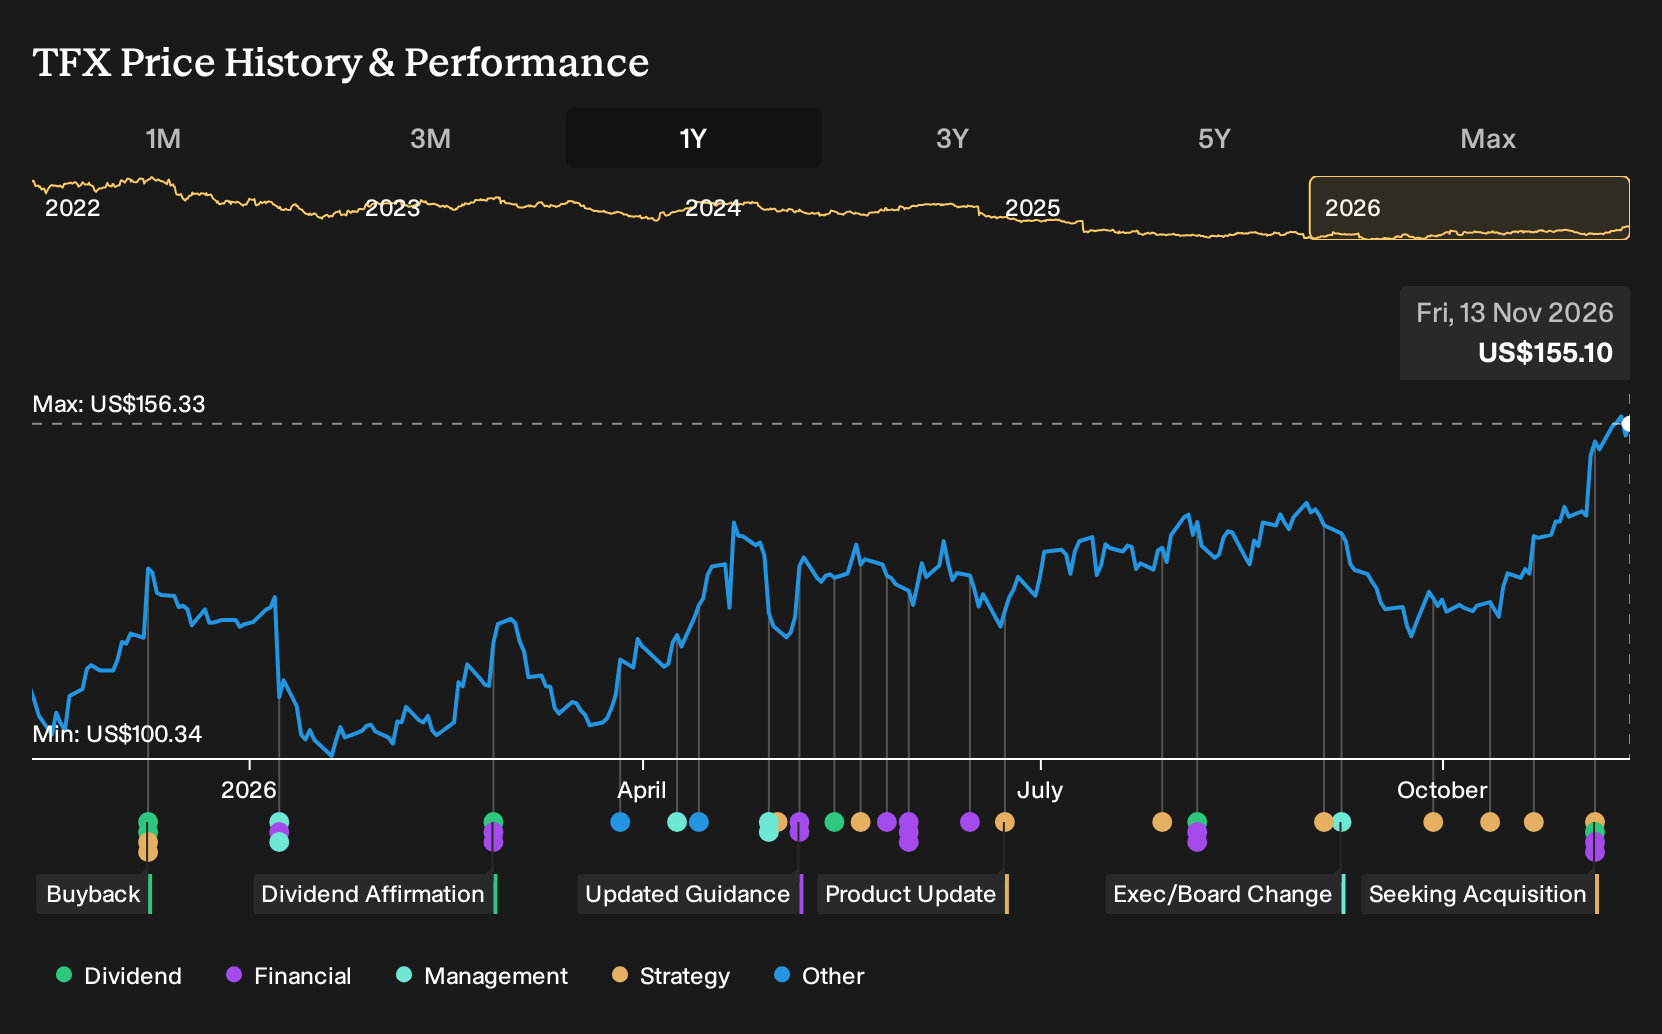
- Teleflex reported third quarter 2026 sales of US$567.78 million and net income of US$927.43 million, alongside higher full year GAAP EPS guidance despite a trimmed revenue outlook tied to foreign exchange.
- The company paired that earnings update with 9.96% of its shares repurchased under the current program and a US$0.34 quarterly dividend reaffirmed for payment on December 31, 2026.
- We now look at how Teleflex's stronger earnings guidance and profitability reset affect the company’s broader investment narrative.
Scan Teleflex alongside other capital-disciplined healthcare names that are actively returning cash to shareholders with our hand picked 6 dividend fortresses list.
Teleflex Investment Narrative Recap
To own Teleflex, you need to be comfortable with a medical devices group that is reshaping itself around Vascular, Interventional and Surgical while working through integration and cost reset work. The analyst consensus Narrative on Simply Wall St centers on margin uplift from restructuring and stranded cost offsets. The latest quarter, with higher GAAP EPS guidance and steady sales, supports that margin story more than it changes it.
The biggest near term swing factor still sits in execution in Interventional and delivery of cost savings. The trimmed revenue outlook tied to foreign exchange and prior softer Interventional trends keeps execution risk in focus. At the same time, the new GAAP EPS range suggests management sees enough levers on profitability to offset some of that pressure.
The most relevant update for that thesis is management’s plan to pursue tuck in acquisitions within Teleflex’s three core segments. Jason Weidman described a playbook that starts with R&D and capex for organic projects, then leans on excess capital for buybacks and eventually M&A that fits the existing capital allocation framework.
For you as a shareholder, that means the same cash that funded the recent 9.96% buyback could later support smaller deals that plug product gaps in Vascular, Interventional or Surgical. Execution on those transactions would feed straight into the Interventional turnaround and margin roadmap, while any integration missteps would compound the existing risk around stranded costs and restructuring benefits.
Teleflex's current analyst narrative points to revenues of US$2.5b and earnings of US$467.6 million by 2029, based on 4.2% yearly revenue growth and an earnings increase of about US$379.9 million from US$87.7 million today.
Uncover why Teleflex's fair value indicates a 4% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Teleflex’s tuck in acquisition plan is exactly where the most bearish analysts lean in. You see the buyback and dividend. They focus on the risk that future deals keep margins stuck near 19% and earnings closer to about US$332.1 million on US$2.5b revenue by 2029. Those pre news forecasts could shift, which is why it helps to compare several narratives before deciding what fits your view.
Explore 3 other Teleflex fair value estimates, including one that suggests it could be worth just $161.82.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Teleflex research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Teleflex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Teleflex's overall financial health at a glance.
Looking For More Ideas Beyond Teleflex?
Once you have a handle on Teleflex, it can help to line it up against a wider bench of potential opportunities, filtered for the traits you care about most.
- If capital preservation matters to you, start with a group of companies that historically show steadier profiles through our 31 resilient stocks with low risk scores.
- If you want to focus on businesses that the market may be underpricing based on their fundamentals, scan the 32 high quality undervalued stocks to see what else stacks up.
- If you prefer balance sheets that leave more room for shareholder returns and future investment, shortlist candidates using the list of solid balance sheet and fundamentals (24 results) to round out your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com