
Strong Earnings Results Could Be A Game Changer For Avient (AVNT)
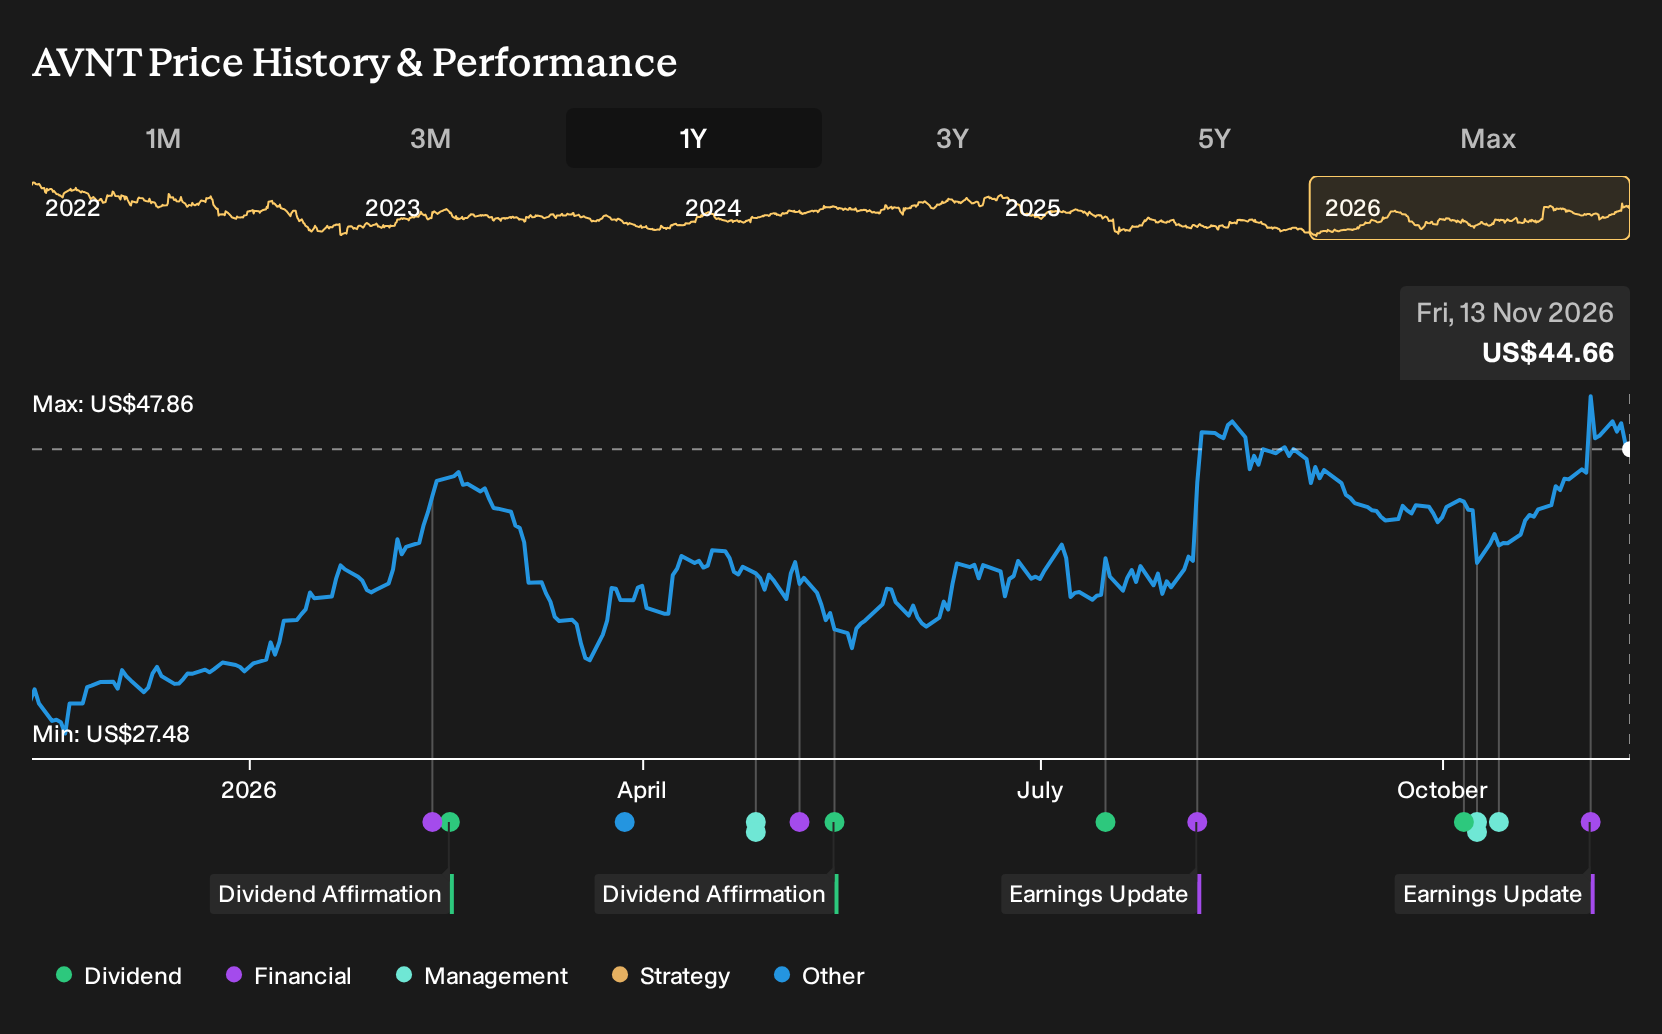
- Avient reported third quarter 2026 sales of US$891.2 million and net income of US$42.7 million, with basic EPS from continuing operations of US$0.47.
- For the first nine months of 2026, Avient recorded US$2,655.6 million in sales and US$163.2 million in net income.
- We will now look at how Avient's higher nine month net income may influence the investment narrative that was discussed before this earnings release.
Extend your read on Avient by comparing it with a hand picked group of financially robust peers using the list of solid balance sheet and fundamentals (24 results), which may offer similar earnings resilience.
Avient Investment Narrative Recap
For a shareholder in Avient, the core belief is that the shift toward higher value materials in electronics, healthcare and packaging can keep lifting earnings quality over time. The latest quarter and nine month results, with higher sales and net income than a year ago, support that operating angle and keep the analyst consensus Narrative on Simply Wall St broadly intact.
The near term catalyst still sits in execution on mix and productivity programs that aim to sustain margin progress after a period affected by one off items. The biggest immediate risk remains end market softness in transportation and other cyclical uses that could offset electronics and packaging demand and make recent earnings momentum less consistent.
The most relevant fresh data point is the third quarter and nine month 2026 report itself, since it lands directly against expectations that Avient can improve profitability while paying down debt. Sales of US$891.2 million in the quarter and US$2,655.6 million year to date, alongside net income of US$42.7 million and US$163.2 million, give investors updated proof points.
These results interact with catalysts around non PFAS packaging, electronics and productivity gains by showing how much of that thesis is currently flowing through the income statement. They also matter for a key risk flagged in the analyst consensus Narrative on Simply Wall St, that weaker transportation volumes or slower industrial demand could restrain operating leverage even if higher value segments perform relatively well.
Avient's current earnings are US$180.1 million and analysts are assuming revenue will grow by 4.0% a year, with earnings expected to reach US$376.2 million and revenues US$3.8b by 2029. This implies an earnings increase of about US$196 million from today.
Uncover why Avient's fair value indicates a 19% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The lowest analysts focus on a different catalyst for Avient. They worry that electronics and non PFAS packaging projects stay small, with revenue nearer US$3.8b and earnings around US$363.9m by 2029. You can see how that more cautious view might shift again once these latest Q3 and nine month numbers are fully absorbed.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Avient research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Avient. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Avient's overall financial health at a glance.
Looking For More Investment Ideas Beyond Avient?
If you want to stress test your view on Avient and widen your opportunity set, it helps to line it up against other companies with different strengths and income profiles. The Simply Wall St Screener can give you a curated set of stocks that match the type of balance sheet, income stream or risk level you prefer.
- If you care most about capital strength and staying power, compare Avient with companies from a list of solid balance sheet and fundamentals (24 results) that are built to handle tougher conditions.
- For readers hunting for mispriced opportunities, filter for companies that combine strong fundamentals with prices that look compressed using the 32 high quality undervalued stocks.
- If reliable cash returns are a priority, focus your search on companies with robust payouts and balance sheets using the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com