
Missed NeoGenomics' Rally? Here's What Buyers Saw
If NeoGenomics sat on your watchlist instead of in your portfolio, the move over the past year may feel like a missed shot. Holding NeoGenomics over the past year would have returned 54.9%, including dividends. That outcome invites a harder question. Back in November 2025, could the combination of aging populations and expanding digital health tools in oncology testing have been enough to justify owning a business still assuming higher future P/E multiples and better margins?
The move put NeoGenomics in the middle of this trade. Scan 36 healthcare AI stocks for other companies exposed to it.
The Two NeoGenomics Stories Investors Had To Weigh
The shares cost US$10.01 at the start of the period. Anyone looking at NeoGenomics then had to choose between two very different but plausible stories about what the next few years might look like.
The bullish narrative saw a Fair Value of US$14. This price was implied by its assumptions, built on aging populations and digital tools driving oncology testing and revenue growth of 10.7% a year, with profit margins eventually reaching 5.3%.
The bearish view pointed to a Fair Value of US$6.5. This was grounded in 8.5% annual revenue growth, margin pressure from underutilized pharma services, and a future P/E assumption of 21.8x if execution and regulatory risks stayed front and center.
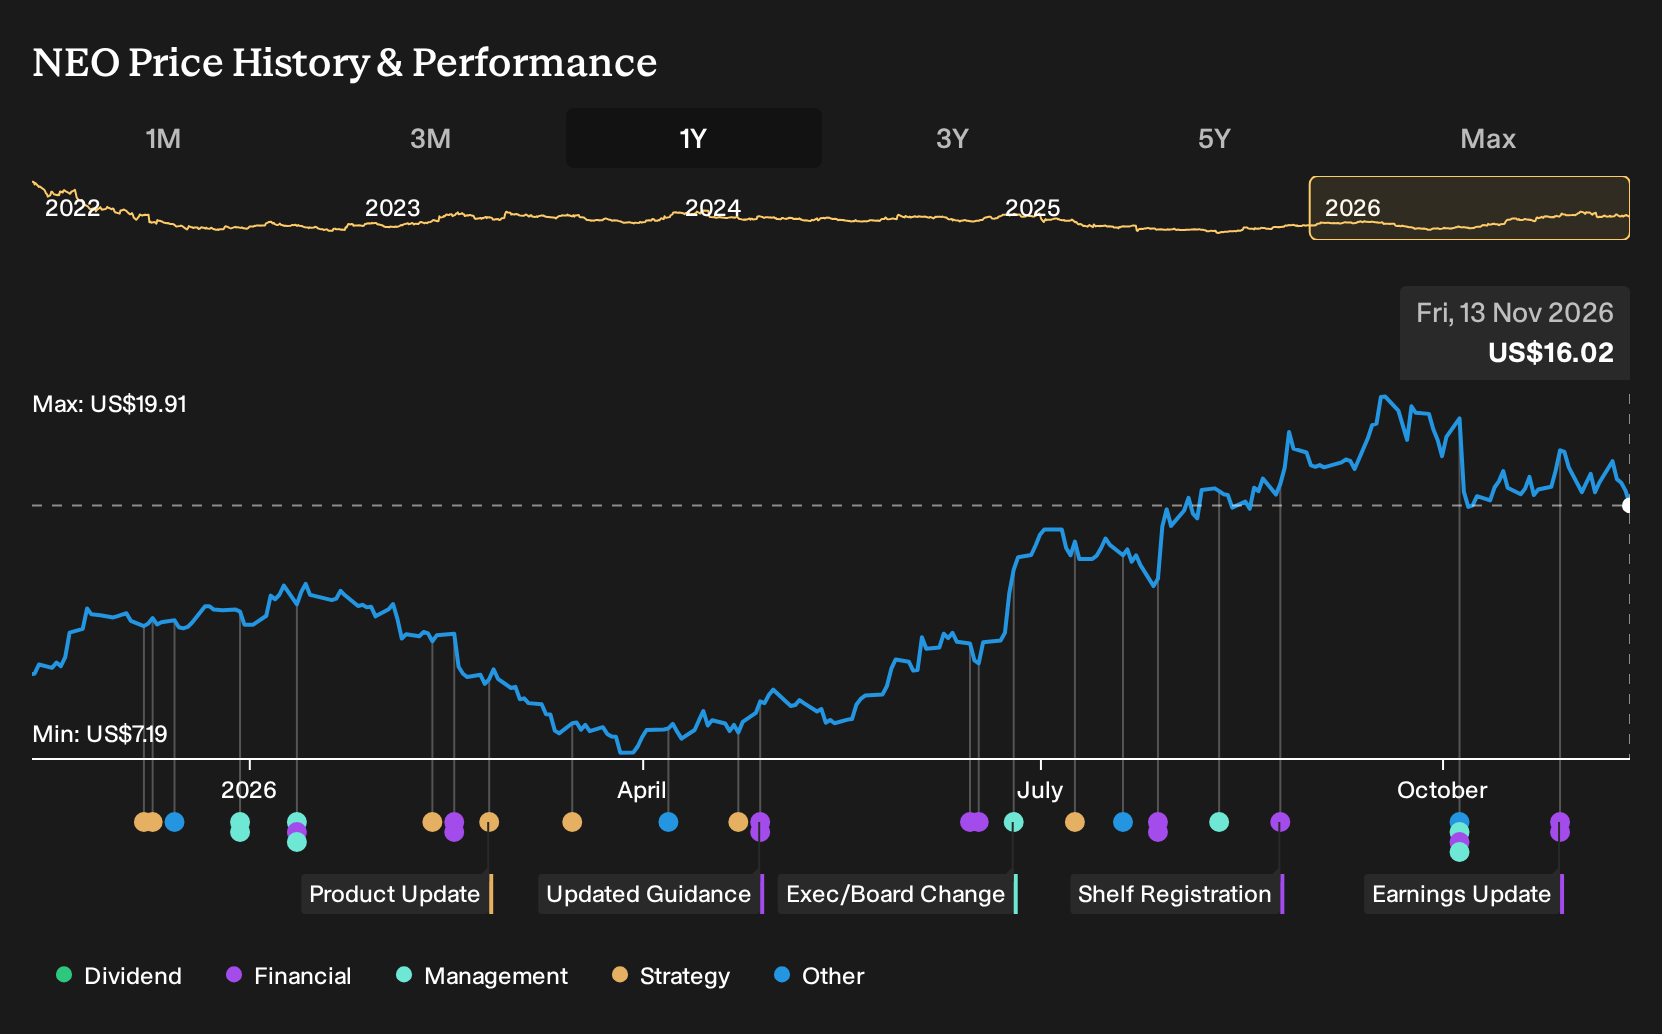
What The Results Changed For The NeoGenomics Story
Q3 2026 results showed NeoGenomics lifting revenue from US$187.8m to US$209.3m while the loss narrowed from US$27.1m to US$7.5m and net margin improved from -14.4% to -3.6%. Product wins in MRD coverage and the PTEN IHC companion test, plus raised 2026 guidance, leaned toward the bullish thesis, but continuing losses meant the profitability assumption stayed unproven. Overall, the evidence cut both ways.
The whole episode turned on whether higher margin potential would show up in reported numbers. For any other diagnostics stock built on a margin story, you would track net margin and net income side by side with guidance changes to see if the promised economics actually move closer to break-even.
What NeoGenomics Buyers Are Really Paying For Today
At today's share price of US$16.02, NeoGenomics is above the level a year ago, while the analyst consensus Narrative on Simply Wall St still places its Fair Value above the current quote.
That Narrative leans heavily on a richer mix of NGS and MRD testing and argues that today’s price still does not fully credit execution in community oncology and broader adoption of RaDaR ST and PanTracer.
"A continued mix shift toward higher value NGS and MRD testing, which currently represents about one third of clinical revenue on roughly 10% of volumes and is expected to move toward two thirds of revenue, is set to lift average unit prices and support gross margin and EBITDA margin expansion."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Before The Next Story Makes Headlines
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 47% below our estimate - uses an active youth audience and AI ad tools to offset weaker gaming revenue.
- Company 2 - 26% below our estimate - expands digital payments and underpenetrated credit, turning strong engagement into transaction-based income.
- Company 3 - 48% below our estimate - supplies accelerated computing platforms as major cloud customers increase AI-focused infrastructure capacity.
Three companies from the same screener. Open all 32 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com