
Calbee (TSE:2229) Posted Stronger Half Year Earnings, Is It Fully Priced?
What Calbee’s Latest Earnings Tell Investors
Calbee (TSE:2229) just posted half year earnings to September 30, 2026, with sales of ¥175,698 million and net income of ¥7,298 million, both above the prior year period.
Basic earnings per share from continuing operations reached ¥60.08 compared with ¥54.33 one year earlier. For anyone tracking this snack producer, the fresh figures give a concrete update on recent business performance.
Calbee’s latest half year results land against a backdrop of steady gains, with a 30 day share price return of 4.5% and a 90 day move of 6.0%, while the 1 year total shareholder return of 11.4% points to momentum building rather than fading.
Spot opportunities across the snacking and packaged foods space by scanning our hand picked 19 high quality undervalued stocks that pair fundamentals with recent share price momentum similar to Calbee.Calbee shares have already rewarded holders over the past year. The real puzzle now is whether the current price still offers a favourable trade off between risk and potential upside.
Price-To-Earnings Of 22x For Calbee: Is It Justified?
On valuation, Calbee trades on a P/E of 22x, which sits above both the Japanese food sector and an internal fair value yardstick based on its earnings profile.
The P/E ratio compares the current share price to earnings per share and gives a quick sense of how much investors are paying for each unit of profit. For a mature snacks producer like Calbee, that figure often reflects what the market is willing to pay for the stability and quality of those earnings.
Here, the stock changes hands on 22x earnings, while the broader JP Food industry averages 16.1x. The estimated fair P/E for the business is 19.1x. The current valuation therefore implies a richer price tag than both peers and that fair ratio level that the market could move towards if sentiment cools or earnings do not accelerate.
Explore the SWS fair ratio for Calbee.
Result: Price-to-Earnings of 22x (OVERVALUED)
Still, rich expectations around Calbee’s 22x P/E could be pressured if snack demand softens or if overseas expansion fails to pull its weight.
Find out about the key risks to this Calbee narrative.
Another View On Calbee’s Valuation
A second lens comes from our DCF model, which estimates Calbee’s future cash flow value at ¥2,836.16 per share compared with the current ¥3,228 price. That points to the stock trading above this cash flow based yardstick, so which signal do you trust more: earnings multiple or cash flow?
Look into how the SWS DCF model arrives at its fair value.
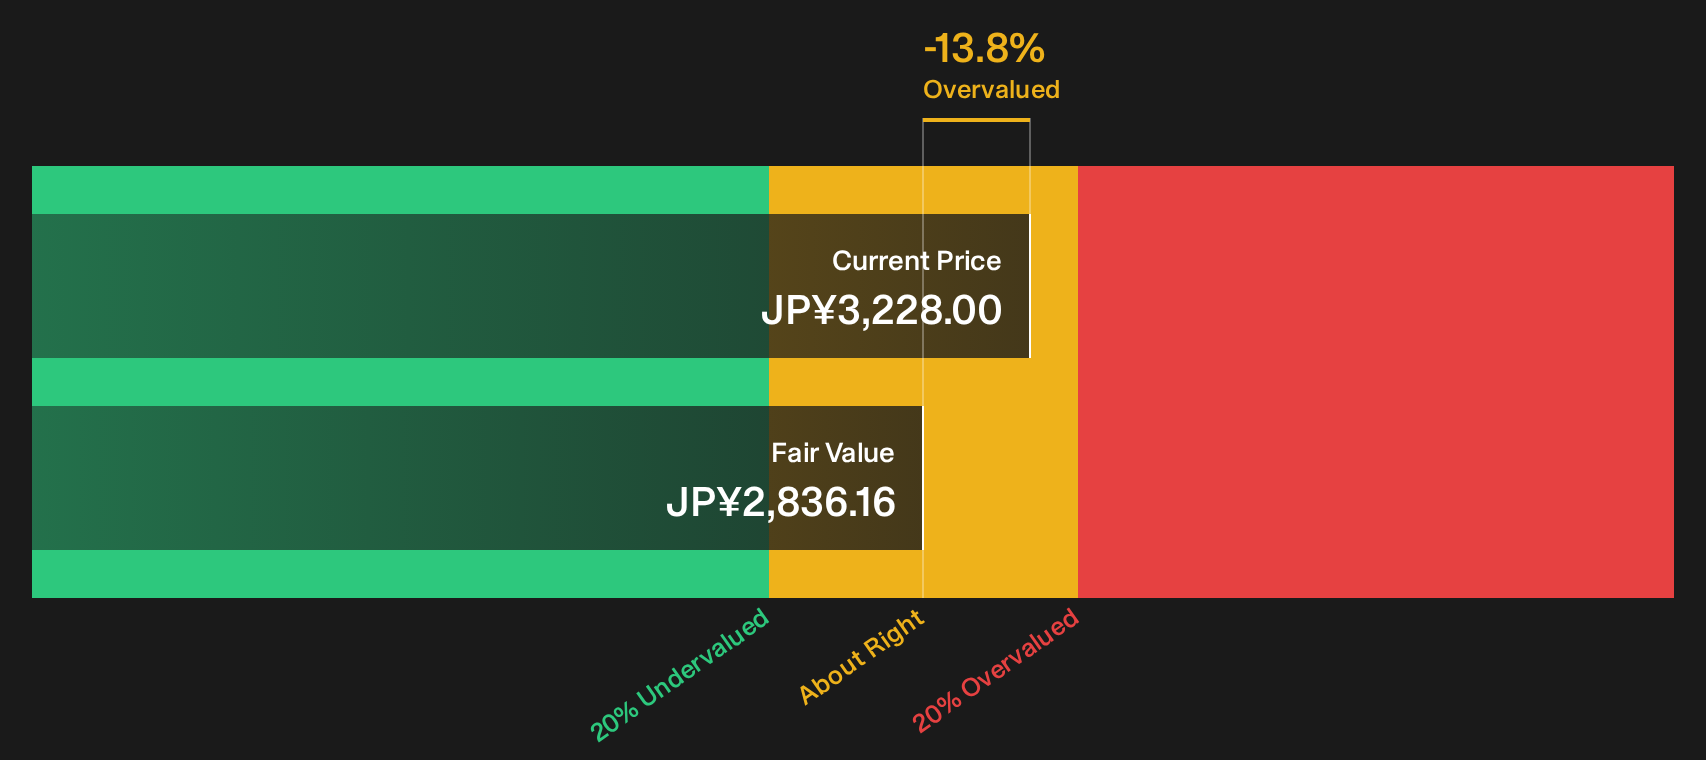
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Calbee for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 19 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this Calbee update leaves you torn between comfort and caution, move quickly from headline impressions to the underlying drivers in the numbers yourself. Then weigh both sides of the story by reviewing the 2 key rewards and 1 important warning sign.
Want More Ideas Beyond Calbee?
If Calbee has sharpened your appetite for opportunities, do not stop here. Put these screeners to work now so potential candidates do not slip past you.
- Target dependable cash generators by reviewing companies in the list of solid balance sheet and fundamentals (24 results) that pair financial strength with resilient fundamentals.
- Hunt for mispriced quality by scanning the 72 high quality undiscovered gems that combine solid metrics with lower market attention.
- Dial down portfolio stress by focusing on the 20 resilient stocks with low risk scores that score well on resilience and downside protection.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com