
Is Lowered Revenue Guidance Altering The Investment Case For Brightstar Lottery (BRSL)?
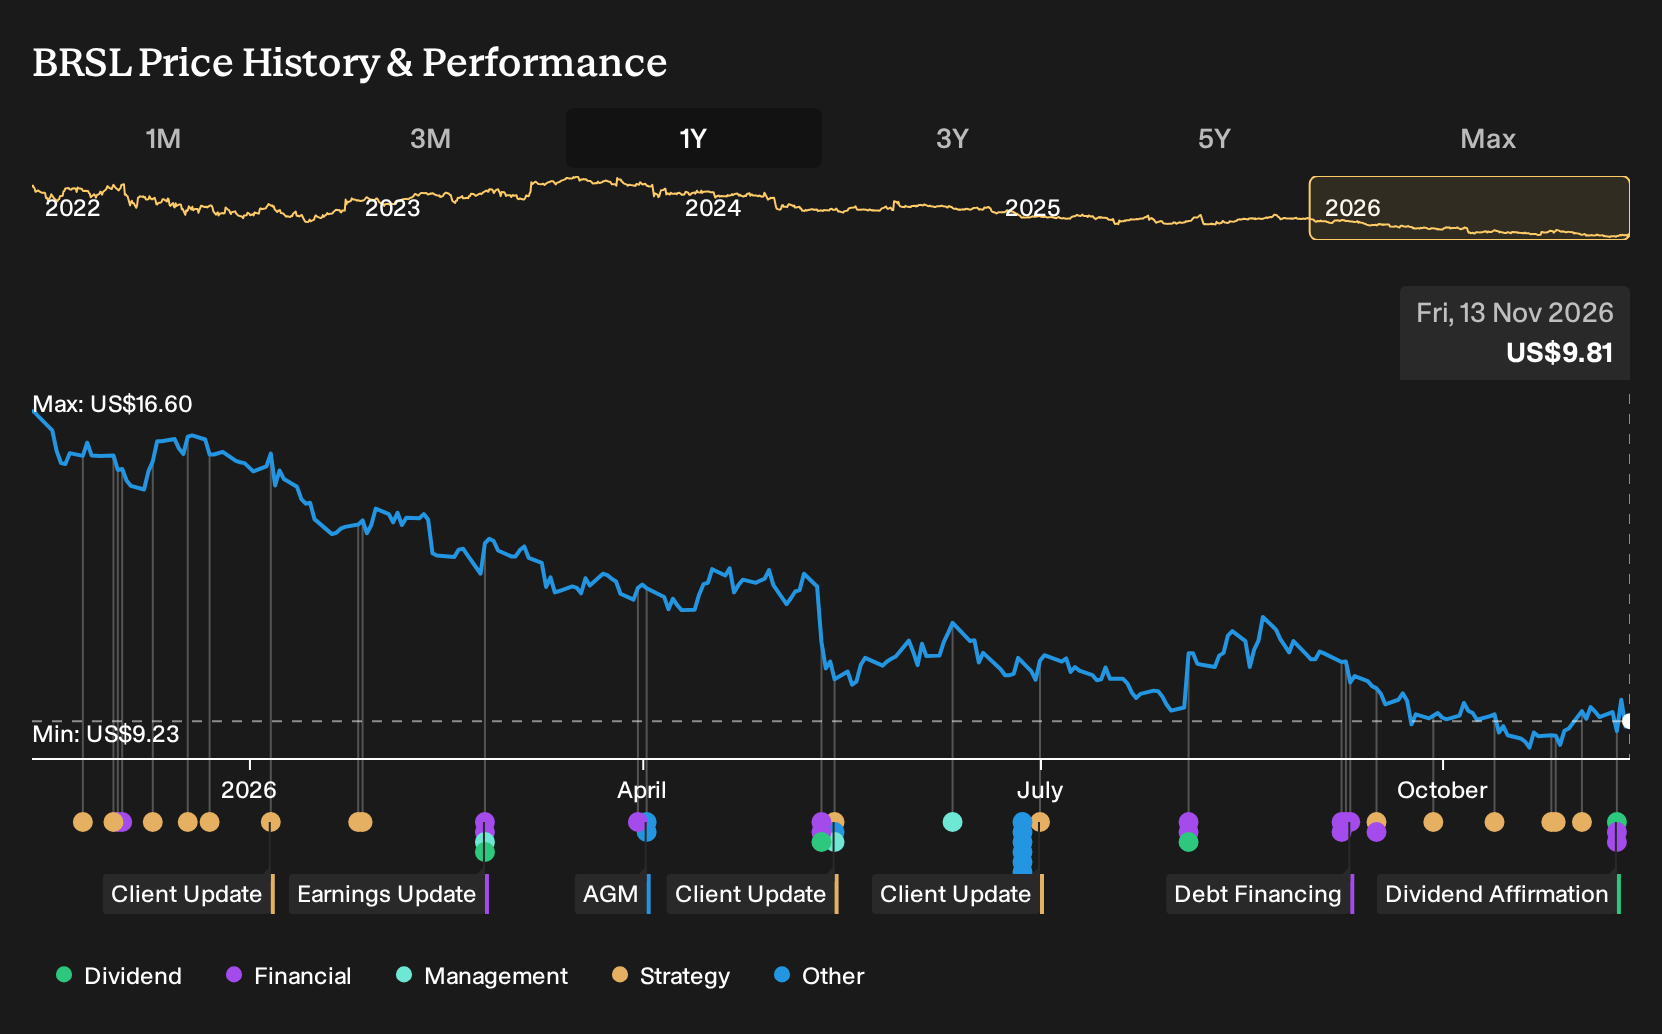
- Brightstar Lottery PLC cut its 2026 revenue guidance to US$2.435b to US$2.455b and reported third quarter revenue of US$607 million and net income of US$22 million, both lower than the same period in 2025, while keeping its quarterly dividend at US$0.23 per share.
- The contrast between softer earnings and the recent push into omnichannel lottery solutions and AI powered tools highlights execution pressure as Brightstar Lottery invests to reshape its digital mix.
- We will now look at how Brightstar Lottery's lowered full year revenue guidance reshapes the broader investment narrative around the business.
Scan how Brightstar Lottery's reset guidance compares to peers facing similar digital transition pressures by reviewing the hand picked 32 high quality undervalued stocks.
Brightstar Lottery Investment Narrative Recap
To own Brightstar Lottery, you need to believe the digital lottery transition and Italy B2C build out can matter more than quarterly jackpot swings. The reduced 2026 revenue guidance and softer third quarter earnings put more weight on execution. In the short term, the key catalyst is delivery on higher margin digital and service revenue that can support earnings quality.
The biggest near term risk is that weaker jackpot cycles and Italy specific disruptions continue while heavy capex and license payments keep interest coverage tight. The analyst consensus narrative on Simply Wall St emphasizes OPtiMa cost savings and recurring non wager revenue. The latest guidance reset makes progress on those pillars more important to watch.
The most relevant announcement here is the decision to keep the quarterly dividend at US$0.23 per share despite lower third quarter profit and trimmed full year revenue guidance. For you as a shareholder, that signals management is holding the payout steady in the face of softer recent results.
That choice ties directly into one of the key risks already flagged: dividend coverage and leverage. With interest payments not well covered by earnings and a high yield that is described as not well supported by cash flows, the dividend affirmation raises the bar on execution. Future cash generation from digital lottery and Italy B2C initiatives now matters even more if this payout is to remain sustainable.
Brightstar Lottery's current analyst narrative points to revenue of US$2.7b and earnings of US$119.2 million by 2029, based on revenue growth of 2.6% per year and a decline in profit from US$188.0 million today, which implies earnings would fall by about US$68.8 million over that period.
Uncover why Brightstar Lottery's fair value indicates a 57% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate take on Brightstar Lottery focuses on jackpot volatility risk. The most cautious analysts were already baking in 2029 revenue of about US$2.6b and earnings near US$97.1 million, well below consensus. That view paints a far more fragile earnings path, and this guidance cut could prompt those forecasts to shift again.
Explore another Brightstar Lottery fair value estimate, including one that suggests as much as 71% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Brightstar Lottery research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Brightstar Lottery. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Brightstar Lottery's overall financial health at a glance.
Looking for more investment ideas beyond Brightstar Lottery?
Once you have formed a view on Brightstar Lottery, it can help to line it up against other opportunities that fit your risk profile, income needs, and balance sheet preferences using the Simply Wall St screener.
- If you want income to do more of the heavy lifting, compare Brightstar Lottery's payout to a focused group of high yielding companies by reviewing 6 dividend fortresses.
- If capital preservation matters most to you right now, stress test your thesis against companies with more resilient financials using the 31 resilient stocks with low risk scores.
- If you are hunting for mispriced opportunities with strong fundamentals, broaden your watchlist with the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com