
USA Rare Earth (USAR) Stock May Trade At A Discount Following First Yttrium Shipments
USA Rare Earth has been in the spotlight after a steep share price slide, and the question now is whether the current valuation lines up with what its balance sheet is actually worth on paper. With the stock under pressure, investors are increasingly asking how today’s market price stacks up against the book value behind the rare earths story.
- Over the past year the share price has fallen 43.7%, which puts the spotlight firmly on whether the current level still reflects the value of assets on USA Rare Earth’s books.
- Recent moves into commercial shipments from Brazil and early magnet sales in the U.S. can shift how investors think about future returns on the projects that underpin the company’s recorded equity base.
- Your read on USA Rare Earth is one view; the desks covering it have another. See what analysts think USA Rare Earth's shares could be worth.
The issue now is whether USA Rare Earth’s current price can be squared with its book value when set against the industry average.
If you are weighing USA Rare Earth's steep share price decline against its asset base and want a broader comparison set, a focused screen of 33 best rare earth metal stocks may be useful.
Does USA Rare Earth Look Undervalued on Book Value?
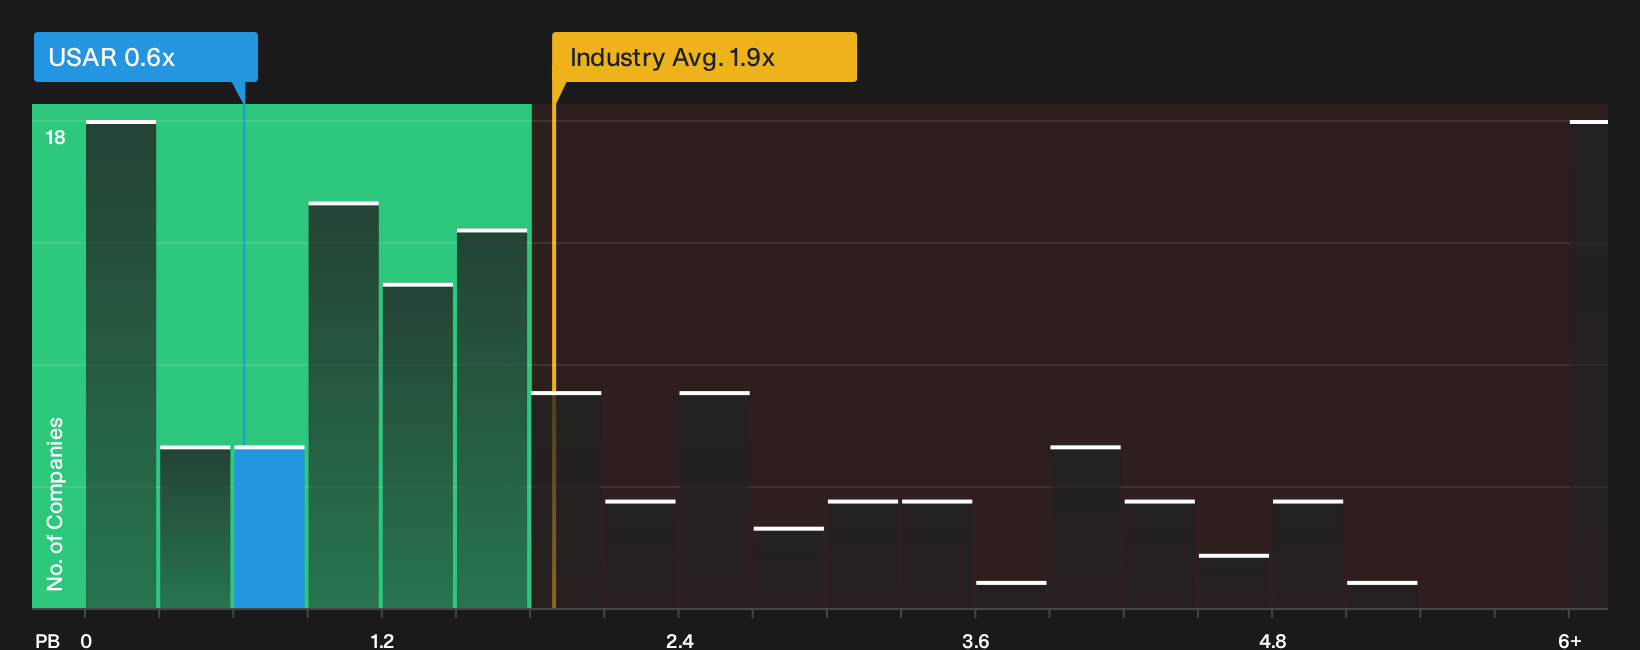
P/B is a useful lens for USA Rare Earth because investors are focused on the value of its projects and facilities relative to the share price. On this metric, the stock trades on a P/B of about 0.6x, compared with an industry average of roughly 1.9x for Metals and Mining companies. That means the market is valuing the equity well below the sector’s typical mark against net assets on the balance sheet.
Because USA Rare Earth has begun commercial shipments from Serra Verde and early magnet sales in the U.S., the current discount to the broader group suggests investors still price its asset base cautiously despite these milestones. The gap to the industry average P/B multiple points to a potentially attractive valuation on this measure, although you would still want to weigh project economics, political risk and future funding needs before relying on that signal too heavily. Explore the numbers behind USA Rare Earth's P/B valuation.
The USA Rare Earth Narrative: What Would Justify Today's Price?
Narratives for USA Rare Earth pick up where the P/B puzzle leaves off and explain which paths for growth, profitability and earnings would need to occur for the equity to be worth materially more or materially less than today’s valuation. Each scenario treats fair value as a thesis about USA Rare Earth's business that can be revisited over time, rather than a single fixed number. These scenarios are available on Simply Wall St's Community page.
Views on USA Rare Earth sit far apart, with one camp seeing deep value and another flagging major downside risk.
Bull case: 75% undervalued
According to the analyst consensus Narrative on Simply Wall St, the appeal starts with what USA Rare Earth is trying to build end to end.
"USA Rare Earth is building an integrated rare earth supply chain, from mining and processing to metal, alloy and magnet manufacturing, focused on ex China customers…"
Discover why this Narrative puts USA Rare Earth at 75% undervalued.
Bear case: 2373% overvalued
RetiredbutWorking, an investor in the Simply Wall St Community, argues that recent news flow does not fully support the current pricing.
"This development adds another federal endorsement to USAR’s role in strengthening the domestic critical materials ecosystem and highlights the growing policy focus on securing U.S. access to rare earth supply chains…"
Explore why this Narrative puts USA Rare Earth at 2373% overvalued.
One more piece of the USA Rare Earth story worth checking
Valuation only tells part of the USA Rare Earth picture, and the research checks on this business have surfaced specific areas of concern that are important to weigh for yourself. Take a closer look at 3 warning signs (2 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com