
Wise Group (WSE) Lifts Guidance After Strong Half Year Results But Is The Value Still There
Wise Group (WSE) is back in focus after its latest half year report, where management highlighted a 23% rise in net revenue, higher full year guidance, expanding products and a resolved regulatory investigation.
Wise Group’s latest update landed after a choppy stretch for the shares, with the 90 day share price return down 14.21% and the 30 day return down 6.49%, even though the stock still shows a 26.89% total shareholder return over three years.
Scan beyond Wise Group and size up other financially solid opportunities on our hand picked 32 high quality undervalued stocks that pair healthier balance sheets with cash flow support.
The recent jump in Wise Group after months of weaker returns forces a blunt question. Are investors finally catching up with the business, or has sentiment simply swung ahead of what the valuation supports?
Most Popular Narrative: 34% Undervalued
On the analyst consensus Narrative on Simply Wall St, Wise Group screens as materially undervalued, with a fair value of $16.94 against the last close of $11.23. This creates a clear gap between the model value and the current share price.
Customer balances of US$39b, including US$9b held through Wise Assets, together with an interest income framework that targets sharing 80% of yield above 1% with customers, create a recurring income stream that can support net revenue while still allowing for margin discipline.
See why 5 investors see Wise Group as 34% undervalued.
Result: Fair Value of $16.94 (UNDERVALUED)
Still, the bullish Wise Group story depends heavily on interest income from customer balances and on cost discipline, as marketing and servicing spend climb quickly.
Find out about the key risks to this Wise Group narrative.
Another View: Wise Group Through The P/E Lens
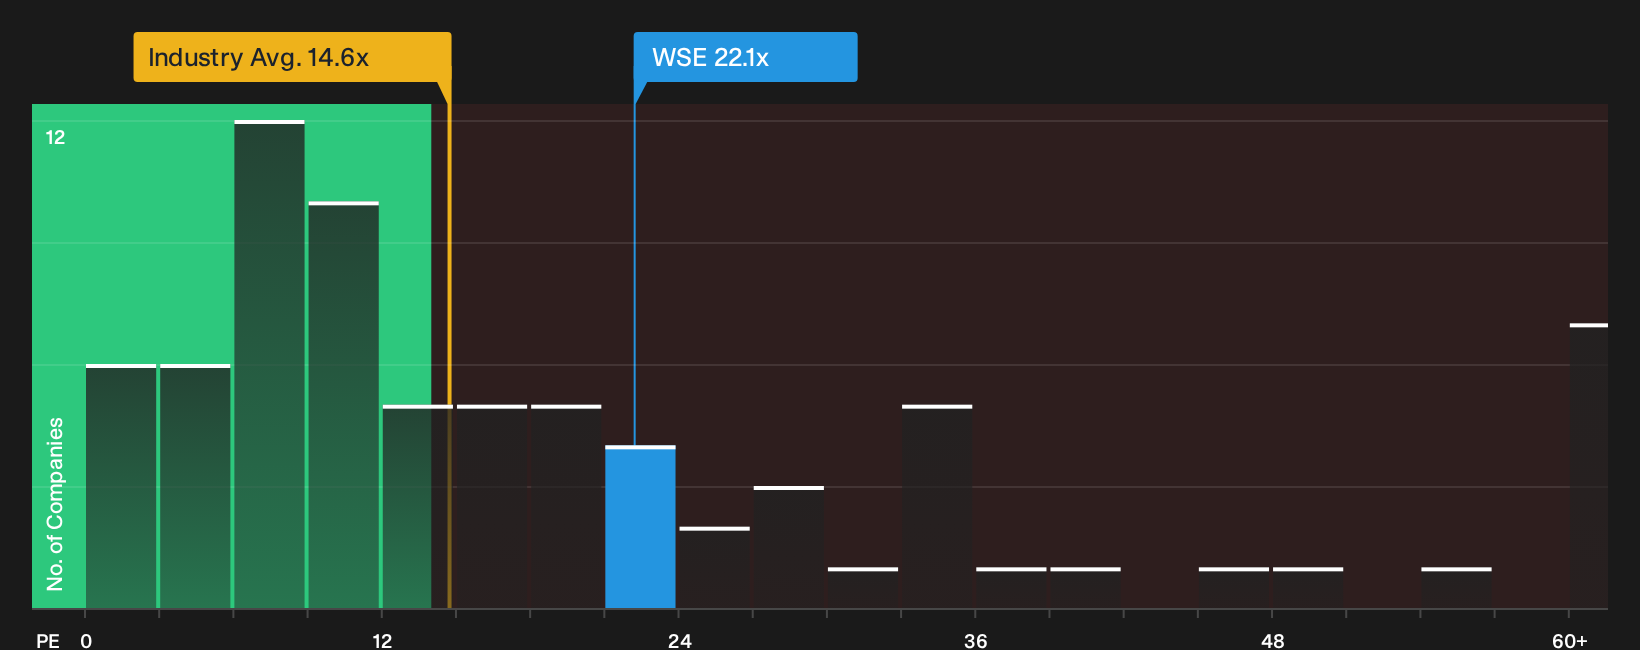
While the analyst narrative points to Wise Group as undervalued on future cash flows, the P/E picture is less forgiving. The stock trades on 22.1x earnings, compared with 14.5x for the US Diversified Financial industry and a fair ratio of 14.8x. That gap suggests investors already pay a premium, so it is worth asking how much margin for error is really left if expectations soften.
For a closer look at how that earnings multiple stacks up against peers and the fair ratio that the market could move towards, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Curious whether the optimism in this Wise Group story really holds up? Act quickly, check the data for yourself, and weigh the 3 key rewards.
Looking for more investment ideas beyond Wise Group?
If Wise Group has sharpened your focus, do not stop here. Broaden your watchlist with fresh, data backed ideas that keep you a step ahead.
- Target potential mispricing by scanning a curated pool of quality stocks that combine stronger fundamentals with attractive valuations through the 32 high quality undervalued stocks.
- Build income focused positions by zeroing in on companies with higher yields and robust payout support using the 6 dividend fortresses.
- Prioritise resilience by filtering for businesses with sturdier balance sheets and healthier fundamentals via the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com