
Biogen (BIIB), Why Is Its Latest Update Drawing Attention?
Biogen (BIIB) drew fresh interest after two product updates. Eisai and Biogen launched the weekly at home LEQEMBI Pen in Japan for early Alzheimer’s disease, while new dapirolizumab pegol lupus data outlined detailed 48 week clinical outcomes.
Those LEQEMBI and lupus updates landed against a backdrop of strong momentum in Biogen’s shares, with a 1 month share price return of 8.83% feeding into a 90 day gain of 20.76% and a year to date share price return of 42.50%. Total shareholder return over 1 year sits at 51.24%, while the 5 year total shareholder return is slightly negative, which shows recent enthusiasm is building off a much weaker longer term experience for holders.
Scan beyond Biogen to see how it stacks up against 36 healthcare AI stocks that are also working to reshape treatment through new therapies and smarter delivery.
After a 42.50% year to date share price gain and a current price of US$253.40, the key question for investors is straightforward: accept Biogen’s re-rating now, or wait and hope for a cheaper entry if valuation comes under closer scrutiny next?
Most Popular Narrative: 6% Undervalued
On Simply Wall St’s analyst consensus Narrative, Biogen’s fair value sits at $268.26 against a last close of $253.40, which points to a modest discount once analyst earnings and cash flow forecasts are factored in using a 7.87% discount rate.
Growing uptake of Biogen’s multi-product growth portfolio, which generated over US$1b of revenue in Q2 2026 and has now exceeded the multiple sclerosis portfolio, supports the idea that a broader base of neurology and immunology brands can increasingly carry total revenue and help stabilise earnings.
What is behind that shift in where value is coming from for Biogen, and how analysts are framing it in their models, is summed up in 65 investors see Biogen as 6% undervalued.
Result: Fair Value of $268.26 (UNDERVALUED)
Still, Biogen’s story can shift quickly if multiple sclerosis erosion deepens or if key launches like LEQEMBI and SKYCLARYS fall short of analyst expectations.
Find out about the key risks to this Biogen narrative.
Another View: What Biogen’s P/E Is Telling You
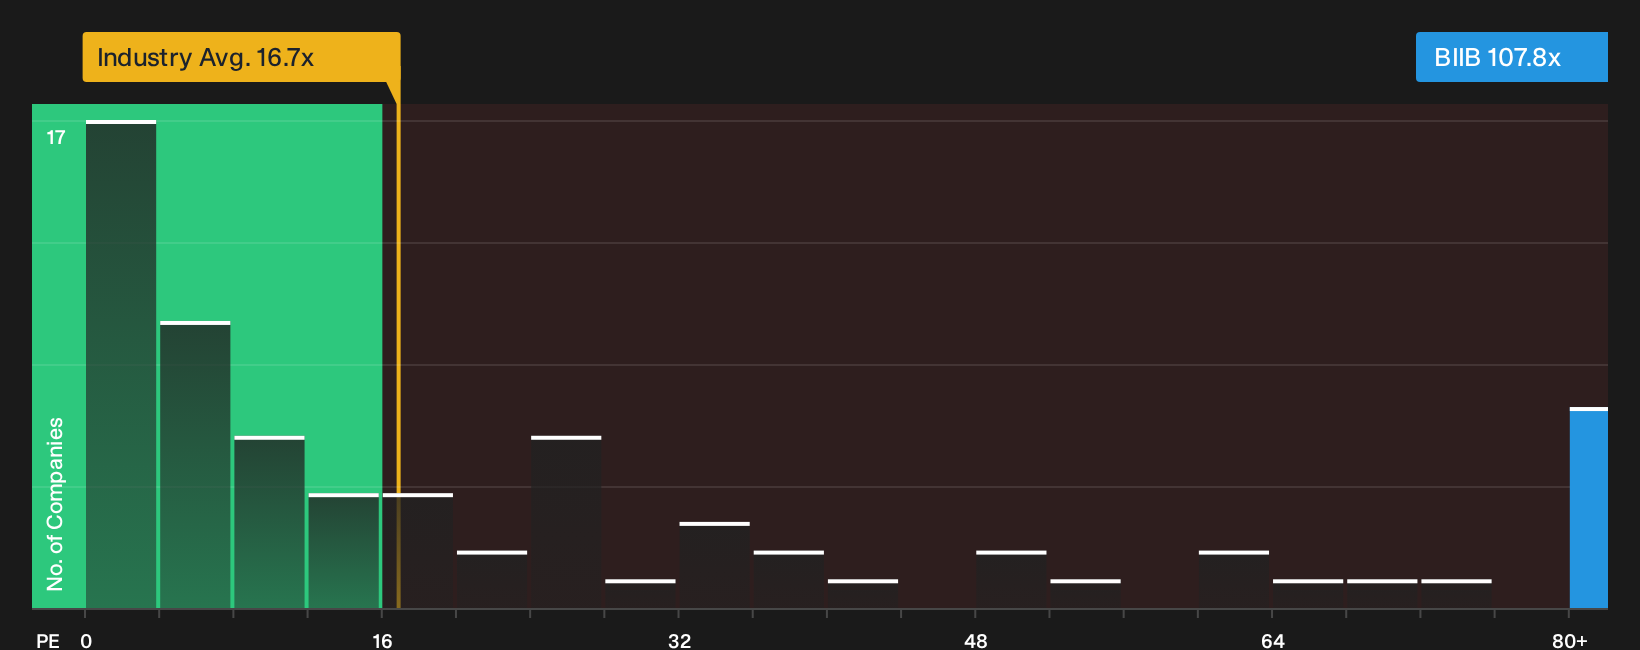
There is a very different signal once you stop looking at fair value targets and focus on price multiples. Biogen trades on a P/E of 107.8x, while the US Biotechs industry sits at 15.9x and closer peers average 30.1x. The fair ratio is 37.7x, which is the level the market could move towards over time.
That kind of gap points to real valuation risk if earnings forecasts or sentiment cool, since a reset even part of the way toward the fair ratio would mean a very different entry point for new buyers and a rougher ride for existing holders. The key question is whether you think Biogen’s future results justify staying this far ahead of both sector and peers.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Biogen’s valuation and risk reward profile can pull you in both directions. Move quickly, review the full data set and weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Biogen?
If Biogen has sharpened your focus on opportunity and risk, do not stop here. Use curated screens to surface fresh, data driven ideas in minutes.
- Start with resilience and filter for companies that pair durable balance sheets with steady fundamentals using the list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced opportunities by scanning a curated pool of quality companies trading below fair value through the 32 high quality undervalued stocks.
- Target under the radar prospects that still show robust financial footing by running the 20 high quality undiscovered gems before others catch on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com