
Chime Financial (CHYM) Raises Guidance, Is An 18% Undervalued View Still Justified?
Chime Financial (CHYM) raised its fourth quarter and full year 2026 revenue guidance, framing the latest move against fresh third quarter results that showed positive net income and higher sales versus a year earlier.
Chime Financial’s share price has climbed 27.08% year to date, and the 1 month share price return of 15.69% points to building momentum, while a 1 year total shareholder return of 77.51% suggests investors have recently reassessed both growth prospects and risk.
Scan how Chime Financial’s raised guidance and momentum compare with a hand-picked group of financially resilient opportunities inside the 31 resilient stocks with low risk scores.
Chime Financial’s guidance hike and swing into profit give one clear story, while the recent surge in the share price tells another. Is this move mainly about better fundamentals, or a mood shift in the market now reflected in valuation?
Most Popular Narrative: 18% Undervalued
The analyst consensus Narrative on Simply Wall St places Chime Financial’s fair value at $41.00 versus a last close of $33.55. This frames a discount built on detailed revenue and earnings forecasts that go well beyond a single quarter.
The ongoing shift toward digital, app based banking for everyday needs aligns directly with Chime's 9.1 million active members and high brand awareness. This can support member growth and higher payments revenue as more consumers choose online over branch based banking.
See why 3 investors see Chime Financial as 18% undervalued.
Result: Fair Value of $41.00 (UNDERVALUED)
Still, the Chime Financial story hinges on digital banking competition and credit product loss rates, either of which could challenge the current bullish narrative if conditions worsen.
Find out about the key risks to this Chime Financial narrative.
Another View: Chime Financial On Sales-Based Valuation
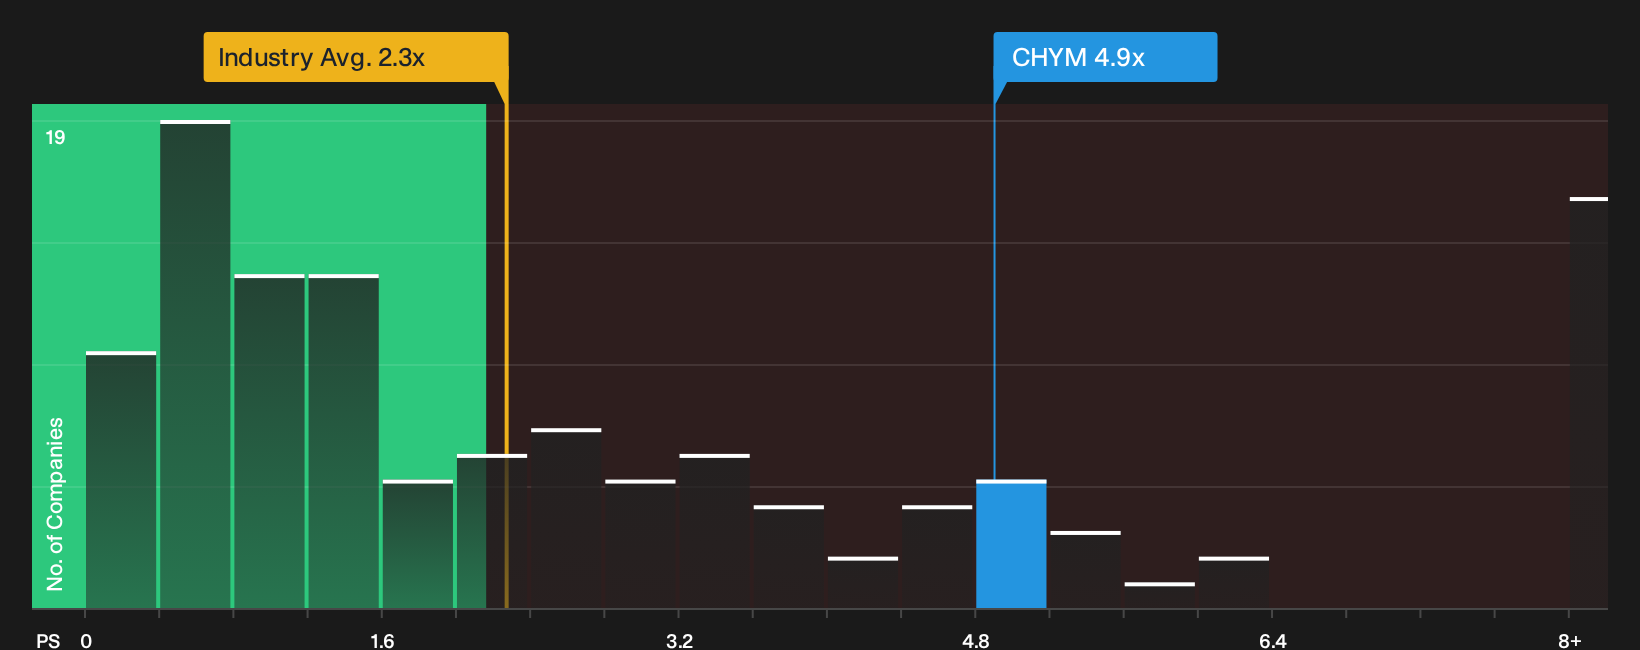
Chime Financial screens differently when price is compared to revenue. The P/S ratio sits at 4.9x, which is richer than both the US Diversified Financial industry average of 2.3x and the peer average of 4.2x, and above a fair ratio of 3.9x that the market could move toward over time. That gap points to a real question for investors. Is the current price reflecting future expectations too early, or is it simply the cost of backing a faster growing fintech story?
For a closer look at how this revenue based lens lines up against the bullish fair value view, have a look at See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Chime Financial story looks upbeat, yet some signals still pull the other way. Act while the data is fresh and judge it for yourself using the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Chime Financial?
If you stop with Chime Financial you risk missing other opportunities. Put a wider lens on your watchlist using the Simply Wall St Screener.
- Target potential mispricing by scanning a curated pool of quality candidates through the 32 high quality undervalued stocks.
- Strengthen capital protection by focusing on balance sheets that look resilient with the list of solid balance sheet and fundamentals (24 results).
- Boost your income watchlist by zeroing in on higher yielding opportunities using the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com