
How Phase 3 Trial Success At Mirum Pharmaceuticals (MIRM) Has Changed Its Investment Story
- Mirum Pharmaceuticals reported that its Phase 3 AZURE-4 trial of brelovitug for chronic hepatitis delta virus met the primary endpoint, with higher rates of combined virologic response and ALT normalization in both active treatment arms compared with no responses in the delayed treatment group.
- The AZURE-4 readout adds a second pivotal trial to Mirum Pharmaceuticals brelovitug dossier, aligning with plans for a U.S. regulatory filing by the first half of 2027 and reinforcing the company’s effort to build an additional rare disease revenue pillar beyond existing cholestasis therapies.
- This development provides new context for how Mirum Pharmaceuticals investment narrative may evolve as brelovitug’s AZURE-4 data contributes to the rare disease portfolio.
Scan how Mirum Pharmaceuticals fits alongside other rare disease and complex-care opportunities by comparing it against the curated shortlist in our 20 high quality undiscovered gems.
Mirum Pharmaceuticals Investment Narrative Recap
To own Mirum Pharmaceuticals, you need to believe its rare disease portfolio can broaden beyond LIVMARLI so the business is not so concentrated in one product. The analyst consensus Narrative on Simply Wall St assumes late stage programs eventually support higher revenue and lower R&D intensity. The AZURE 4 success fits that rare disease expansion story, but does not change the near term reliance on LIVMARLI.
The short term swing factor is execution on current product sales against higher 2026 guidance of US$715 million to US$720 million, while managing a third quarter net loss of US$40.77 million. The biggest risk is that programs like brelovitug or volixibat require more spending or face further regulatory delays, which could keep operating leverage under pressure.
The recent collaboration with GeneDx is tightly linked to Mirum Pharmaceuticals rare disease thesis. Sponsored exome testing in cholestasis, early onset cataracts and PBD ZSD directly supports the goal of finding more genetically confirmed patients who may be candidates for current and future therapies, including cholestasis medicines already contributing to sales guidance.
For catalysts, this testing effort can matter because earlier and clearer diagnosis may feed into uptake for LIVMARLI and any future bile acid or peroxisomal products if approved, which is central to the analyst consensus Narrative on Simply Wall St. The operational risk is that higher diagnosis rates do not automatically translate into treatment adoption at the pace needed to support the revenue and margin expectations implied in that view.
Analysts’ narrative for Mirum Pharmaceuticals points to revenues of US$1.4b and earnings of US$425.9 million by 2029, anchored on an assumed 28.1% yearly revenue growth rate and an earnings swing of roughly US$1.33b from current earnings of a US$903.9 million loss to the forecast profit level.
Uncover why Mirum Pharmaceuticals' fair value indicates a 63% potential upside to its current price, which could narrow quickly.
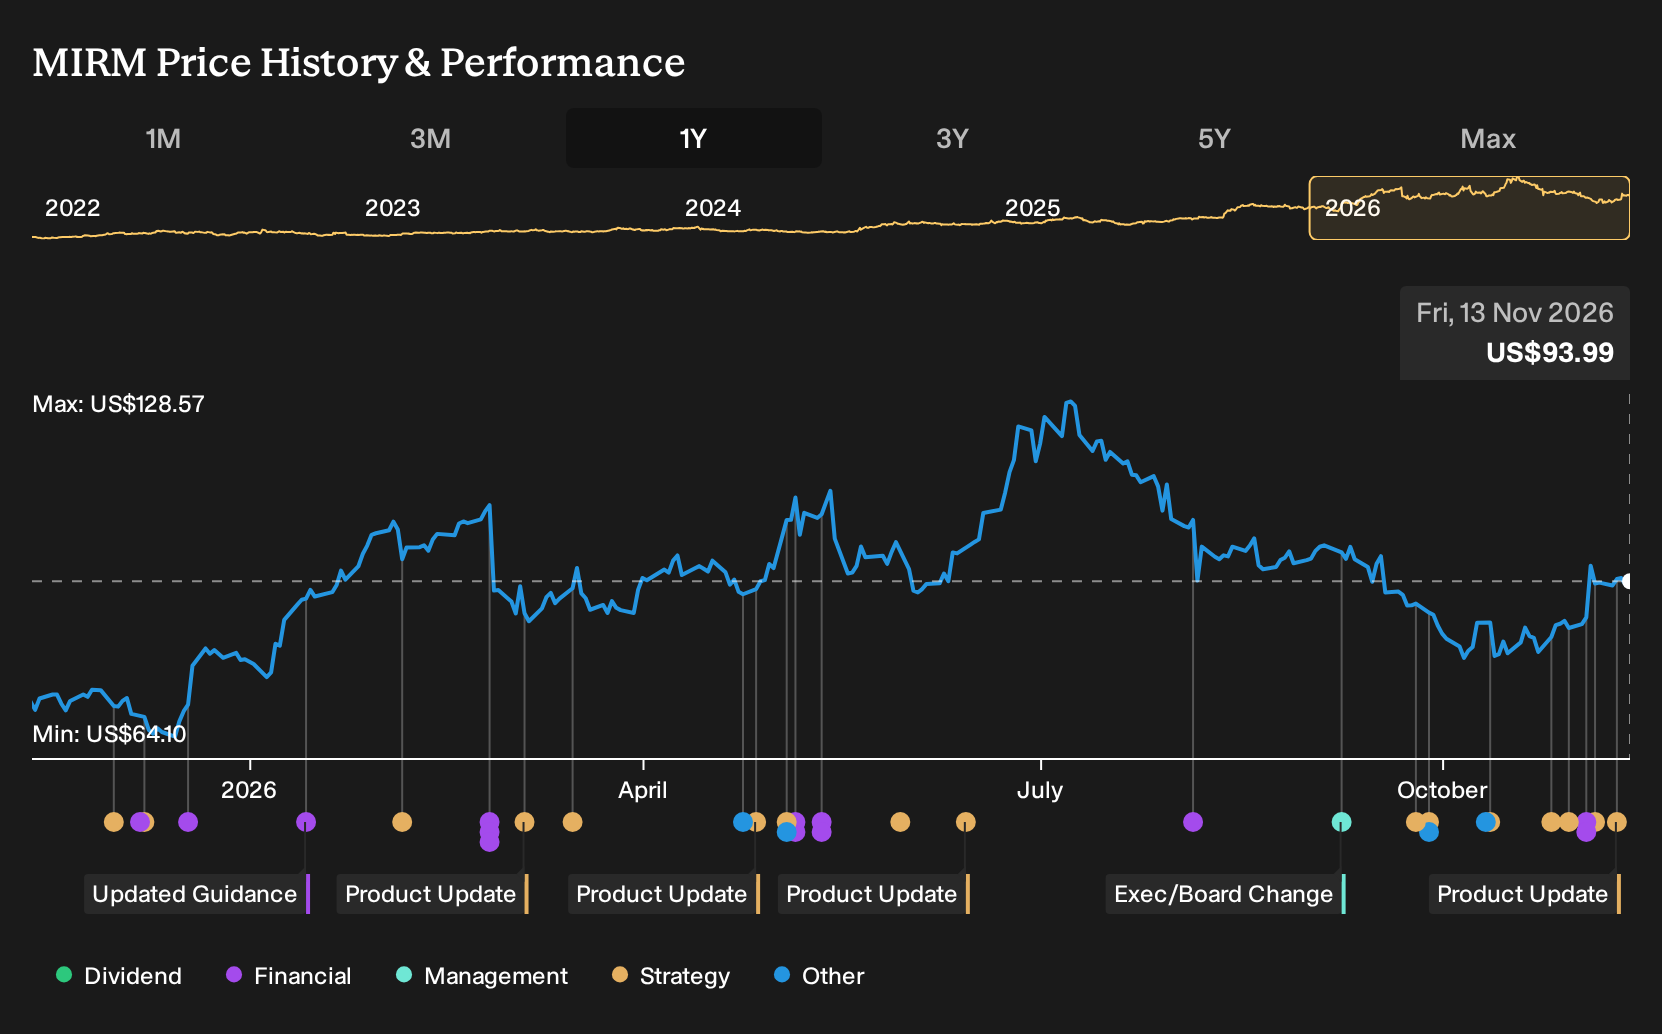
Exploring Other Perspectives
Some of the most optimistic analysts framed Mirum Pharmaceuticals around Atebrioz and volixibat approvals, expecting about US$1.4b of revenue and US$642.9 million of earnings by 2029. You now have AZURE 4 in the mix, yet those forecasts were set before this data. Treat them as one possible storyline and then compare several others.
Explore 2 other Mirum Pharmaceuticals fair value estimates, including one that suggests as much as 348% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Mirum Pharmaceuticals research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Mirum Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mirum Pharmaceuticals' overall financial health at a glance.
Looking For More Ideas Beyond Mirum Pharmaceuticals?
If Mirum Pharmaceuticals has sharpened your thinking on rare disease and complex-care opportunities, use that same lens across the wider market. The Simply Wall St Screener lets you filter for different styles, so you can match ideas to your own risk tolerance and income goals rather than copying consensus.
- For investors who want potential upside with a margin of safety, start by scanning a 32 high quality undervalued stocks that already combine quality fundamentals with discounted prices.
- If resilience matters more to you than rapid gains, focus on a 31 resilient stocks with low risk scores where balance sheets and risk profiles score more conservatively.
- When capital preservation and financial strength come first, anchor your watchlist around a list of solid balance sheet and fundamentals (24 results) that filters for robust cash, manageable debt and healthier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com