
Learn Why The Bull Case For Camtek (CAMT) Could Change Following Strong Earnings Report
- Camtek reported third quarter 2026 sales of US$161.29 million and net income of US$42.84 million, with basic earnings per share from continuing operations of US$0.92.
- The nine month 2026 figures, including US$416.2 million in sales and US$97.79 million in net income, show how Camtek converted higher demand into stronger profitability per share.
- This article examines how Camtek's higher net income may influence the existing AI and advanced packaging investment narrative around the stock.
Scan beyond Camtek's strong earnings and see how other chip and packaging players stack up in our curated list of 53 AI infrastructure stocks powering the AI build out.
Camtek Investment Narrative Recap
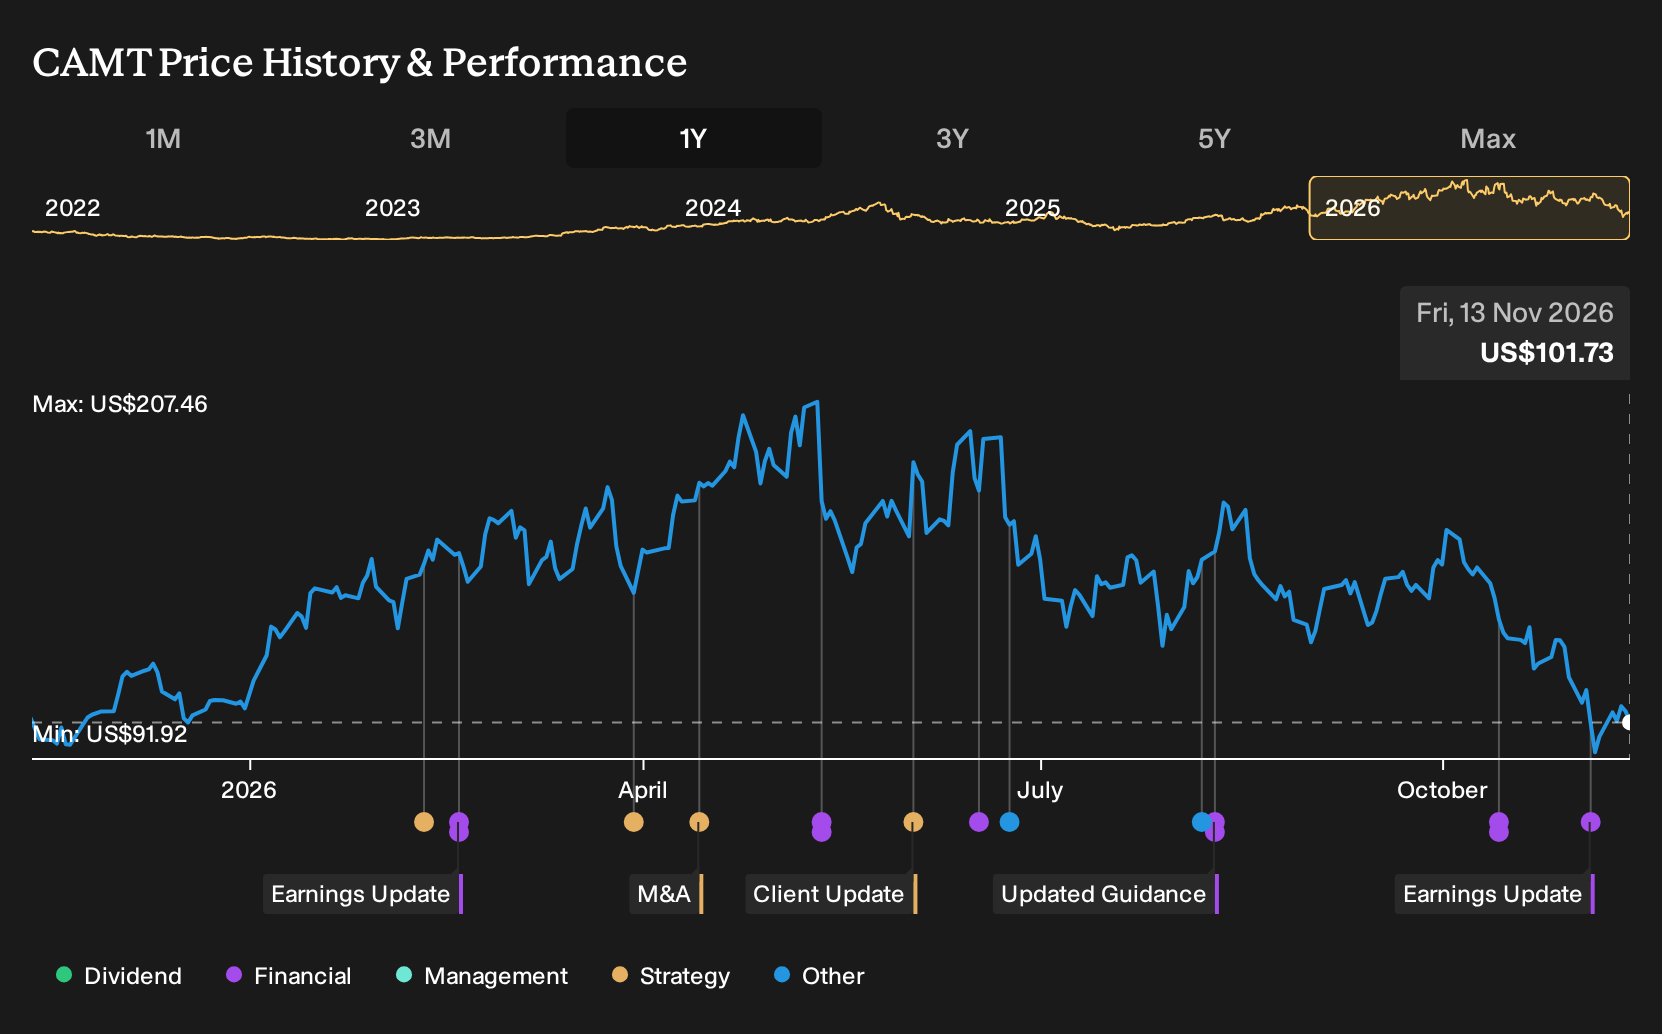
To own Camtek, you need to believe the AI driven advanced packaging story can keep translating into orders across Hawk, Eagle G5 and related tools. The latest quarter, with US$161.29 million in sales and US$42.84 million in net income, supports that thesis but also raises the bar for what “strong” now looks like.
The key short term catalyst is still effective conversion of the more than US$600 million 2026 year to date order book into high margin shipments. The biggest risk remains concentrated exposure to advanced packaging and HBM customers. If their spending plans soften or shift, this quarter alone does not offset that vulnerability.
The analyst consensus narrative on Simply Wall St leans heavily on AI and high performance computing demand supporting multi year advanced packaging orders. The latest earnings update, including US$416.2 million in nine month sales and US$97.79 million in net income, provides evidence that Camtek is currently executing against that order flow.
That same narrative highlights margin ambitions tied to a richer mix of Hawk and Eagle G5 systems and new German capacity targeted for late 2026. The most relevant link to this earnings report is management’s ability to turn that backlog into sustained profitability per share while managing risks related to pricing pressure, costs and any pause in HBM related projects.
Camtek's current narrative assumes revenue will compound at 26.2% a year, taking revenues to US$1.0b and earnings to US$706.2m by 2029. This implies a very large earnings increase from US$37.7m today.
Discover how Camtek's fair value indicates a 67% potential upside to its current price. This gap could narrow quickly if sentiment follows the earnings trend.
Exploring Other Perspectives
One alternative angle you might consider focuses on valuation risk rather than AI demand. The lowest analysts were already pencilling in 2029 revenue of about US$904.1 million and earnings of US$669.0 million, yet still landed on a lower fair value. Those forecasts came before this Camtek earnings surprise, so their storyline could shift meaningfully from here.
Explore 4 other Camtek fair value estimates, including one that suggests as much as 32% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Camtek research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Camtek. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate Camtek's overall financial health at a glance.
Looking for more investment ideas beyond Camtek?
Once you are comfortable with where Camtek sits in your portfolio, it can help to scan a wider field of opportunities using focused stock lists inside the Simply Wall St Screener.
- If you want potential mispricing combined with quality fundamentals, start with a curated set of 32 high quality undervalued stocks that may warrant a closer look.
- For income focused investing, filter for companies that prioritize cash returns to shareholders through a collection of 6 dividend fortresses that already clear the 5% yield bar.
- When capital preservation matters most, narrow your search to a 31 resilient stocks with low risk scores and use that as a watchlist for sturdier business models.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com