
What Woodside Energy Group Shareholders Got Right
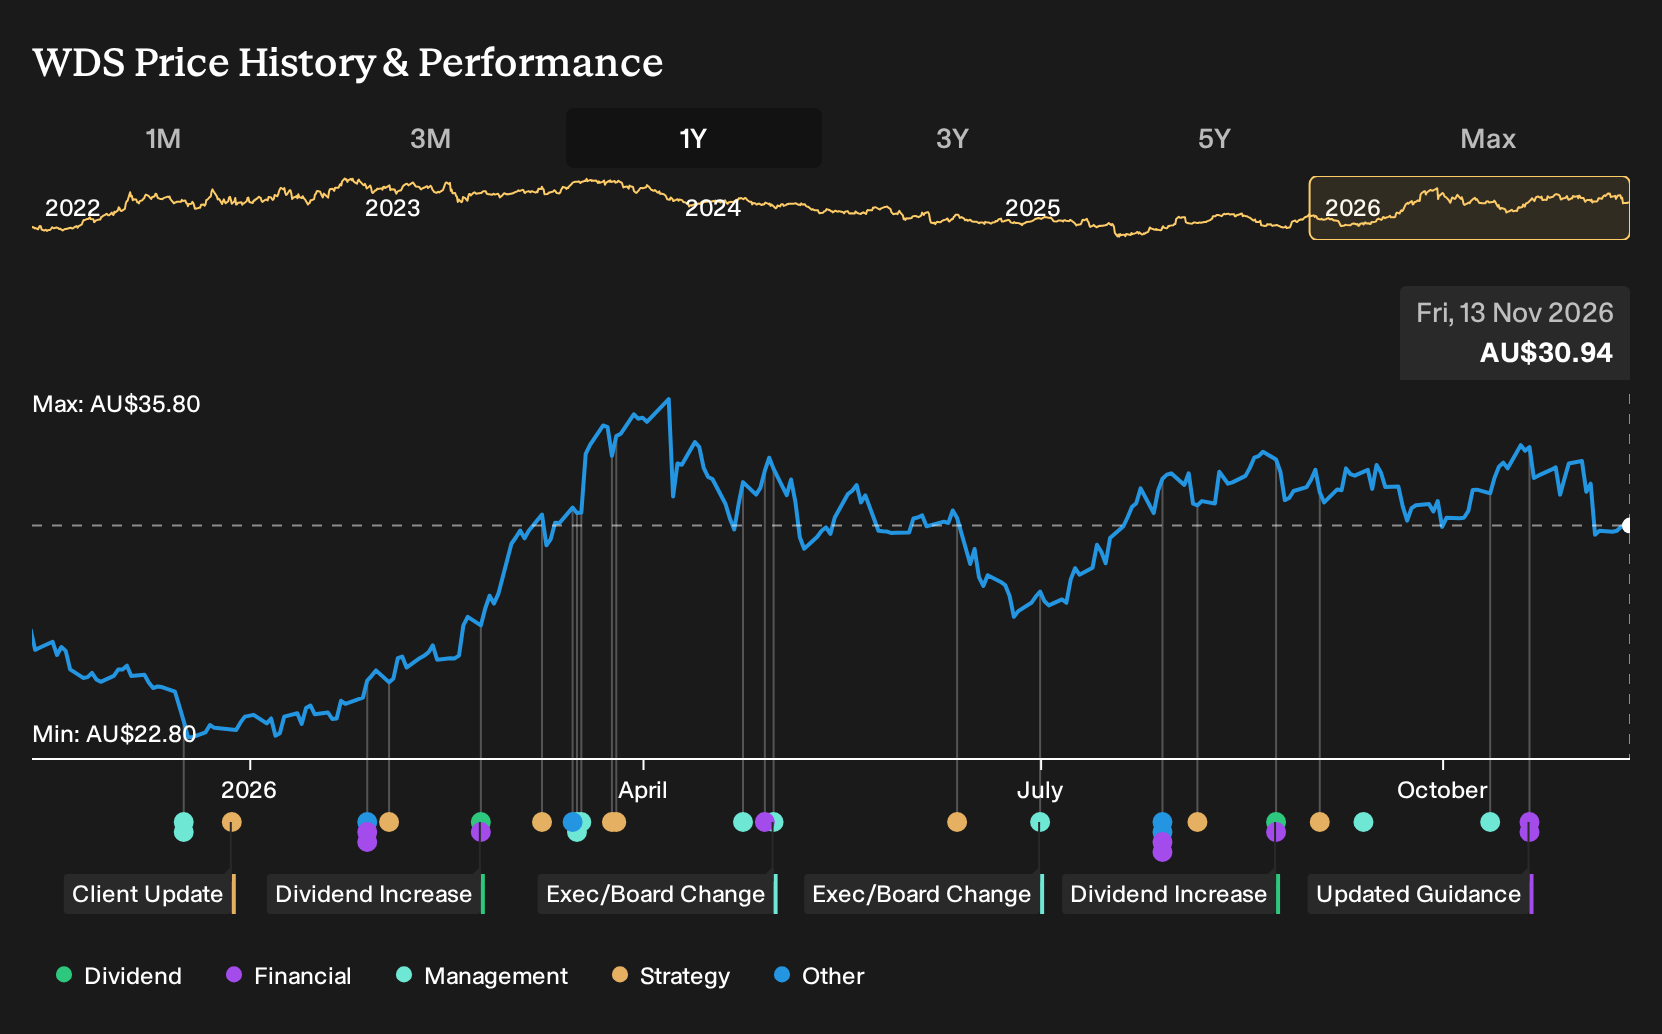
Woodside Energy Group did not start this period quietly. Early on, it locked in a 20-year LNG supply deal with QatarEnergy for the under-construction Louisiana LNG project, tying future cargoes to a long contract while the plant is still on the drawing board. Holding Woodside Energy Group over the past year would have returned 24.2%, including dividends. If you were deciding on 13 November 2025, how confident would you have felt that these kinds of commitments would truly benefit equity holders?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Woodside Energy Group. Zero in on 2 high quality undervalued stocks for companies trading below our estimates.
The Two Woodside Energy Group Stories Investors Had To Weigh
The shares cost A$26.16 at the start of the period, and anyone looking at Woodside Energy Group then had to choose which future felt more reasonable.
The bullish narrative carried a Fair Value of A$43.54 and leaned on LNG expansion. It assumed revenue would grow 3.9% a year and that a P/E of 20.9x on 2028 earnings was justified.
The bearish view put Fair Value at A$23.62 and focused on decarbonization risk. It assumed revenue would fall 5.2% a year and margins would contract to 8.0%.
What The Evidence Did To The Woodside Energy Group Argument
Woodside Energy Group’s 20-year LNG supply agreement with QatarEnergy for the Louisiana project reinforced the optimistic case that long contracts could underpin cash flows. H1 2026 results pointed in the same direction, with revenue at US$7.45b and net income at US$1.67b, compared with US$6.59b and US$1.32b in H1 2025, and net margin rising to 22.5%. The evidence supported the optimistic case.
The key lesson is simple. When a thesis leans on big project build outs, test it against two hard numbers over time: the share of capacity covered by long term contracts, and the trend in reported net margin.
What Woodside Energy Group's 24% Run Already Prices In
Woodside Energy Group trades at A$30.94 after a 24.2% gain over the past year, and the bullish analyst Narrative on Simply Wall St places its Fair Value above that level.
That Narrative leans on cost cuts, LNG project execution and portfolio clean up, and argues today’s price still does not credit disciplined capital allocation translating into higher long term returns.
"The decision to retire the prior $5b new energy spend ambition and require emerging low carbon projects to compete directly with hydrocarbons for capital creates scope for a smaller but higher returning future project set, which can lift return on invested capital and support earnings quality beyond what headline volume growth alone implies."
One Narrative disagrees with today's price. → See where this Narrative says Woodside Energy Group should trade
Which Company Could Surprise You Next?
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 31% below our estimate - leans on large-format stores to drive electronics and appliances sales into online channels.
- Company 2 - 15% below our estimate - shifts customers to unified contracts bundling cloud, security and AI services under one provider.
- Company 3 - 27% below our estimate - targets repeat demand for truck and bus parts as operators extend vehicle lifecycles and maintenance.
That is three of the list. See the full list of 12 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com