
Takeda Pharmaceutical (TSE:4502) Launches ORZEYFUL In The United States, Is The Stock Expensive?
Takeda Pharmaceutical’s ORZEYFUL launch and what it means for the stock
Takeda Pharmaceutical (TSE:4502) has moved ORZEYFUL from FDA approval in August to full commercial availability in the United States, placing the first orexin receptor 2 agonist for narcolepsy type 1 directly into the prescription channel.
The ORZEYFUL launch lands at a time when Takeda Pharmaceutical’s momentum has been building, with the share price up 17.61% over the past 30 days and 40.89% year to date. The 1-year total shareholder return of 61.38% points to strong recent performance that extends into an 86.03% total shareholder return over three years and 165.96% over five years.
Scan how Takeda Pharmaceutical’s narcolepsy breakthrough compares with other healthcare plays showing strong fundamentals in our curated list of solid balance sheet and fundamentals (24 results)
Taken together, ORZEYFUL’s launch and Takeda Pharmaceutical’s sharp share price move set up an immediate fork in the road. Is it more sensible to commit capital now, or to wait for a calmer entry point as the valuation picture comes into focus?
Most Popular Narrative: 2% Overvalued
Taken against the last close of ¥6,926, the analyst consensus Narrative on Simply Wall St pegs Takeda Pharmaceutical’s fair value at ¥6,759.56, pointing to a small premium in the current price while hinging heavily on successful new drug rollouts.
The anticipated moderation and eventual stabilization of VYVANSE generic erosion after FY2025 would remove a major headwind for revenues, allowing Takeda's core products and launch products to drive top line and earnings recovery.
Rapid progress and positive late stage data from Takeda Pharmaceutical's late stage launches such as ORZEYFUL and MIMRYLO, along with a broader pipeline that includes zasocitinib, elritercept and other agents, keeps open the path to multiple new revenue streams.
See why 17 investors see Takeda Pharmaceutical as 2% overvalued.
Result: Fair Value of ¥6,759.56 (OVERVALUED)
Still, two pressure points sit in the background: faster than expected generic competition for ENTYVIO or VYVANSE, and weaker uptake of new launches, could quickly challenge that story.
Find out about the key risks to this Takeda Pharmaceutical narrative.
Another View: Takeda Pharmaceutical Through A Cash Flow Lens
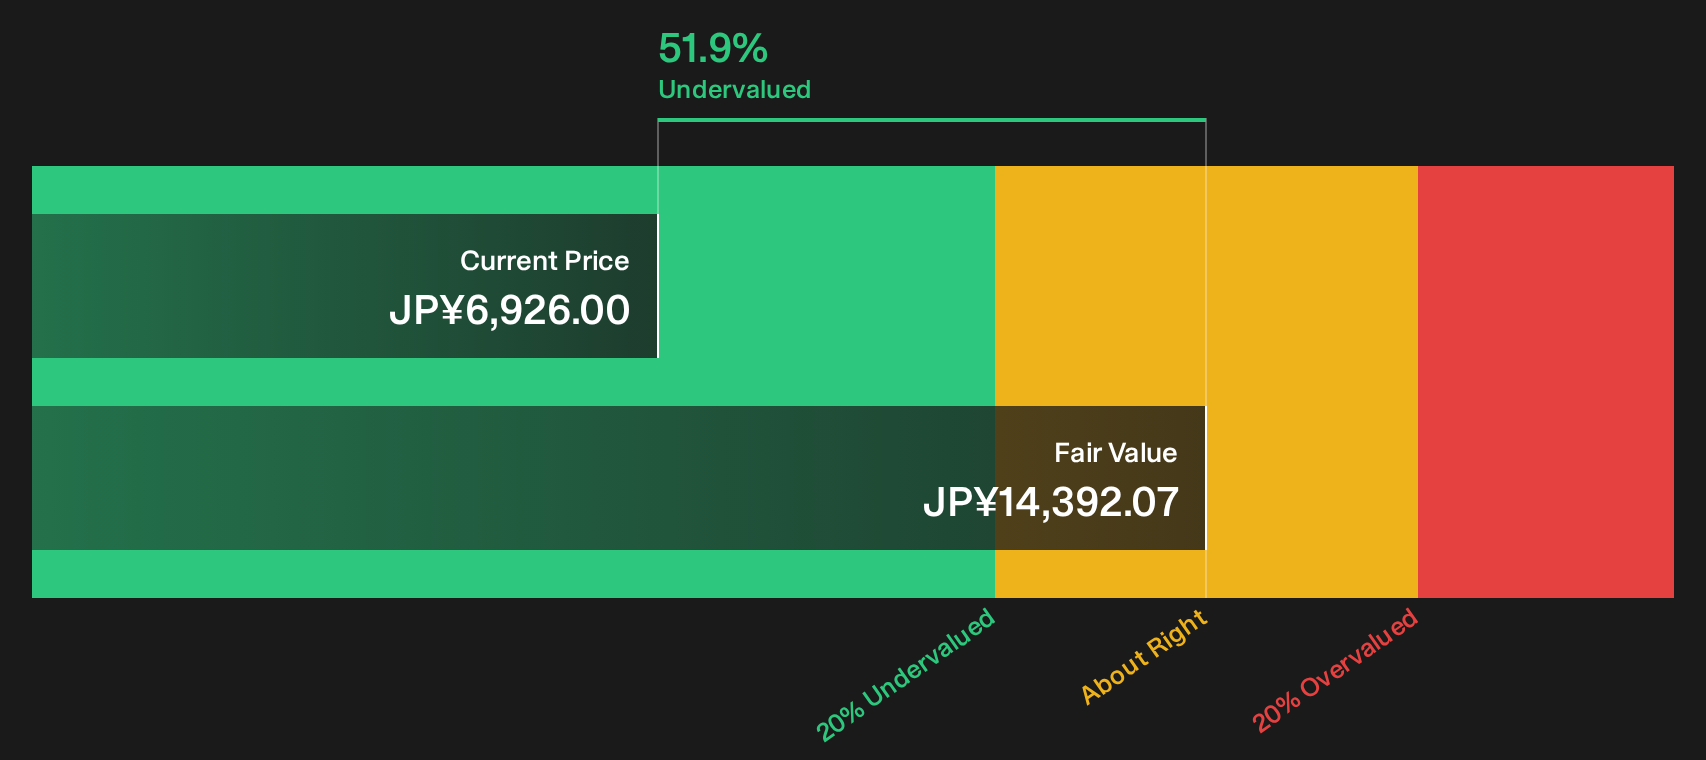
The analyst Narrative tags Takeda Pharmaceutical as 2% overvalued against a fair value of ¥6,759.56, yet our DCF model points to something different. On that framework, the shares trade at a 51.9% discount to an estimated future cash flow value of ¥14,392.07. Which story do you trust more: the target based on earnings forecasts, or the one grounded in long term cash generation?
To understand how sensitive that cash flow outcome is to growth and margin assumptions, and how it compares with your own expectations, Look into how the SWS DCF model arrives at its fair value.
Next Steps
If the split views around Takeda Pharmaceutical leave you on the fence, use that uncertainty as a prompt to move fast and test the data yourself. Start by weighing the company’s biggest potential upsides against the issues investors are worried about using our breakdown of 3 key rewards and 3 important warning signs
Looking for more Takeda Pharmaceutical style investment ideas?
Do not stop your research with Takeda Pharmaceutical. Fresh opportunities can appear quietly, and the investors who already mapped out alternatives are the ones ready to act with confidence.
- Target resilient compounding potential by reviewing companies with strong cash generation and attractive pricing through the 19 high quality undervalued stocks.
- Lock in income-focused ideas by scanning for reliable payout candidates featured as 28 dividend fortresses.
- Prioritize capital protection by filtering for companies screened as 20 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com