
Hudbay Minerals (TSX:HBM) Reports Record Revenue, Is The 33% Undervaluation Still Compelling?
Hudbay Minerals (TSX:HBM) has moved back into focus after reporting third quarter 2026 results, with sales of US$765.9 million and net income of US$149.5 million, alongside a reaffirmed quarterly dividend.
Hudbay Minerals has seen mixed momentum, with the share price down 11.7% over the past month and 17.6% over the past quarter, yet still up 10.4% year to date. This performance is supported by a 1 year total shareholder return of 37.9% and a very large 3 year total shareholder return above 4x, as investors weigh record Q3 revenue, Copper World progress and the reaffirmed dividend against recent earnings estimate misses and softer near term sentiment.
Scan Hudbay Minerals in context by lining it up against 17 top copper producer stocks that could benefit if investor interest swings back toward critical metals exposure.
Hudbay Minerals now trades well below its recent highs, even as it reports record quarterly revenue and advances Copper World. Does that reset leave more upside than downside for new money, or has most of the payoff already shown up?
Most Popular Narrative: 33% Undervalued
Hudbay Minerals last closed at CA$30.47, while the analyst consensus Narrative on Simply Wall St anchors fair value at CA$45.35, implying a sizeable valuation gap that hinges on copper growth projects and cash generation holding together over time.
The combination of record trailing twelve month adjusted EBITDA of about US$1.3b, more than US$400 million of free cash flow, and a net cash position of roughly US$80 million gives Hudbay Minerals scope to fund its growth pipeline and maintain its capital allocation framework. This can influence future net margins and earnings through disciplined investment and potential returns of capital.
See why 40 investors see Hudbay Minerals as 33% undervalued.
Result: Fair Value of CA$45.35 (UNDERVALUED)
Still, the Hudbay Minerals story can change quickly if fuel and consumable costs stay elevated or if Copper World capital needs climb beyond current expectations.
Find out about the key risks to this Hudbay Minerals narrative.
Another View: Hudbay Minerals Through The P/E Lens
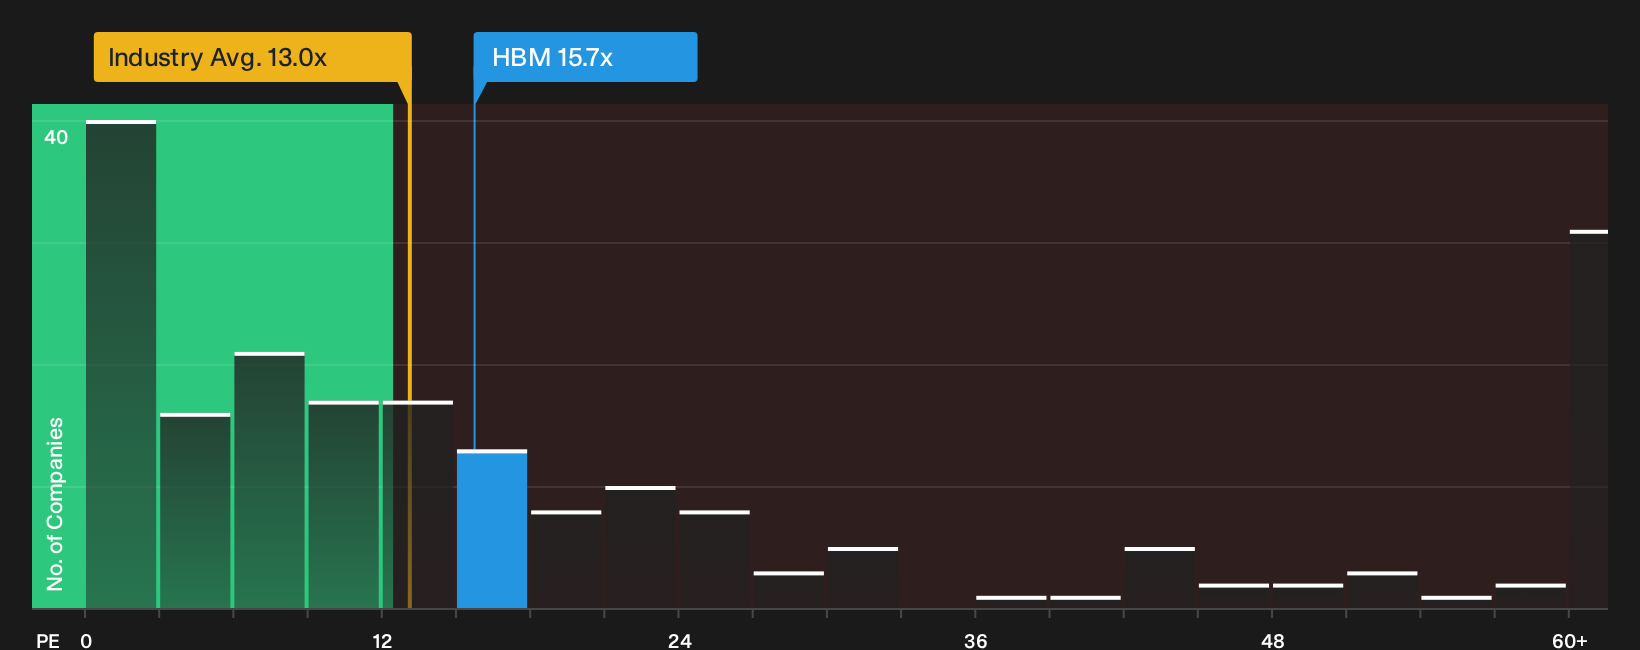
There is a different reading of Hudbay Minerals when the focus shifts from fair value estimates to plain P/E math. The shares trade on 15.7x earnings, above the Canadian Metals and Mining industry at 13x, yet below the peer group near 34.4x and close to a fair ratio of 15.9x.
This mix suggests investors pay a premium to the wider sector but a discount to closer comparables, while sitting near the level the market could move toward over time. The open question is whether that balance points to more upside risk or downside risk from here.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Hudbay Minerals is split, so treat this as your prompt to move quickly, stress test the numbers yourself, and weigh the upside shown in 3 key rewards.
Looking for more investment ideas beyond Hudbay Minerals?
If Hudbay Minerals has your attention, do not stop here. Fresh ideas often sit just outside your current watchlist, and ignoring them can quietly cost you.
- Target potential mispricing by using our filter built to surface quality opportunities that screens as 7 high quality undervalued stocks with stronger fundamentals already in place.
- Prioritise resilience under pressure by scanning a 9 resilient stocks with low risk scores so you focus on businesses with sturdier financial profiles and lower overall risk scores.
- Spot tomorrow's potential leaders early by checking a 9 high quality undiscovered gems that highlights companies the broader market may not be paying attention to yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com