
Hotel Demand Rebound Could Be A Game Changer For CoStar Group Stock (CSGP)
- CoStar Group reported that U.S. hotel performance in September showed an 11% year over year rise in RevPAR, the strongest monthly gain since February 2023, supported by leisure travel, calendar holiday timing and higher corporate group demand.
- The sharp pickup in corporate group demand within CoStar Group’s data points to healthier business travel activity, which matters for hotel owners, lenders and brokers who rely on the company’s analytics to plan capital allocation and pricing decisions.
- We will now examine how this stronger U.S. hotel RevPAR backdrop fits into CoStar Group’s broader investment narrative and execution.
Scan CoStar Group’s hotel demand data in context by comparing it with other travel-exposed plays identified through 20 high quality undiscovered gems that may still be flying under most investors’ radar.
CoStar Group Investment Narrative Recap
To own CoStar Group, you need to believe it can turn a deep real estate data and marketplace footprint into a broad, profitable platform while managing through slower revenue guidance and muted bookings. The analyst consensus narrative on Simply Wall St leans on tighter cost control and a focus on adjusted EBITDA as the near term anchor for that story.
The September RevPAR jump supports the relevance of CoStar’s hospitality data, although it does not materially change the central catalyst, which is execution across Homes.com, Apartments.com, AI tools and international portals. The main near term risk still sits with softer multifamily advertising trends and Ten X restructuring weighing on revenue if demand does not re accelerate.
One of the most important recent developments for this CoStar Group thesis is the reaffirmed 2026 adjusted EBITDA outlook of US$780 million to US$820 million, even after lowering revenue guidance. That commitment leans on expense cuts, including Homes.com sales headcount reductions and Ten X restructuring, and keeps margin quality in focus while the top line resets.
Set against the stronger hotel RevPAR data, that margin target shows how management is trying to balance cyclical pockets of strength, such as hospitality analytics, with areas under pressure like multifamily advertising. For you, the key question is whether cost discipline, AI and data products, Homes.com traction and the Zonda and international build out can offset those revenue risks over the next few years.
CoStar Group’s long term story hinges on analysts’ expectation that revenues reach US$4.7b and earnings climb to US$678.0m by 2029. This rests on an assumed 8.4% yearly rise in revenue and an earnings increase of about US$499.0m from US$179.0m today.
Uncover why CoStar Group's fair value indicates a 16% potential upside to its current price, which could narrow quickly.
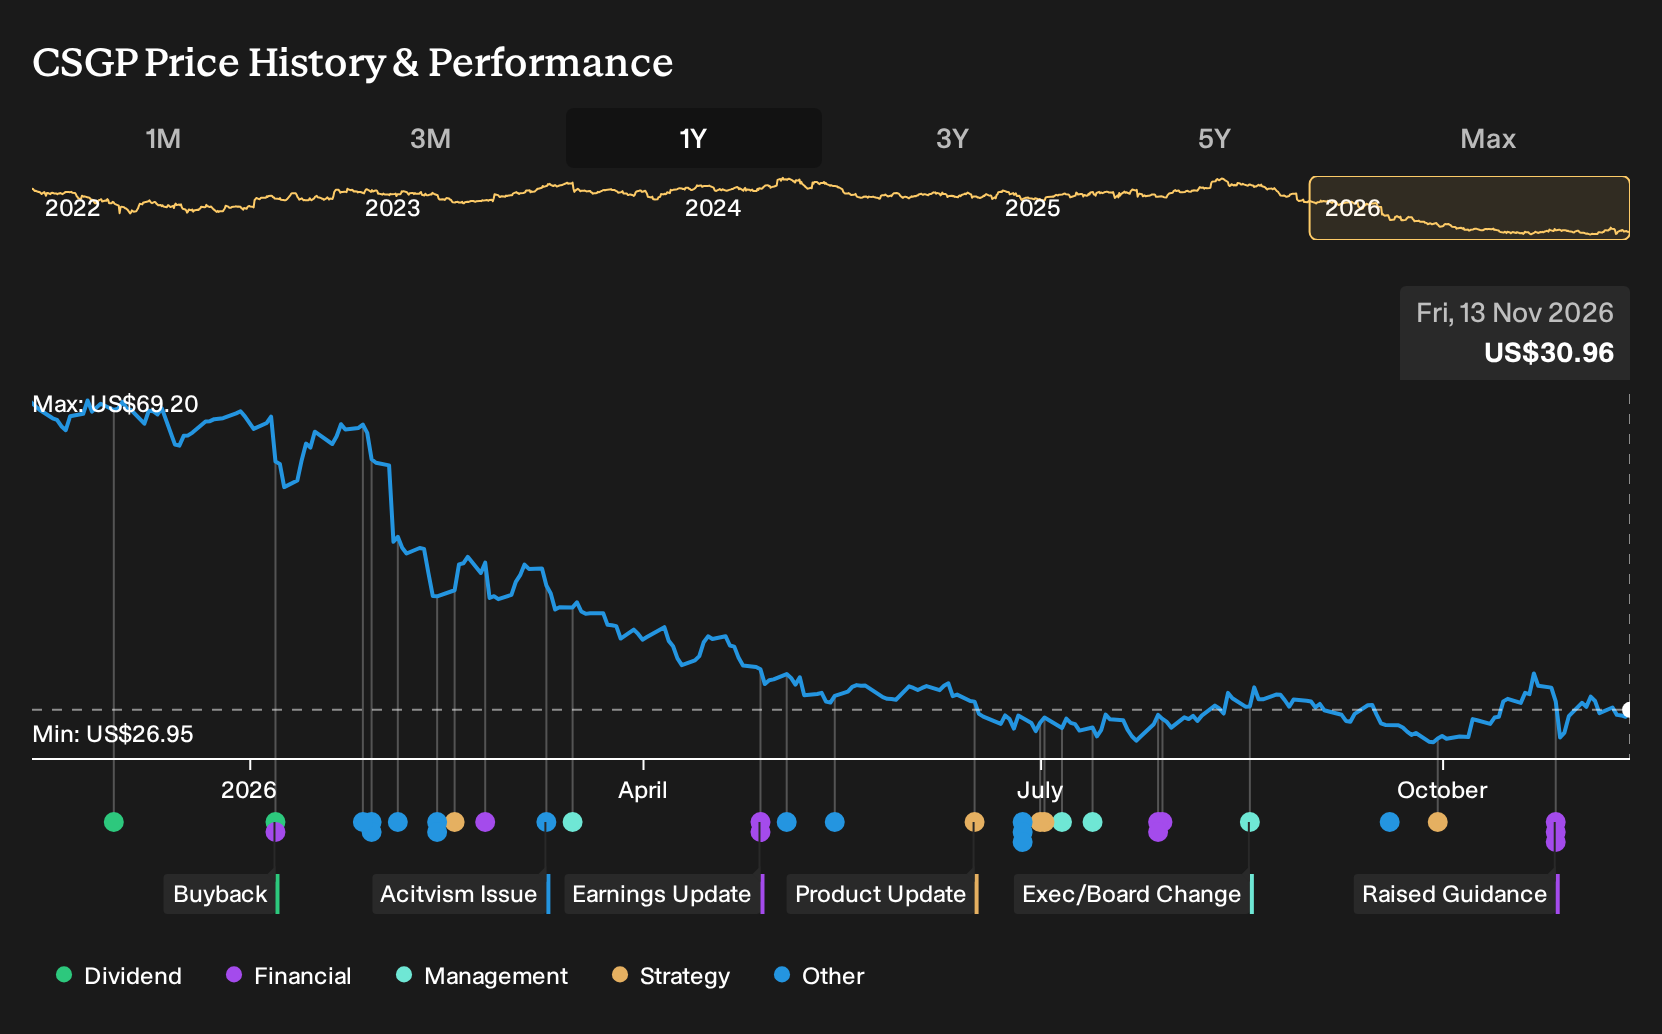
Exploring Other Perspectives
High conviction analysts are leaning into CoStar Group’s Homes.com catalyst. They were already pencilling in about US$5.3b of revenue and US$878.8m of earnings by 2029 before this RevPAR surprise. You can read that as a much more optimistic story, and it might shift again as stronger hotel data feeds into future forecasts.
Explore 4 other CoStar Group fair value estimates, including one that suggests as much as 147% potential increase from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CoStar Group research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for CoStar Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CoStar Group's overall financial health at a glance.
Looking for more investment ideas beyond CoStar Group?
Once you have a handle on CoStar Group, it can help to widen your watchlist with companies that fit specific risk, income, or quality filters using the Simply Wall St Screener.
- If you want steadier capital swings, start with stocks screened for resilience by checking out 31 resilient stocks with low risk scores.
- For readers focused on balance sheet strength and fundamentals, consider scanning the list of solid balance sheet and fundamentals (24 results) as a quality first shortlist.
- Income focused investors who care about cash returns can review the 6 dividend fortresses to see which payers clear a 5% yield hurdle.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com