
Will Earnings Beat Change UMS Integration's (SGX:558) Narrative
- UMS Integration reported third quarter 2026 sales of S$95.37 million and net income of S$21.08 million, with both basic and diluted earnings per share at S$0.0237. For the first nine months, sales reached S$251.9 million and net income was S$54.48 million.
- The step up in earnings per share from continuing operations over both the quarter and nine month period shows how UMS Integration converted higher activity levels into stronger profitability on a per share basis.
- The focus now turns to how UMS Integration's stronger earnings per share profile could reshape the investment narrative that readers have been tracking.
Scan how UMS Integration's latest earnings compare with other manufacturers by reviewing our hand picked 86 robotics and automation stocks in the same broader automation theme.
What Is UMS Integration's Investment Narrative?
To stay invested in UMS Integration, you need to believe that its precision engineering footprint across semiconductors and aerospace can keep attracting steady orders while management runs a tight operation. The latest quarter supports that story. Higher sales and net income fed through into a stronger earnings per share profile, which points to decent execution on volume, cost control and pricing. With analysts expecting both earnings and revenue to grow faster than the wider Singapore market, the near term narrative is still about converting demand into cash generation rather than chasing new, capital heavy projects.
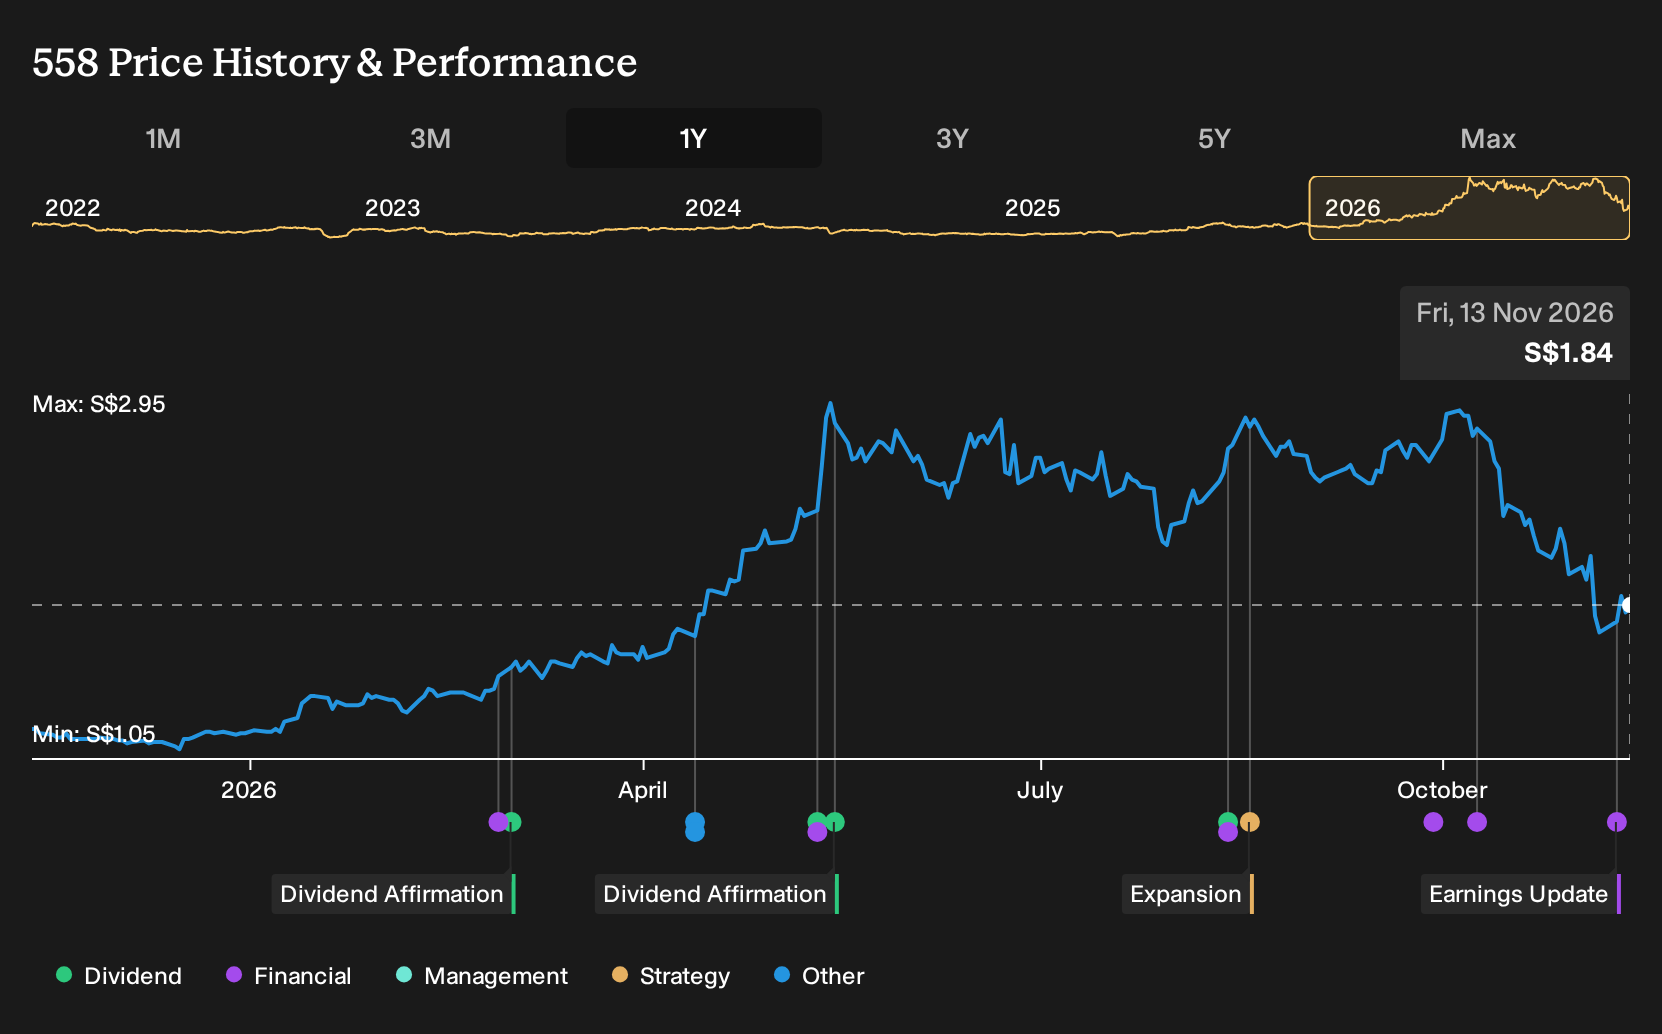
In the short term, the key swing factors look operational. Order visibility in semiconductor tools, the mix between higher margin components and lower margin services, and how much working capital is tied up as activity scales all matter more than any single quarterly print. The recent results fit into that picture as a supportive data point rather than a reset. The share price has climbed over the past week but is down over the last quarter, so the earnings beat has not fully rewritten sentiment on its own.
Yet there is one area where the headline growth story around UMS Integration has to share space with a quieter concern about...
There's only one way to know the right time to buy, sell or hold UMS Integration. Head to Simply Wall St's company report for the latest analysis of UMS Integration's Fair Value.
Exploring Other Perspectives
On fair value, the Simply Wall St Community offers two very different takes on UMS Integration, with estimates stretching from 0.34 to 2.91. That spread shows how widely private investors can disagree. Use it as a prompt to stress test your own view, especially now that fresh earnings data has arrived.
Explore another UMS Integration fair value estimate, including one that suggests as much as 58% upside from the current price.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your UMS Integration research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for UMS Integration. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UMS Integration's overall financial health at a glance.
Looking For More Investment Ideas Beyond UMS Integration?
If UMS Integration has sharpened your interest in precision manufacturers and resilient balance sheets, it can help to widen the lens and compare it with a broader set of listed businesses.
- For investors who want strong fundamentals with less drama, filter for companies screened as 210 resilient stocks with low risk scores that could offer a steadier ride through different market conditions.
- If your priority is financial resilience, focus on businesses with cleaner debt profiles and robust cash positions through our list of solid balance sheet and fundamentals (198 results) to see which ones meet your risk tolerance.
- Those hunting for underappreciated opportunities can scan a curated 559 high quality undiscovered gems that pair quality metrics with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com