
Raised Revenue Outlook Might Change The Case For Investing In LivaNova Stock (LIVN)
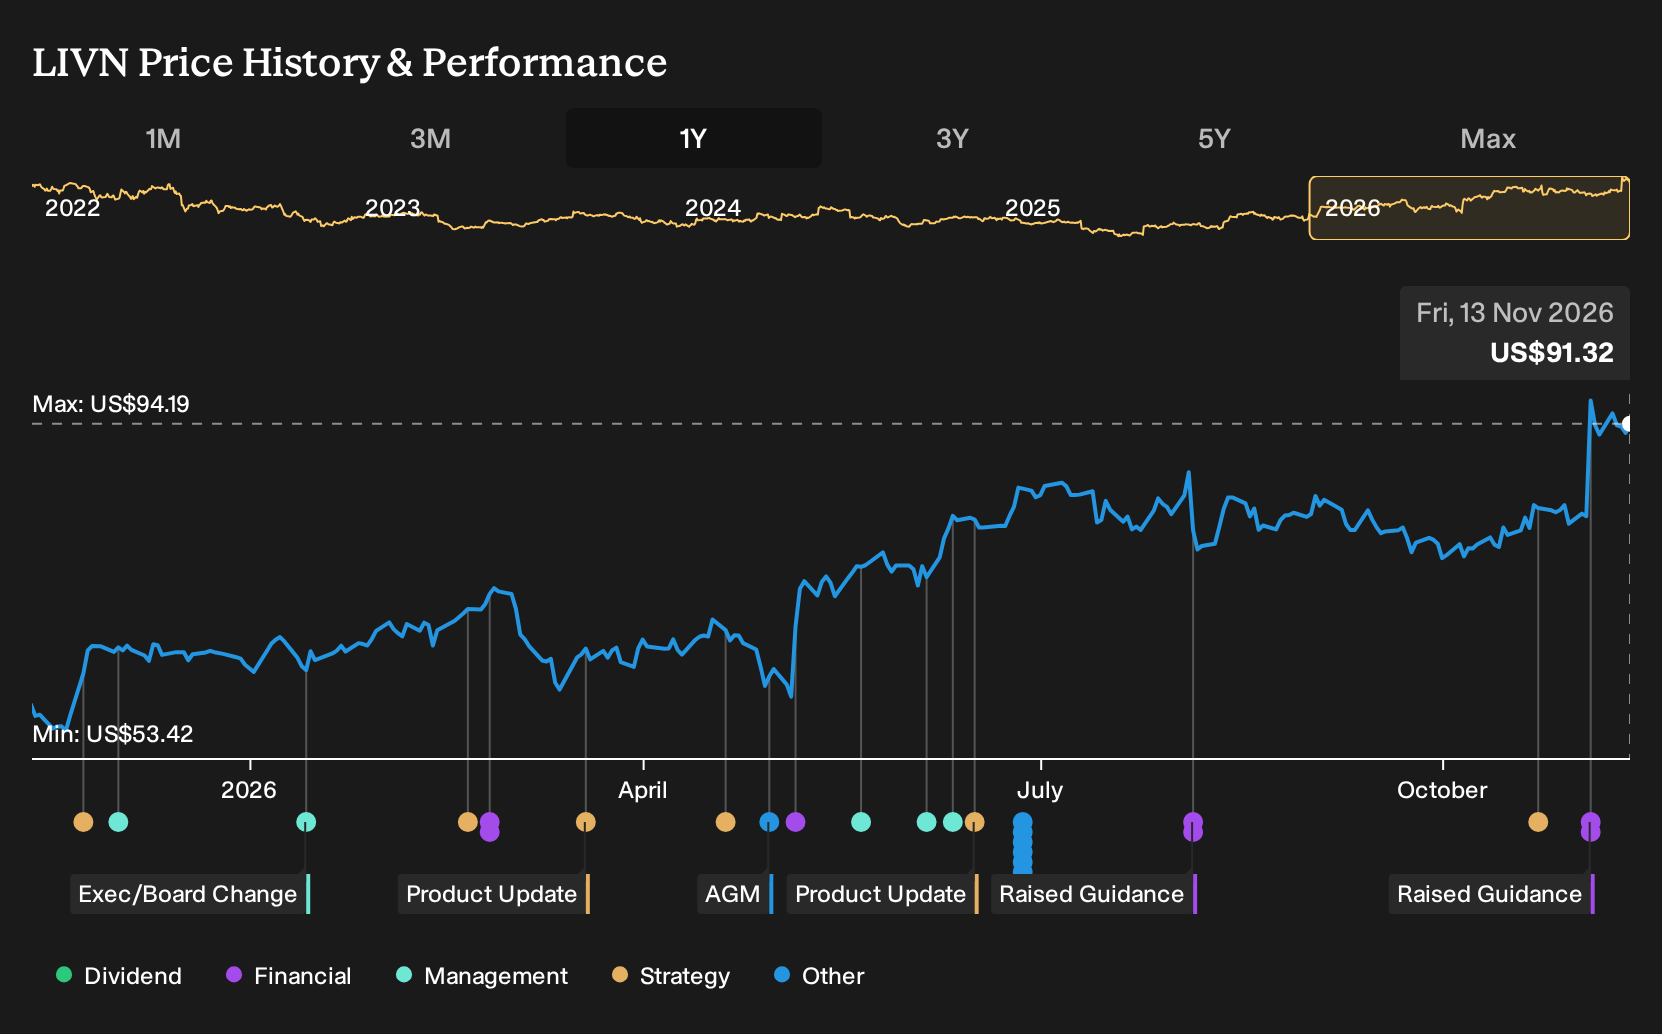
- LivaNova reported third quarter 2026 sales of US$393.15 million and net income of US$34.29 million, alongside higher full year 2026 constant currency revenue growth guidance of 9% to 10% and an expected 1% foreign exchange tailwind.
- The nine month shift from a net loss of US$273.38 million to net income of US$165.16 million, with basic earnings per share from continuing operations moving from a loss of US$5.01 to US$3.01, points to a materially different earnings profile for LivaNova’s ongoing operations.
- We will now see how LivaNova’s raised 2026 revenue outlook could reshape its existing investment narrative around growth and cash generation.
LivaNova Investment Narrative Recap
LivaNova appeals most if you believe its heavy investment in cardiopulmonary, neuromodulation and digital platforms can translate into steadier earnings and stronger cash generation. The analyst consensus Narrative on Simply Wall St centers on that execution. The higher 2026 revenue growth guidance to 9% to 10% suggests management sees current demand as supportive. In the short term, the key issue remains how well new capacity and IT spending convert into operating leverage.
The biggest near term risk stays the same. LivaNova is in a high CapEx phase, with US$135,000,000 planned for 2026, so any delay in monetising cardiopulmonary upgrades or neuromodulation launches could weigh on free cash flow. Dependence on government reimbursement in epilepsy, plus logistics and tariff costs, still add operational uncertainty despite the raised outlook.
The raised full year 2026 revenue guidance is the announcement that matters most here. Management now expects 9% to 10% constant currency growth, with a 1% foreign exchange tailwind based on current rates. For investors watching catalysts, this updated outlook directly connects to whether recent Essenz placements, oxygenator capacity and neuromodulation momentum are feeding through to the income statement as intended.
That guidance interacts cleanly with existing triggers and risks. A higher top line target increases the spotlight on execution in cardiopulmonary and on epilepsy volumes supported by improved Medicare reimbursement. It also heightens the stakes on elevated spending. If cardiopulmonary and neuromodulation do not sustain that guided growth, the combination of heavy CapEx, reimbursement exposure and tariffs could pressure margins and delay the cash conversion goals highlighted in the analyst consensus Narrative on Simply Wall St.
LivaNova's current analyst narrative points to forecast revenues of US$1.9b and earnings of US$244.6 million by 2029, based on an assumed 7.3% yearly increase in revenue and an earnings rise of about US$48.5 million from US$196.1 million today.
Uncover why LivaNova's fair value indicates a 15% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One bullish twist in the alternate LivaNova story is the focus on earnings power. The most optimistic analysts were already projecting revenue of about US$2.0b and earnings of roughly US$257.7 million by 2029, before this guidance upgrade. That group paints a much richer EPS path than consensus, so today’s news could eventually nudge those expectations even higher or prompt a rethink if execution falls short. Investor views can spread widely, so it helps to compare several narratives before you decide how this raised outlook fits your own thesis.
Explore another LivaNova fair value estimate, including one that suggests as much as 15% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your LivaNova research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for LivaNova. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate LivaNova's overall financial health at a glance.
Looking for more investment ideas beyond LivaNova?
Once you have a view on LivaNova, it can help to cross check that thesis against a broader watchlist of businesses with different risk, income and valuation profiles. The Simply Wall St Screener offers several focused sets of companies that can round out your research and keep you from getting anchored on a single story.
- If you want a shortlist of companies where stability and balance sheet strength are front and center, start with a list of solid balance sheet and fundamentals (24 results) that can handle shocks without leaning heavily on new funding.
- For readers who care most about valuation and quality together, compare LivaNova against a 32 high quality undervalued stocks that pair healthier cash profiles with share prices that sit below estimated fair value ranges.
- If capital preservation sits high on your priority list, cross reference your ideas against a 31 resilient stocks with low risk scores that screens for businesses with more resilient risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com