
Louisiana-Pacific (LPX) Beat On Earnings, Is The Stock Still Cheap?
Louisiana-Pacific (LPX) drew fresh attention after reporting third quarter results that featured higher net income and earnings per share year over year, followed by a reaffirmed quarterly dividend of $0.30 per share.
The recent earnings beat and dividend affirmation arrived alongside a 30 day share price return of 14.04%, which has helped offset a year to date share price decline of 7.19%. Momentum looks more muted over a longer horizon, with a 1 year total shareholder return of 1.79% compared with a 3 year total shareholder return of 28.94% and 5 year total shareholder return of 15.70%. This suggests that recent enthusiasm around Louisiana-Pacific is building from a relatively modest near term base.
Scan beyond Louisiana-Pacific and review a curated group of construction and materials stocks showing strong financial quality and potential mispricing with our 32 high quality undervalued stocks.
Louisiana-Pacific has already rewarded investors who stepped in before the recent 30 day jump, yet the share price is still below earlier 2026 levels. The key question is whether the current valuation signals remaining upside or suggests that most of the move has already played out.
Most Popular Narrative: 14% Undervalued
On the analyst consensus Narrative on Simply Wall St, Louisiana-Pacific carries a fair value estimate of $87.79 against a last close of $75.85. This points to a valuation gap that the narrative links to siding growth potential and OSB headwinds. The same work applies a 9.08% discount rate to those future cash flows and earnings assumptions, then weighs them against a housing exposed business that still depends on both product mix and cost control.
Continued product innovation, including new SmartSide profiles and treated products such as LP BurnGuard fire rated OSB, together with capacity additions for ExpertFinish at Green Bay, Bath and the planned North Branch plant, broadens the addressable market and can support further market share gains that flow through to higher revenue and earnings.
See why 13 investors see Louisiana-Pacific as 14% undervalued.
Result: Fair Value of $87.79 (UNDERVALUED)
Still, the Louisiana-Pacific narrative depends on housing-related demand holding up and on OSB pricing not remaining weak enough to keep that segment below EBITDA breakeven.
Find out about the key risks to this Louisiana-Pacific narrative.
Another View: What Multiples Say About Louisiana-Pacific
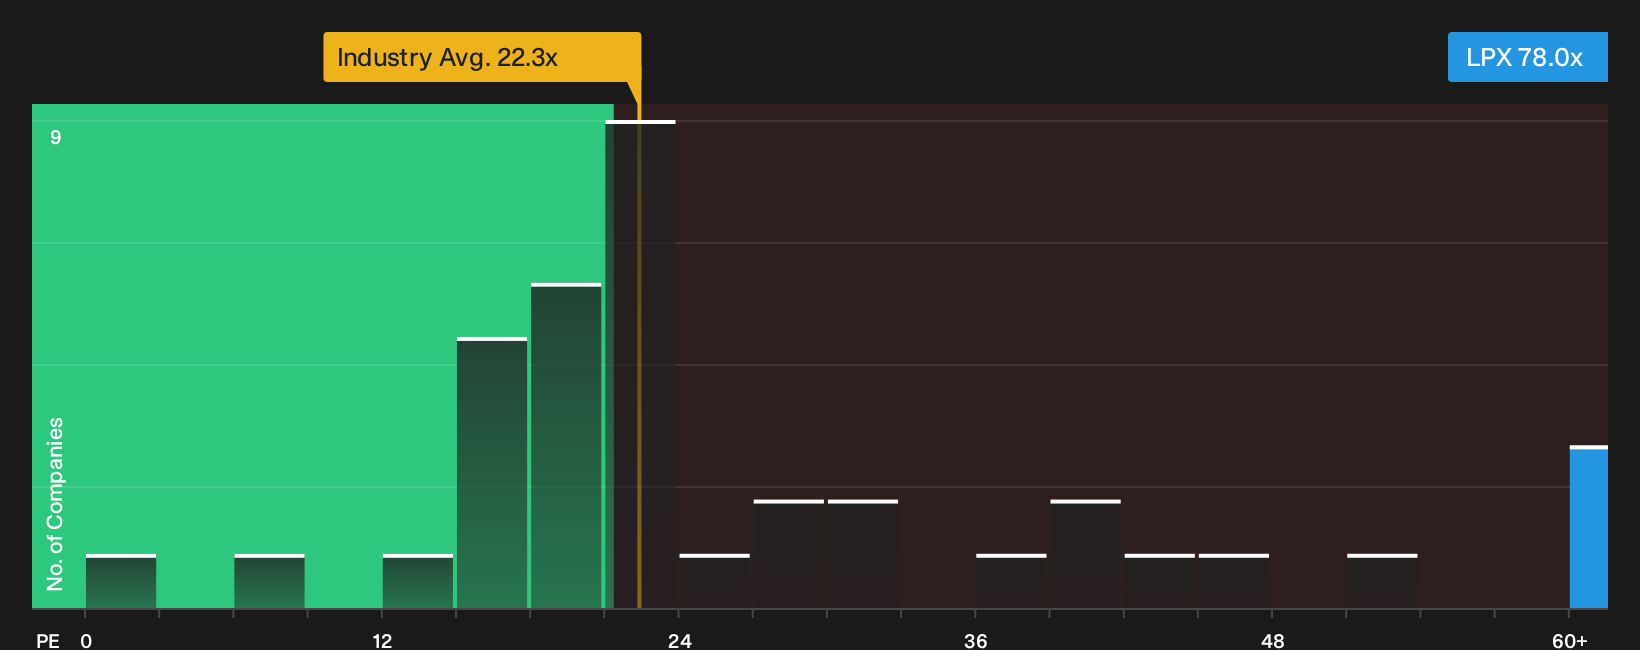
Set the DCF narrative aside for a moment and look at what the P/E ratio is saying. Louisiana-Pacific trades on about 78x earnings versus 22.2x for the wider US Building industry and 28.8x for close peers, while the fair ratio sits lower again at 73.4x.
That gap suggests investors are already paying a premium for the LPX story, which leaves less room for error if margins or housing demand disappoint. The question is whether you think the business can grow into that higher multiple before the market pushes the ratio closer to the fair level.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the data can create hesitation, yet the real edge comes from reviewing the full picture yourself and acting on your own judgment, starting with a closer look at the 1 key reward and 3 important warning signs.
Looking for more ideas beyond Louisiana-Pacific?
If Louisiana-Pacific has sharpened your focus, do not stop here. Fresh opportunities often emerge where pricing, balance sheets and income streams tell a cleaner story.
- Target resilient income potential by scanning companies that show up in our 6 dividend fortresses.
- Spot mispriced quality by reviewing the hand picked candidates in our 20 high quality undiscovered gems.
- Prioritise durability and capital protection by filtering for businesses inside our 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com