
Kerry Group (ISE:KRZ) Retail Expansion Puts Its Undervalued Narrative Back In Focus
Bio-K+, part of Kerry Group (ISE:KRZ), has rolled out its probiotic Pro Line and other products across major retailers including Walmart, Costco.ca and Albertsons, widening retail and e-commerce access across Canada and the United States.
The recent push by Bio-K+ into Walmart, Costco.ca and Albertsons arrives while Kerry Group’s shares trade around €101.7, with a 30-day share price return of 11.39% and a 33.38% year to date gain. This suggests building positive momentum, alongside a 31.79% 1-year total shareholder return and a mixed longer record that includes a 46.67% total shareholder return over three years, but a 5-year total shareholder return that is still slightly down.
Scan other health focused consumer stocks that are showing similar momentum in probiotics and packaged nutrition with our curated list of 559 high quality undiscovered gems.
After a sharp run in Kerry Group shares alongside Bio K+ gaining shelf space at mass retailers, you now face a simple timing call. Is it worth stepping in at today’s price or waiting for a cooler entry before valuation stacks up for you?
Most Popular Narrative: 90% Undervalued
On the analyst consensus Narrative on Simply Wall St, Kerry Group’s fair value sits at about €102.58 against a last close of €101.70. Simply Wall St’s own cash flow model points to a far higher intrinsic value, framing a wide gap between price and what those models imply.
The current valuation implies the market is only partially pricing in Kerry’s targets for 3 to 5% volume growth, 20 to 21% EBITDA margins and higher cash conversion by 2030, which supports the narrative that the stock is undervalued.
See why 11 investors see Kerry Group as 1% undervalued.
Result: Fair Value of €102.58 (UNDERVALUED)
Still, Kerry Group’s narrative can be knocked off course if end markets stay weak and if currency swings or rising input costs squeeze the margin story analysts are using.
Find out about the key risks to this Kerry Group narrative.
Another View: Kerry Group On Earnings Multiples
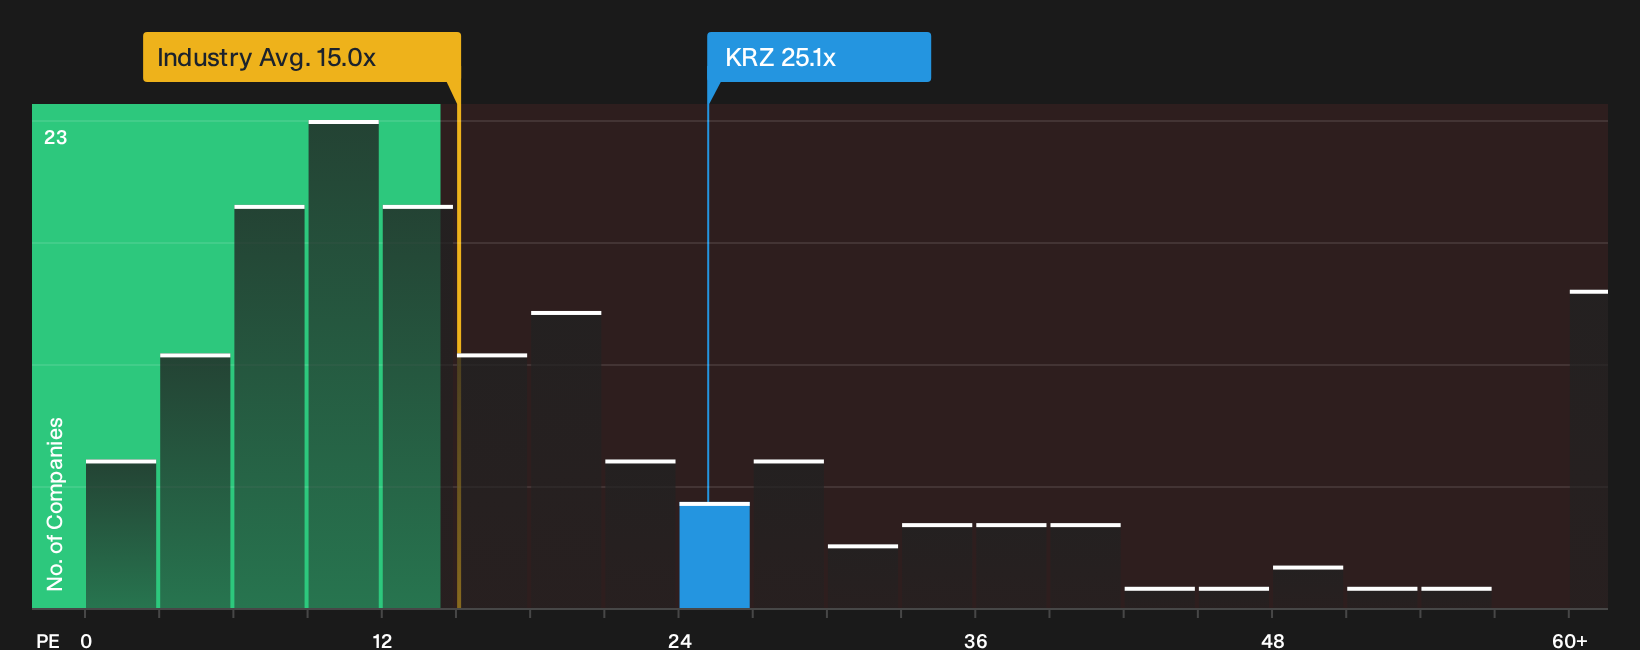
Kerry Group looks cheap on cash flow models, yet its P/E of 25.1x tells a different story. That figure is higher than the European Food sector at 14.5x and above a fair ratio of 20.8x, even though it is slightly below peer levels at 26.1x.
This gap suggests the market already pays a premium for Kerry Group’s earnings compared with the wider industry, while still leaving some room for compression if sentiment cools toward the fair ratio. How comfortable are you owning a stock where the story is value on cash flows, but a premium on earnings?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Kerry Group is clearly split between value appeal and premium earnings. If that tension pushes you to act rather than watch, walk through the underlying positives that have investors optimistic by checking the 2 key rewards.
Looking for more ideas beyond Kerry Group?
If Kerry Group has sharpened your focus on pricing, quality and timing, do not stop here. Broaden your watchlist so you are not relying on a single story.
- Hunt for stronger value setups by scanning our curated pool of quality opportunities with the 198 high quality undervalued stocks.
- Sharpen your income playbook and target potential cash return candidates using the focused universe of 220 dividend fortresses.
- Dial down portfolio stress by concentrating on sturdier businesses screened through the 210 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com