
Kuraray (TSE:3405) Reported Stronger Nine Month Earnings, Is The Premium Valuation Justified?
Kuraray (TSE:3405) has drawn fresh attention after reporting nine month sales of ¥643,351 million and net income of ¥40,624 million, along with a board meeting on a planned merger of wholly owned Kuraray Saijo.
The recent nine month earnings release and the planned merger review have arrived after a solid run in Kuraray's shares, with a year to date share price return of 19.76% and a 1 year total shareholder return of 24.75% that points to building momentum rather than fading interest.
Scan Kuraray's latest move in context by comparing it with our hand-picked 72 high quality undiscovered gems that are also drawing fresh interest from improving earnings profiles.
Bulls see Kuraray's stronger nine month figures and merger plan as evidence the recent share price climb still has room. Bears point to an already solid run. Which side do the current valuation signals lean toward next?
Preferred Multiple of 22.8x P/E: Is it justified?
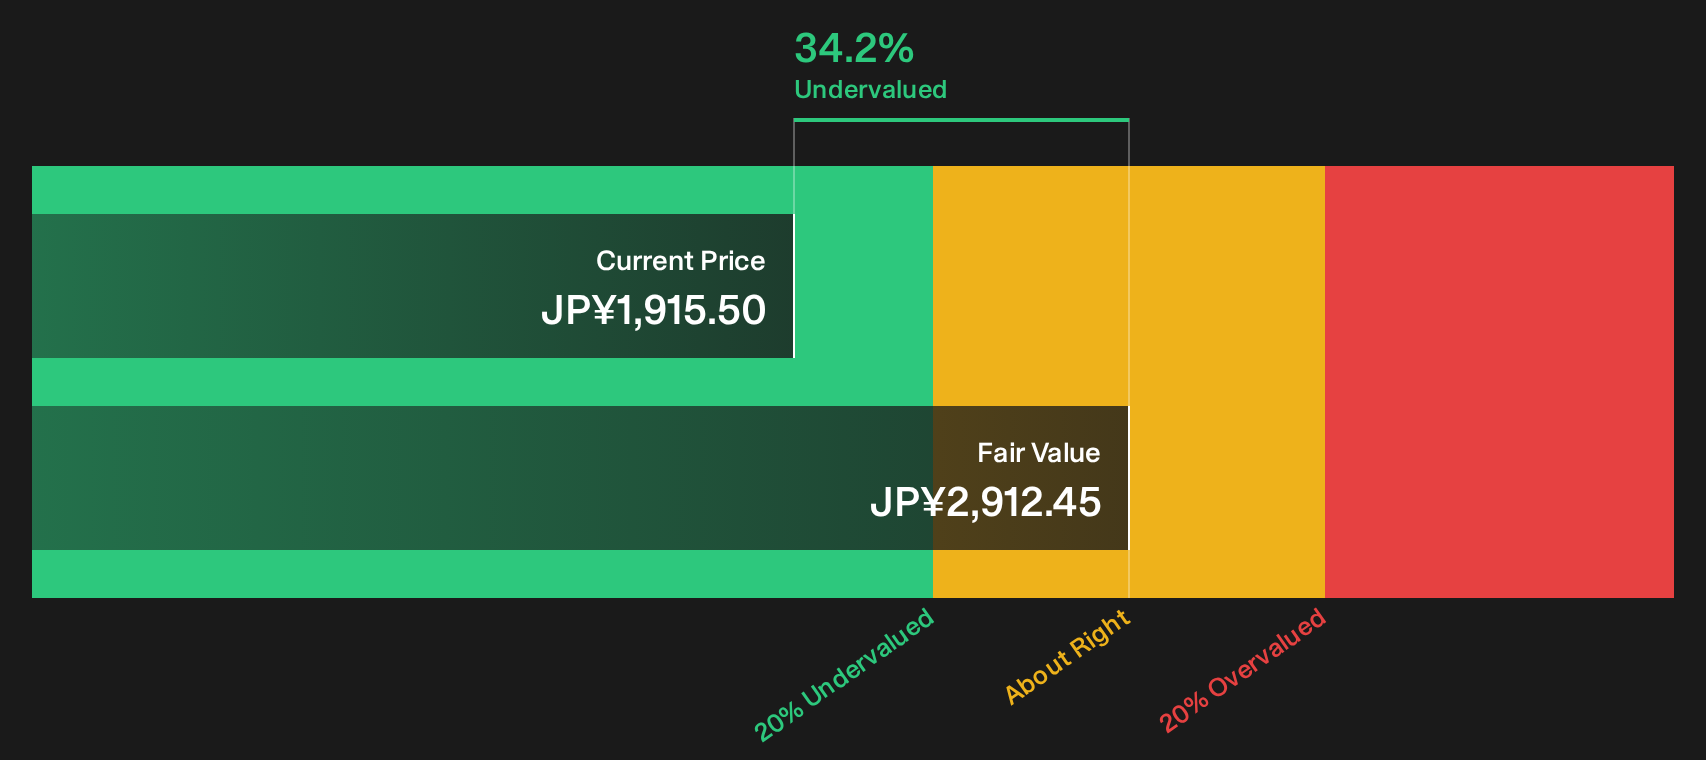
Kuraray trades on a P/E of 22.8x, which sits against a last close of ¥1,915.5 and a discounted cash flow estimate of ¥2,912.45 from the SWS DCF model.
The P/E multiple captures how much investors are willing to pay today for each unit of current earnings. For a materials group like Kuraray, which operates across vinyl acetate, isoprene, functional materials, fibers, and trading, that ratio often reflects how durable investors think those earnings are and how much growth they expect to see from here.
Right now the market is paying a P/E of 22.8x for Kuraray. The estimated fair P/E from Simply Wall St's model is 16.9x, which is meaningfully lower. The current multiple is also more than double the peer average of 10.7x and ahead of the broader JP Chemicals industry on 11.6x. Those gaps suggest investors are pricing in stronger earnings quality and growth than both the fair ratio implies and the sector currently commands.
Explore the SWS fair ratio for Kuraray.
Result: Price-to-Earnings of 22.8x (OVERVALUED)
Still, Kuraray's premium P/E and the discount to its ¥1,812.14 analyst price target leave little room if earnings momentum or merger benefits disappoint.
Find out about the key risks to this Kuraray narrative.
Another View on Kuraray's Value
The P/E picture looks rich for Kuraray, yet the SWS DCF model tells a different story. On that cash flow view, the shares trade about 34.2% below an estimated value of ¥2,912.45. One lens suggests the stock is expensive, while the other suggests a discount. Which one do you consider more when money is on the line?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kuraray for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 19 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Kuraray's value can be confusing. Move quickly to check the underlying data, weigh the upside and downside, then judge the balance of its 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Kuraray?
Do not stop your research with Kuraray. The right set of alternatives can change your opportunity set, especially when valuations and risks are pulling in different directions.
- Spot potential bargains early by scanning a 19 high quality undervalued stocks that filters for companies with attractive pricing and solid fundamentals.
- Protect the downside first by checking a 20 resilient stocks with low risk scores focused on resilient balance sheets and steadier risk profiles.
- Get ahead of the crowd by reviewing a list of solid balance sheet and fundamentals (24 results) that highlights businesses with financial strength to support future decisions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com