
Is National HealthCare (NHC) Cheap On Mixed Earnings And Profit Pressure?
National HealthCare (NHC) just delivered third quarter results that showed higher revenue alongside a sharp drop in profit, while also affirming a quarterly dividend, a combination that gives investors mixed signals to unpack.
Recent trading reflects that mixed message. The share price is down 11.32% over the past month and 7% over 90 days, yet the year-to-date share price return of 59.44% and 1-year total shareholder return of 64.72% show that National HealthCare still sits on strong longer term gains.
Spot opportunities with a similar mix of growth and earnings pressure by scanning our curated list of 32 high quality undervalued stocks that may be pricing in near term profit headwinds.After an 11% pullback following softer profit, and with National HealthCare still up strongly over the past year, does it make more sense to step in now or wait for a cleaner entry as the valuation picture comes into focus?
DCF valuation: a wide gap between price and cash flow value
The SWS DCF model currently estimates a future cash flow value for National HealthCare of $488.12 per share, which is well above the recent closing price of $207.93. That gap suggests the market price reflects a heavy discount to the modelled stream of future cash flows.
A discounted cash flow approach projects the cash the business could generate over time, then discounts those amounts back to today using a required return. The idea is simple. Cash received in the future is worth less than cash in hand today, so each year out gets marked down before all those values are added up into a single fair value estimate.
For a healthcare operator like National HealthCare, with $1.58b in revenue and earnings of $114.66m, this type of model leans heavily on the durability of its inpatient, homecare and hospice earnings base. The result here is a valuation that presents the shares as trading at a 57.4% discount to the model’s estimate of future cash flow value, which is a much more generous appraisal than recent profit softness might indicate.
Look into how the SWS DCF model arrives at its fair value.
Result: DCF Fair value of $488.12 (UNDERVALUED)
Still, any thesis built on discounted cash flows needs watching for pressure on National HealthCare’s reimbursement rates or heavier staffing and care delivery costs that compress cash generation.
Find out about the key risks to this National HealthCare narrative.
Another view on National HealthCare’s valuation
The SWS DCF model paints National HealthCare as heavily undervalued relative to its projected cash generation, yet the market is still paying a rich 28.4x P/E compared with 25.3x for the wider US Healthcare sector and 24.4x for peers. That gap points to sentiment that already bakes in quality, which raises a simple question for you: Is the current price rewarding that confidence or stretching it too far?
See what the numbers say about this price — find out in our valuation breakdown.
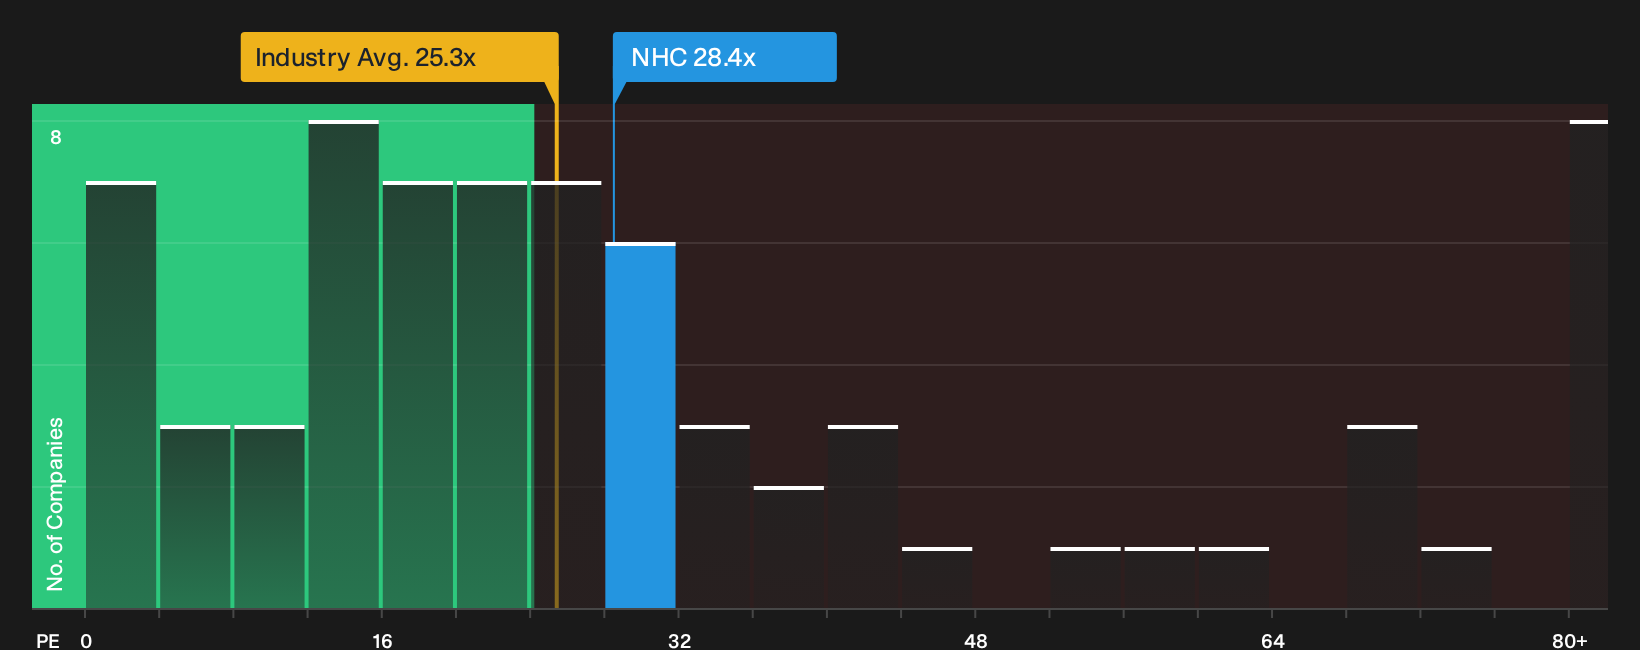
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out National HealthCare for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on National HealthCare’s value story are one thing; your own judgment is another. Move quickly through the data and decide whether the trade off between potential upside and known issues fits your risk tolerance with 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond National HealthCare?
If National HealthCare has sharpened your focus on valuation and risk, do not stop here. Put the same discipline to work across a wider watchlist.
- Target potential bargains early by filtering for companies that combine quality fundamentals with discounted prices using the 32 high quality undervalued stocks.
- Strengthen your income stream by reviewing a carefully curated set of higher yield payers through the 6 dividend fortresses.
- Dial back portfolio risk by zeroing in on businesses with sturdier financial footing using the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com