
What Andritz Holders Bought Into
If you only skimmed the headlines about order backlog records, hydropower projects and decarbonization tailwinds, the outcome for Andritz might still surprise you. For Andritz shareholders, the return over the past year was 36.5%, including dividends. That result landed in between bullish calls of industrial revival and bearish warnings about legacy hydropower and pulp. If you were weighing those opposing views back in November 2025, what exactly in the public record could have tipped your decision?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Andritz is not the only name tied to this theme. Zero in on 43 power grid technology and infrastructure stocks and compare how each one is priced.
What Andritz Investors Were Really Arguing About
The shares cost €64.55 at the start of the period, and Andritz sat between two sharply different stories about its future.
In the optimistic Narrative, Fair Value sat at €70.56. Supporters focused on a 26% jump in Q2 order intake, a €10.4b backlog and a rising 44% revenue share from services, which they viewed as a path to more recurring income.
The cautious view put Fair Value at €43. Bears pointed to legacy hydropower and pulp exposure, higher compliance costs and pressure from lower cost rivals as factors that could squeeze margins over time.
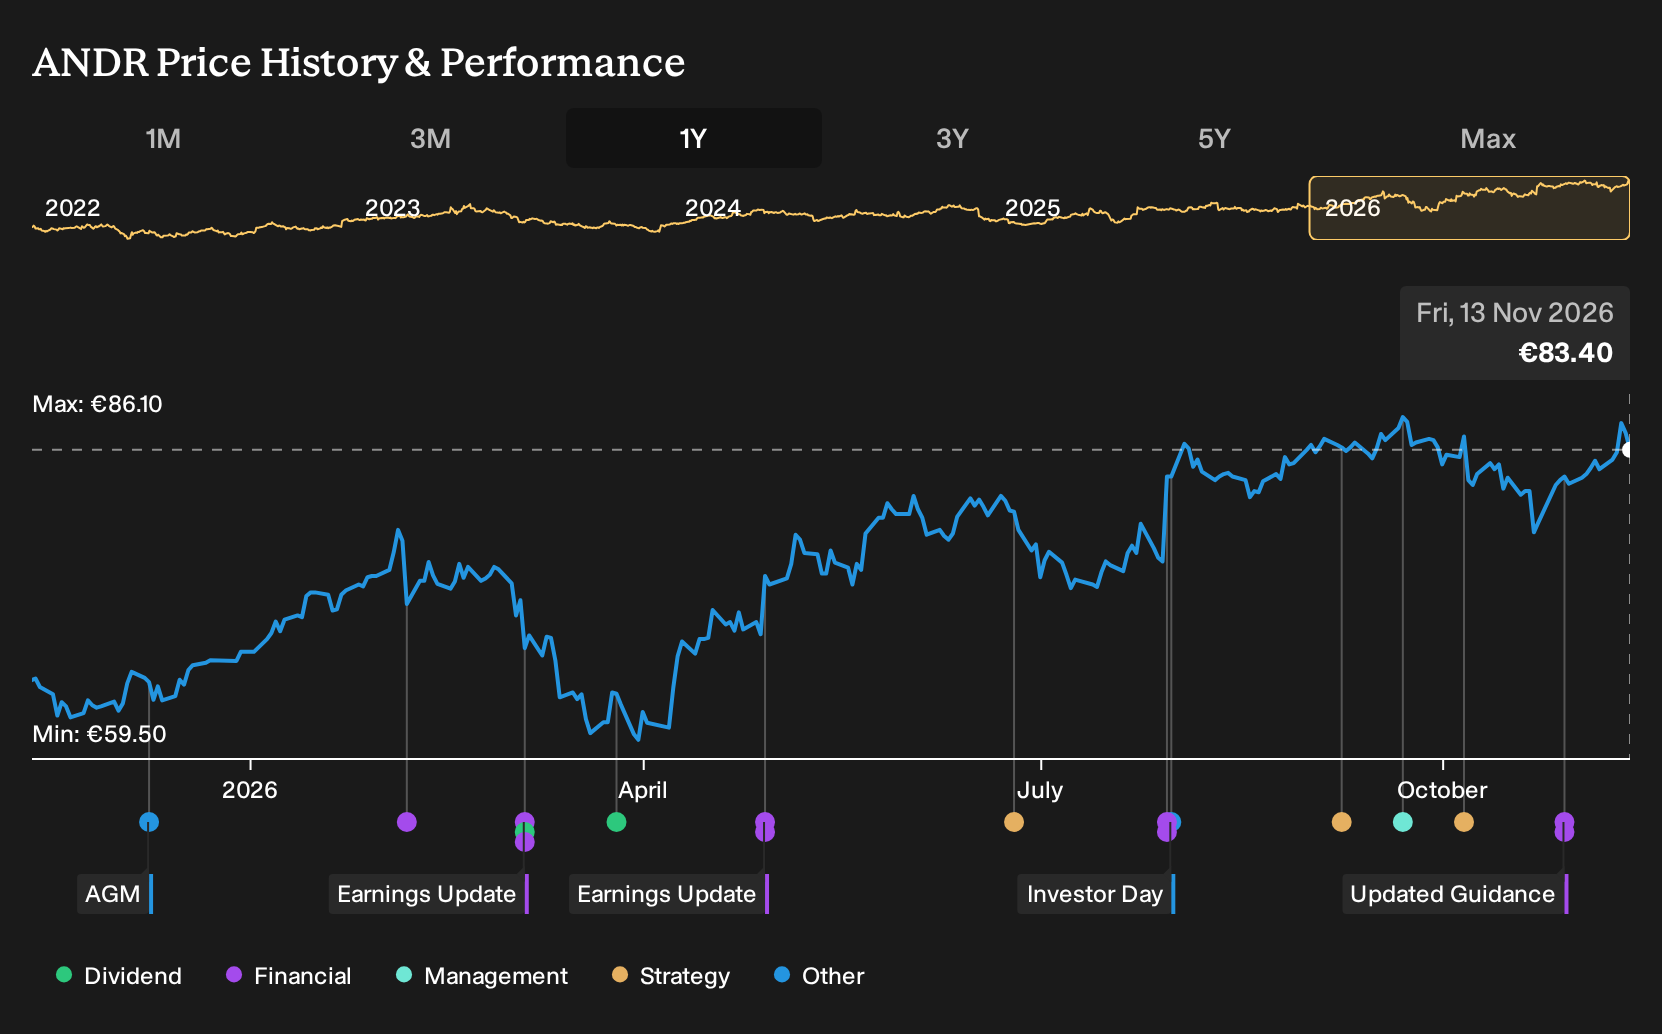
What The Results Changed For The Andritz Debate
The clearest update came from Q3 2026, when Andritz reported revenue of €2,059.6m and net income of €126.9m. Both revenue and profit rose versus Q3 2025, and net margin edged up from 5.9% to 6.2%. That pattern supported the optimistic case that higher services and a large backlog could feed gradually better profitability, although it did not resolve long term hydropower and pulp concerns.
The practical lesson is simple. When a story hinges on margin resilience, do not just watch sales or order headlines. Instead, track the reported net margin and the share of Andritz or any peer’s turnover that comes from services compared with more cyclical project work.
What Today’s Andritz Price Already Assumes
With Andritz now at €83.4, the bullish analyst Narrative on Simply Wall St places its Fair Value above that quote, based on confidence in hydropower orders, grid related equipment and a heavier tilt toward recurring service work and cash generation.
The Narrative argues today’s price still does not fully credit the durability of that backlog fed cash flow and the potential mix shift toward higher margin activities.
"The rising share of service revenue, at about 44% of group revenue in 2025 and 45% to 46% in early 2026 with Pulp & Paper already near 60%, creates room for Andritz to shift mix further toward recurring and higher margin activities, which can influence group net margins and cash conversion as that share grows."
One Narrative disagrees with today's price. → See where this Narrative says Andritz should trade
After Andritz, Another Kind Of Factory
Andritz shows how physical infrastructure stories often start with booked projects. You could also look at a business built around hardware that actually ships.
Instead of turbines or pulp lines, this one produces ammunition and small unmanned aircraft. The link is simple. Both are meant to be used up and reordered.
Customers do not restock arsenals or drone fleets with slide decks. They need reliable production lines turning raw material into finished, repeatable products.
As Andritz investors weigh backlog quality, this parallel raises a separate question. What happens when a manufacturer secures contracts that strain whether its existing plant can truly scale?
That argument has a Narrative and a number behind it. → See the company one Narrative values 183% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com