
Cardinal Health (CAH) Gains Fresh Support After Strong Earnings While Fair Value Stays In View
Why Cardinal Health Stock Is Back On Investor Radar
Analyst sentiment around Cardinal Health (CAH) has turned more optimistic after a run of stronger earnings and profit figures, which has put the stock on more watchlists for income and healthcare exposure.
Recent news has given investors fresh reasons to recheck the chart. Cardinal Health confirmed another quarterly dividend and posted first quarter earnings with higher sales and net income. The share price has climbed, with a 13.47% 1 month share price return and a very large 5 year total shareholder return that points to strong long term momentum.
Scan how Cardinal Health stacks up against other healthcare distributors by reviewing our hand picked list of solid balance sheet and fundamentals (24 results) that could complement or compete with a position in CAH.
Cardinal Health has already rewarded shareholders with a sharp move and a very large 5 year total return, yet recent earnings strength and a small discount to analyst targets raise a simple issue. Is most of the upside already cashed in, or is the valuation still leaving meaningful room ahead?
Most Popular Narrative: 4% Undervalued
Cardinal Health last closed at $281.10 compared to the analyst consensus Narrative fair value of $291.53. This implies a modest discount based on the analyst consensus Narrative on Simply Wall St, which ties together price targets with revenue and earnings forecasts.
The expansion of specialty pharma distribution, multi specialty MSO platforms in areas like oncology, urology and gastroenterology, and a rapidly scaling Biopharma Solutions business that is ahead of its prior growth plan points to a larger mix of higher value services that can influence segment profit and overall earnings.
See why 65 investors see Cardinal Health as 4% undervalued.
Result: Fair Value of $291.53 (UNDERVALUED)
Still, Cardinal Health carries real pressure points, including product quality issues such as levothyroxine recalls and sensitivity to inflation-linked input costs in its medical segment.
Find out about the key risks to this Cardinal Health narrative.
Another View: Cardinal Health On Earnings Multiples
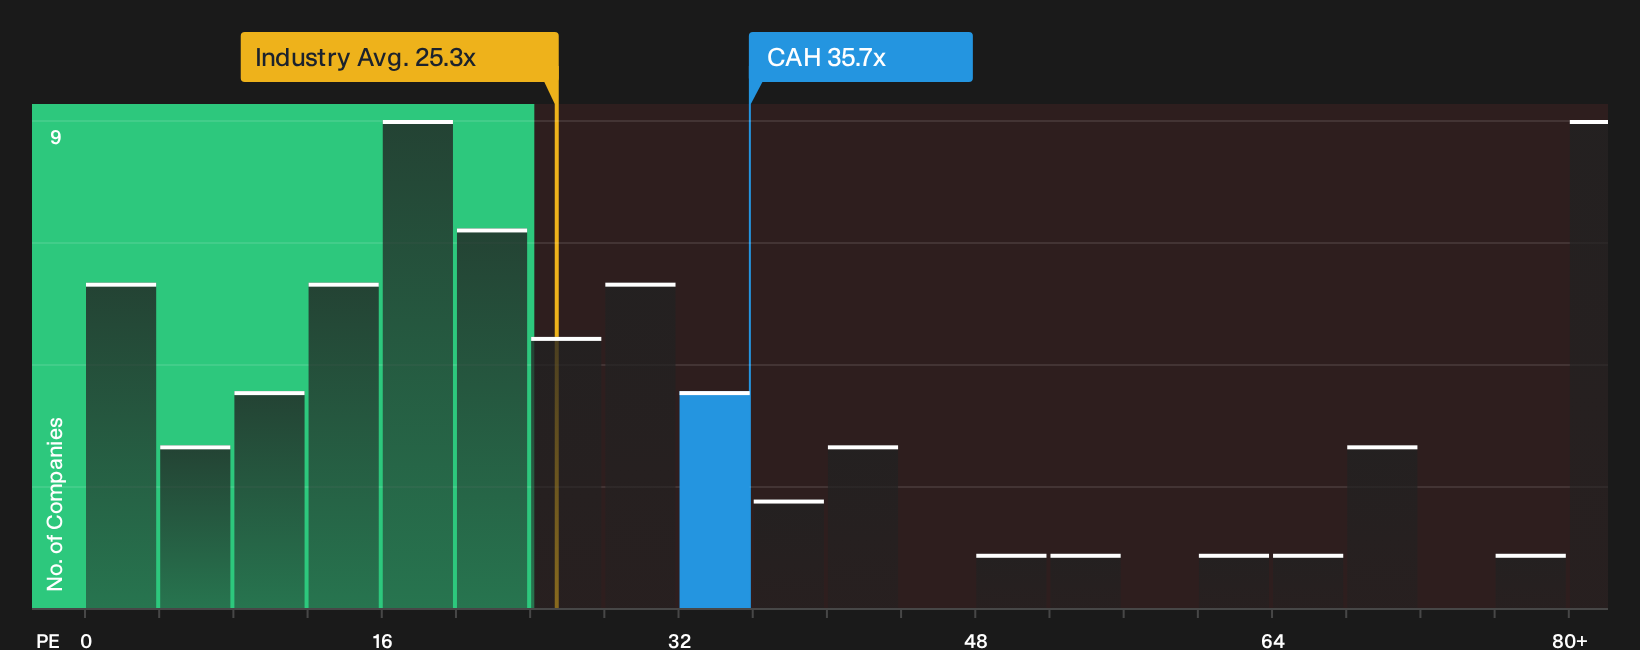
The cash flow story for Cardinal Health looks supportive, yet the simple earnings multiple paints a tougher picture. The stock trades on a P/E of 35.7x, compared with 25.3x for the wider US Healthcare group and 28.2x for peers, while the fair ratio sits at 31.9x.
That gap suggests investors are already paying a premium multiple, which reduces margin for error if growth or profitability fall short of expectations. It raises a practical question for anyone watching CAH: Is this premium a reasonable price for quality, or is it pushing nearer to stretch territory?
Before leaning too heavily on any single metric, it is worth stress testing this richer P/E against your own expectations for earnings power, debt, and cash generation over the next few years. You can then compare that with our valuation breakdown and fair ratio analysis in See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If sentiment in this Cardinal Health story feels mixed, that is the point. Both risk and reward signals are on the table right now, so move quickly, review the underlying data, and weigh the 3 key rewards and 3 important warning signs
Looking for more Cardinal Health sized ideas?
Do not stop with Cardinal Health. Broaden your watchlist now, or you risk missing other opportunities that line up better with your goals and risk tolerance.
- Target strong fundamentals and robust financial footing by reviewing our curated list of solid balance sheet and fundamentals (24 results) to help you build a sturdier core for your portfolio.
- Zero in on quality at a reasonable price by scanning 32 high quality undervalued stocks that may align more closely with the valuation profile you want.
- Prioritise resilience and capital protection by assessing 31 resilient stocks with low risk scores that could help smooth out volatility across your holdings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com