
Should Stronger Earnings Require Action From Andersons Stock Investors?
- The Andersons, Inc. reported third quarter 2026 sales of US$2,833.72 million and net income of US$46.45 million, with basic earnings per share from continuing operations of US$1.37.
- Across the first nine months of 2026, Andersons' net income of US$136.2 million and basic EPS of US$4.01 from continuing operations are described as indicating a materially stronger earnings profile than the prior year period.
- Attention now turns to how Andersons' sharply higher quarterly earnings and EPS may influence the existing investment narrative around renewables and agribusiness.
Andersons Investment Narrative Recap
To own Andersons, you need to believe the renewables and agribusiness platform can turn recent earnings momentum into steadier cash generation. The latest quarter and year-to-date results show higher net income and EPS from continuing operations, which supports that idea, but they also raise the bar for execution on ethanol, grain merchandising and premium ingredients projects.
In the near term, a key swing factor is how effectively Andersons converts its renewables footprint and Port of Houston buildout into consistent margins while managing grain and fertilizer volatility. The biggest immediate risk is that weak demand pockets, grain oversupply or softer fertilizer volumes could reverse some of the recent profitability gains.
The analyst consensus narrative on Simply Wall St highlights several operational catalysts. One of the most relevant to the recent earnings release is the push to capture 45Z tax credits and decarbonize ethanol plants, with debottlenecking and potential carbon sequestration. Recent EPS strength offers a live snapshot of how important these credits and operational adjustments can be for net income.
Those same analysts describe expansion at the Port of Houston and investment in value-added grain and nutrient processing as key levers for future earnings quality. In that context, Andersons' latest quarter serves as a test of how well these projects offset risks such as Brazilian ethanol competition and tighter fertilizer markets, rather than a final verdict on their success.
Analysts currently model Andersons reaching about US$13.2b in revenue and US$245.1 million in earnings by 2029, which implies 5.9% yearly revenue growth and an earnings increase of roughly US$41.5 million from US$203.6 million today.
Discover why Andersons' fair value points to a potential 71% upside from its current price, which could narrow quickly.
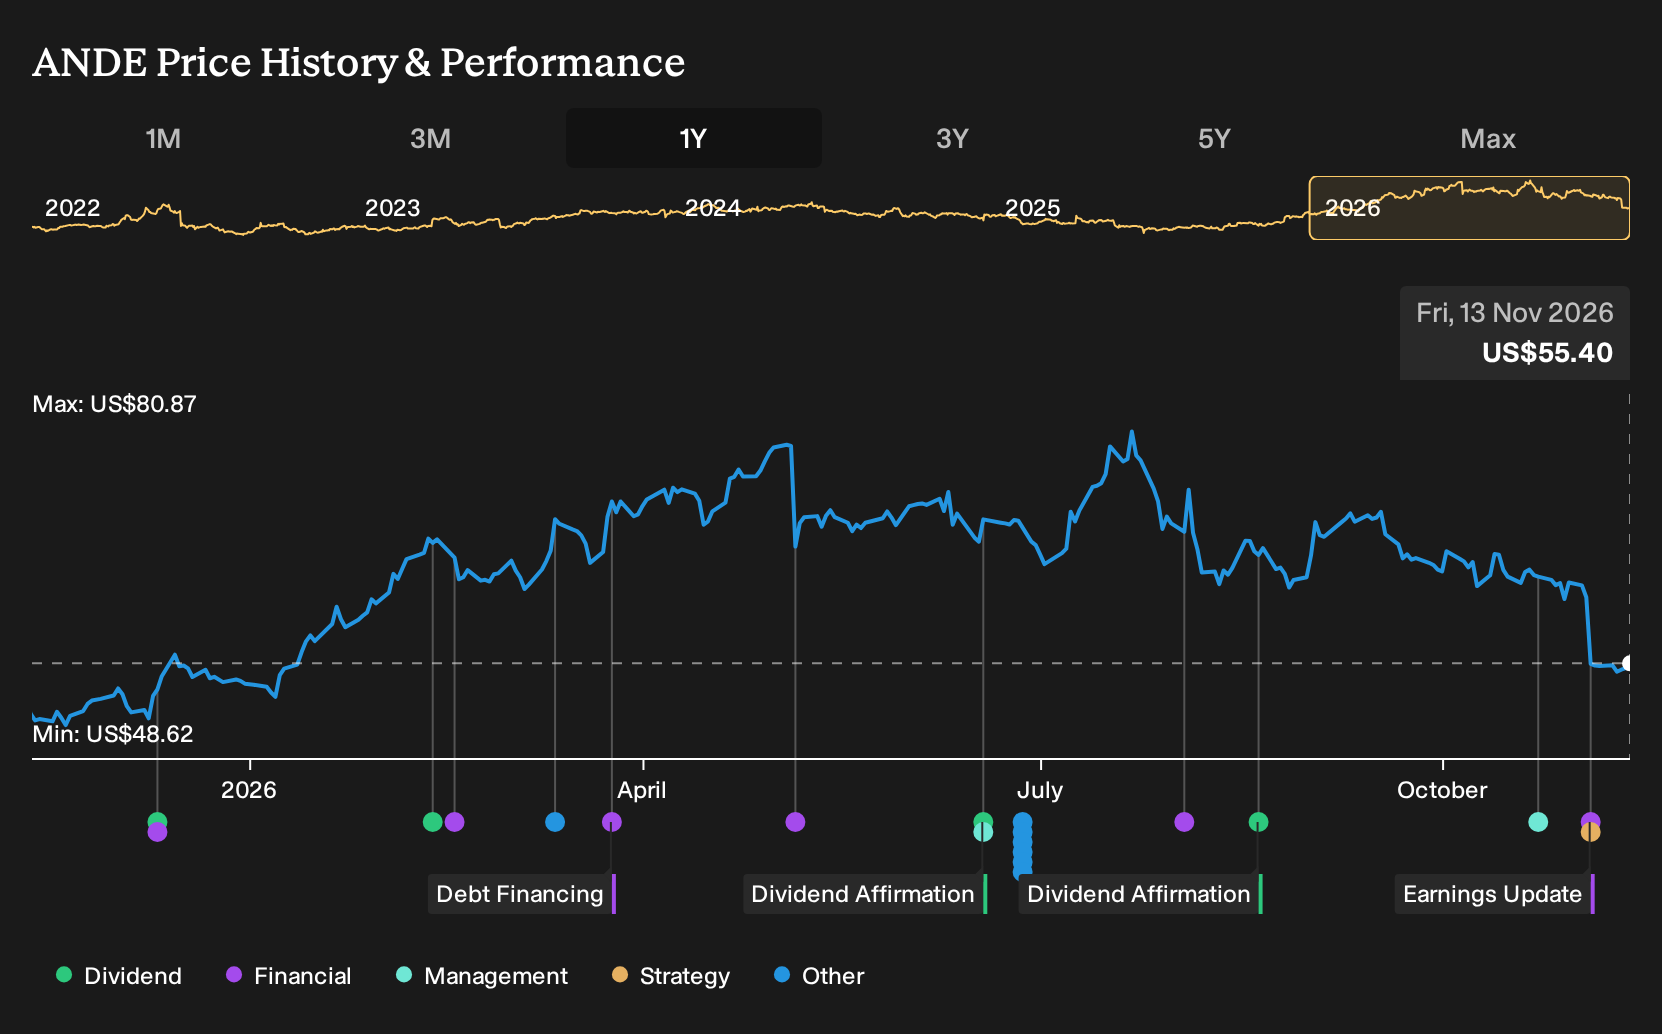
Exploring Other Perspectives
One alternate angle focuses on Andersons' reliance on 45Z tax credits. The most cautious analysts were penciling in about US$12.0b of 2029 revenue and US$257.9 million of earnings before this quarter, yet still framed that as vulnerable if policy terms tighten. You can treat this earnings beat as a prompt to compare those assumptions with your own view.
Explore another Andersons fair value estimate, including one that suggests it could be worth just $95.00!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Andersons research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Andersons. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Andersons' overall financial health at a glance.
Looking for more investment ideas beyond Andersons?
Once you have a view on Andersons, it can help to compare that thesis with other companies that have clear financial traits, so your portfolio is built on more than one story.
- If you want income resilience to balance earnings-driven ideas like Andersons, check out dependable payers screened as 6 dividend fortresses.
- For investors who care most about financial strength, stress test your watchlist against a list of solid balance sheet and fundamentals (24 results) that can better handle rough patches.
- If you enjoy finding opportunities before the crowd, broaden your hunting ground with a 20 high quality undiscovered gems that already show solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com