
Learn Why The Bull Case For 1&1 (XTRA:1U1) Could Change Following Profit Drop
- 1&1 AG reported results for the nine months to 30 September 2026, with sales of €3,401.87 million and net income of €11.72 million, compared with €3,016.26 million and €110.71 million a year earlier.
- The combination of higher sales and sharply lower earnings suggests rising costs or margin pressure inside 1&1 AG's telecom operations, which matters for a business that is investing heavily in its own network.
- The next step is to assess how this sharp net income drop shapes 1&1 AG's investment narrative around network build and margins.
Compare 1&1's margin pressure with companies that currently pair telecom exposure with stronger fundamentals by scanning our hand picked list of solid balance sheet and fundamentals (198 results).
1&1 Investment Narrative Recap
To own 1&1, you need to be comfortable with a telecom group that is trading near a full P/E multiple and is still in a heavy build phase. The analyst consensus Narrative on Simply Wall St leans on the idea that shifting more traffic onto its own OpenRAN and fiber assets can eventually support better EBITDA and free cash flow. The latest nine month figures, with net income of €11.72 million on €3,401.87 million of sales, keep the focus squarely on execution.
In the short term, the main potential catalyst remains management’s 2026 EBITDA guidance of about €800 million and the expected EBITDA ramp in 2027 and 2028. The sharp earnings compression increases the risk that roaming costs, depreciation and Consumer and Small Business weakness keep margins under pressure. If those headwinds persist, the current high capital spending and low net margin profile could weigh on sentiment around 1&1.
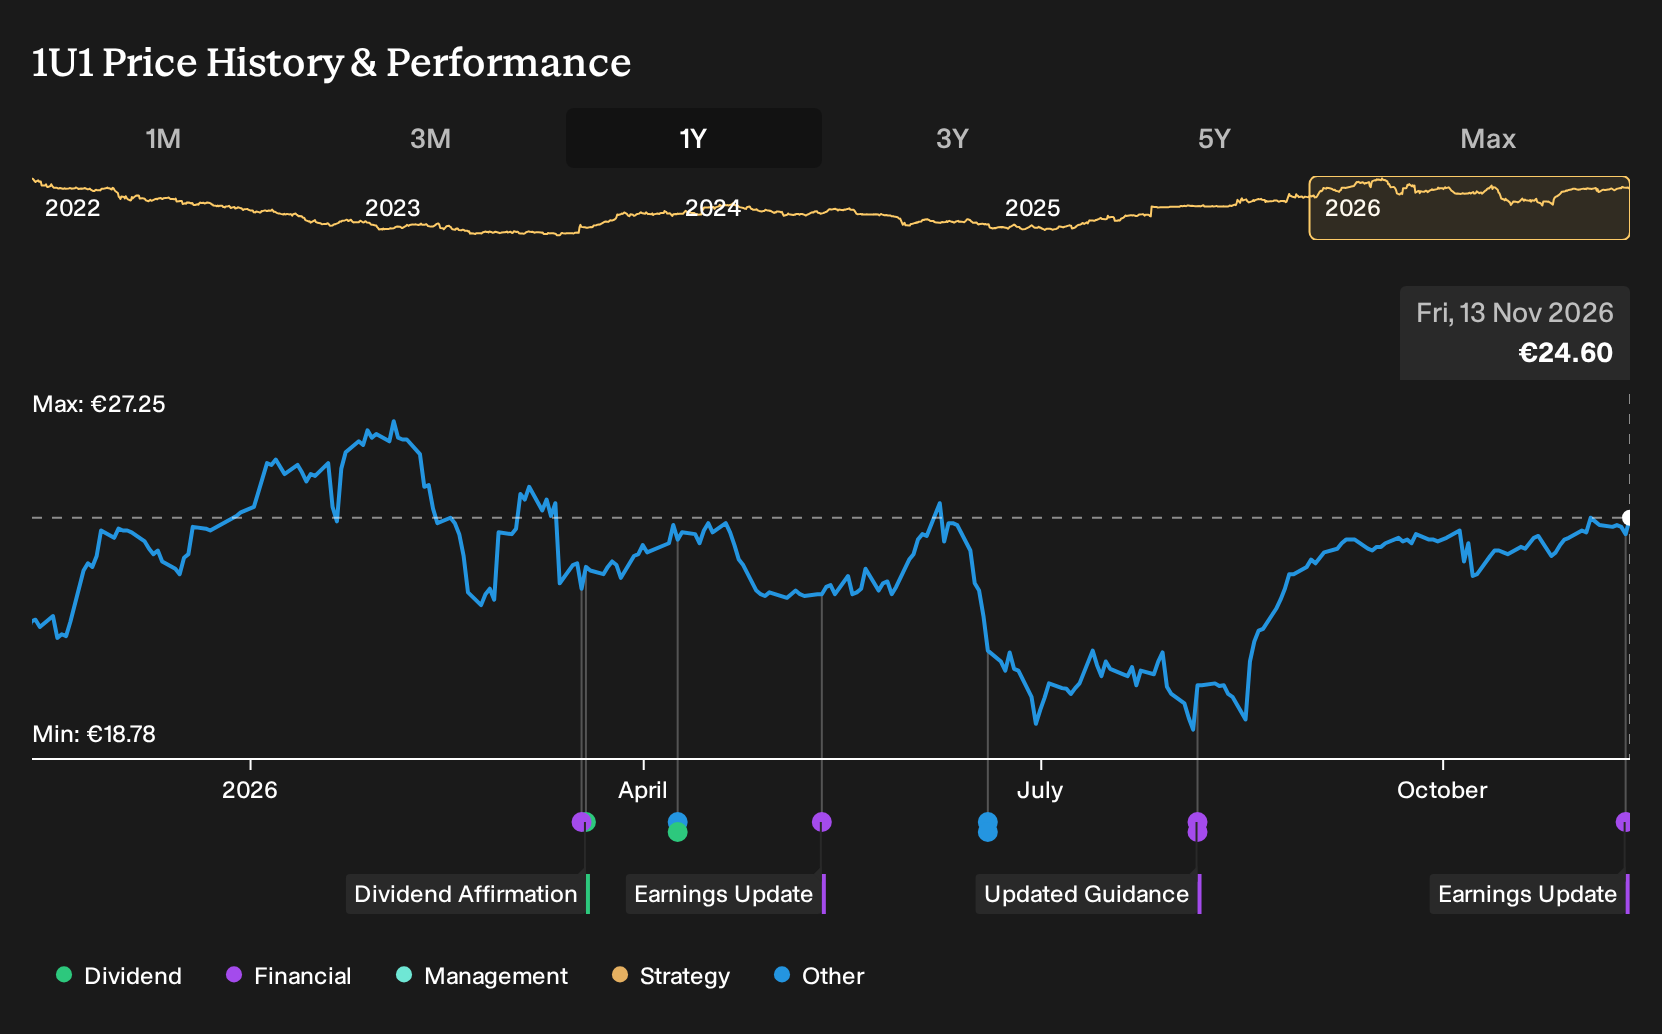
The most relevant recent update is the Q3 2026 earnings call on 12 November 2026. Sales for the first nine months were €3,401.87 million compared with €3,016.26 million a year earlier, while net income was €11.72 million versus €110.71 million. Basic earnings per share from continuing operations were €0.07 compared with €0.63. The income statement now reflects much thinner profitability.
For you as a shareholder, that call matters because it tests the timeline behind the catalysts outlined earlier, such as the own network migration and expected operating EBITDA growth of roughly €100 million per year in 2027 and 2028. The step down in earnings heightens the existing risks flagged around roaming dependence, Consumer and Small Business EBITDA pressure and low current Return on Equity. Execution on the network rollout and cost base will likely shape whether 1&1 can move closer to that medium term earnings profile.
1&1's narrative projects €4.7 billion in revenue and €198.7 million in earnings by 2029. This assumes 2.0% yearly revenue growth and an earnings increase of about €77 million from €121.5 million today.
Uncover why 1&1's fair value appears to be roughly in line with its current price.
Exploring Other Perspectives
For a different angle on 1&1, focus on the bullish catalyst around earnings power. The most optimistic analysts were pencilling in revenue of about €4.8 billion and earnings of €309.5 million by 2029, well above consensus. That camp saw the telecom group as undervalued, although these views predate the latest earnings shock. Reader, use this as a cue to compare several narratives before leaning on any single forecast.
Explore 2 other 1&1 fair value estimates, including one that suggests it could be worth as much as €25.21.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your 1&1 research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for 1&1. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate 1&1's overall financial health at a glance.
Looking For More Ideas Beyond 1&1?
Once you have a view on 1&1, it can help to widen the lens and compare it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you do that quickly by filtering for financial strength, income potential, or under followed opportunities.
- If capital preservation sits high on your list, filter for resilient companies using our 210 resilient stocks with low risk scores. This can help you see which businesses pair steadier balance sheets with lower risk scores.
- If value is your focus, scan for mispriced opportunities with solid fundamentals through the 198 high quality undervalued stocks. You can then see which tickers currently trade below their fair value estimates.
- If income is a priority, hunt for potential cash return opportunities using the 220 dividend fortresses. This allows you to compare yields, payout ratios, and safety in one place.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com