
Water Recycling Push Might Change The Case For Investing In Ecolab Stock (ECL)
- Ecolab is expanding its water recycling operations by combining chemicals, monitoring systems, and on site services, with management highlighting strong traction in semiconductor fabs and data center cooling where Ovivo’s ultrapure water systems support high levels of reuse.
- The focus on integrating Ovivo’s technology with Ecolab’s recycling know how reflects a push for deeper, higher value roles inside high tech water infrastructure rather than just selling standalone chemicals.
- We will look at how Ecolab's investment narrative intersects with its push into semiconductor water reuse through the Ovivo combination.
Ecolab Investment Narrative Recap
To own Ecolab, you need to be comfortable with a story built on water reuse, high tech customers and pricing power through the One Ecolab approach. The short term swing factor is how well the business converts strong interest in semiconductor and data center projects into live installs while keeping service quality high.
The biggest current tension is execution against high capital expenditure and acquisitions like CoolIT. The analyst consensus narrative on Simply Wall St flags these as a drag on near term free cash flow. Softer heavy industrial demand or raw material cost spikes that pricing cannot fully offset would also test the thesis.
The Ovivo combination sits closest to the current news around semiconductor water reuse. Ovivo brings ultrapure systems that let fabs recycle more than 80% of their water. Ecolab layers on chemicals, control systems and on site service. Together, that keeps the firm deeper inside customer utilities rather than at the edge of the process.
This matters because Global High Tech is one of the growth engines analysts are watching, alongside Digital, Life Sciences and Pest. If Ecolab executes cleanly on integrating Ovivo and scaling reuse projects inside fabs and data centers, it directly supports those segment ambitions while also stressing the usual risks around project delivery, capex and customer concentration.
Ecolab's long term story assumes revenues reach US$20.7b and earnings come to US$3.3b by 2029, based on analysts' forecast for 7.2% yearly revenue growth and an earnings increase of about US$1.2b from the current US$2.1b level.
Uncover why Ecolab's fair value indicates a 5% potential upside to its current price that could narrow quickly.
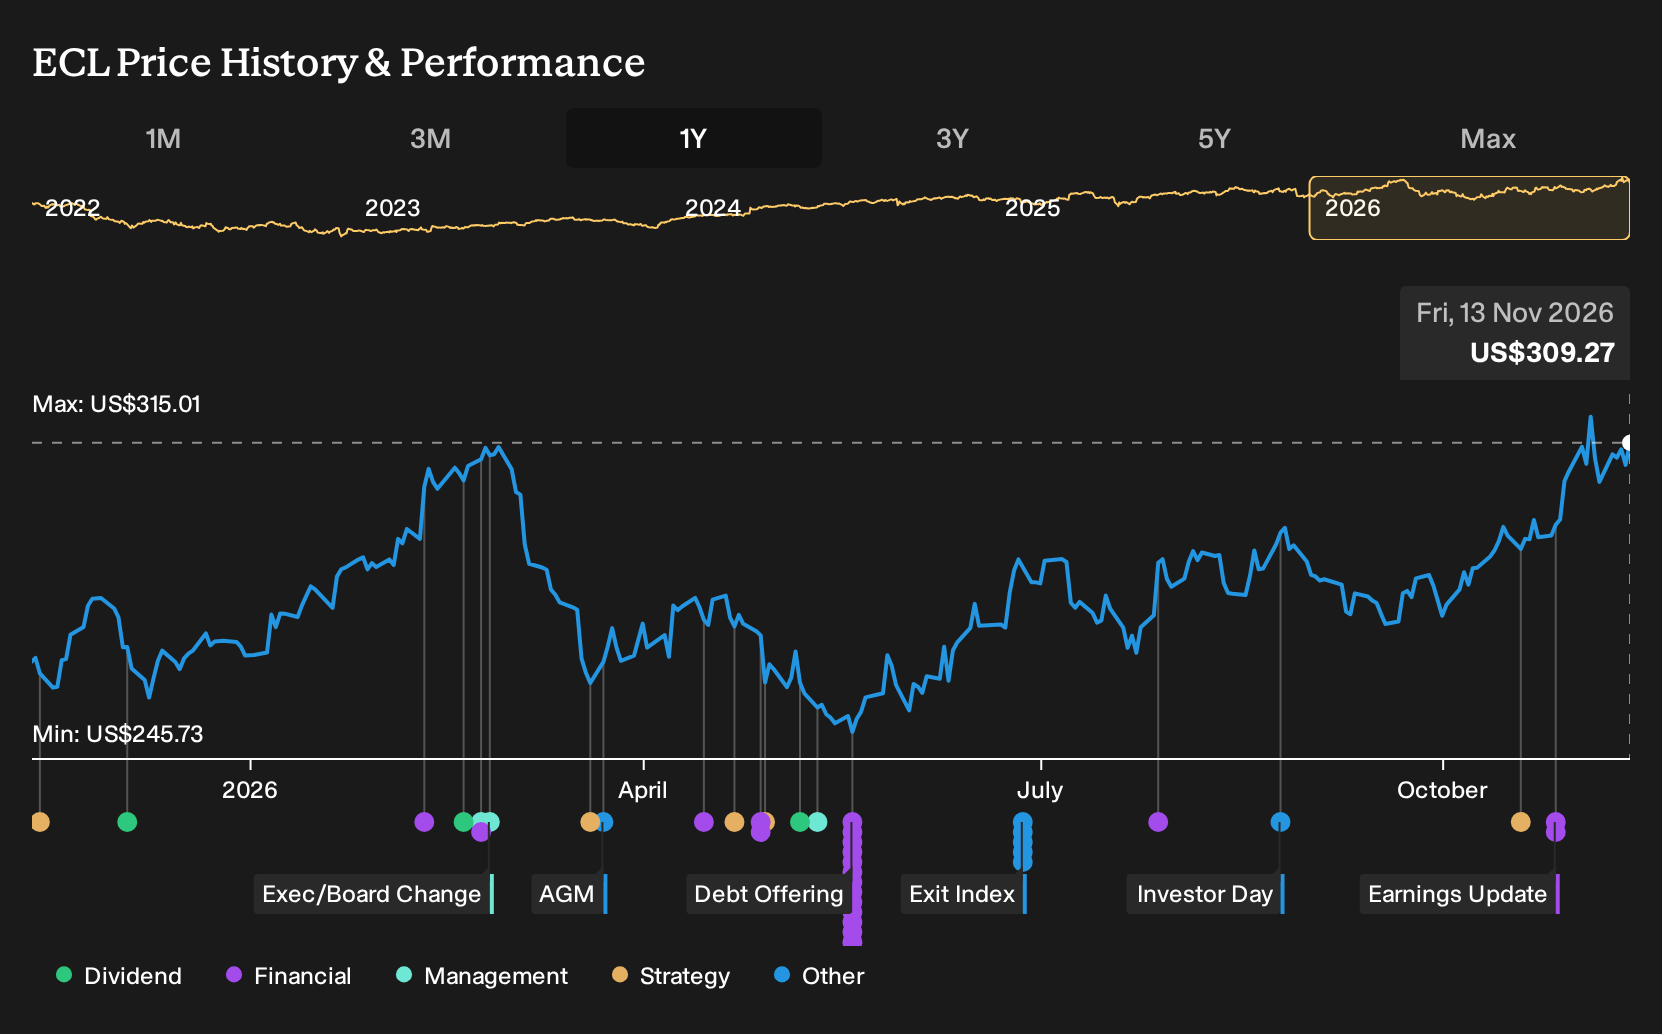
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community range from about US$233 to US$325, which already shows how far opinions on Ecolab can stretch. Those estimates do not reflect the latest semiconductor water reuse push, while risks around heavy industrial demand and high capex keep the debate wide open for you to explore.
Explore another Ecolab fair value estimate, including one that suggests there could be as much as 25% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ecolab research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ecolab. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ecolab's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ecolab?
If Ecolab's push into high tech water reuse has sharpened your interest in different types of quality, income or resilience, it can help to line it up against a wider watchlist built from clear filters.
- If you want a focus on financial strength and cleaner balance sheets, start by scanning a list of solid balance sheet and fundamentals (24 results) that meet strict debt and liquidity criteria.
- For investors hunting for quality at a reasonable entry point, compare Ecolab with a 32 high quality undervalued stocks that combine solid fundamentals with pricing that screens as potentially attractive.
- If steady income is a priority, build a shortlist around 6 dividend fortresses and see which yields line up with your risk tolerance and time horizon.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com