
Should Bond Sale Require Action From Edenred (ENXTPA:EDEN) Investors?
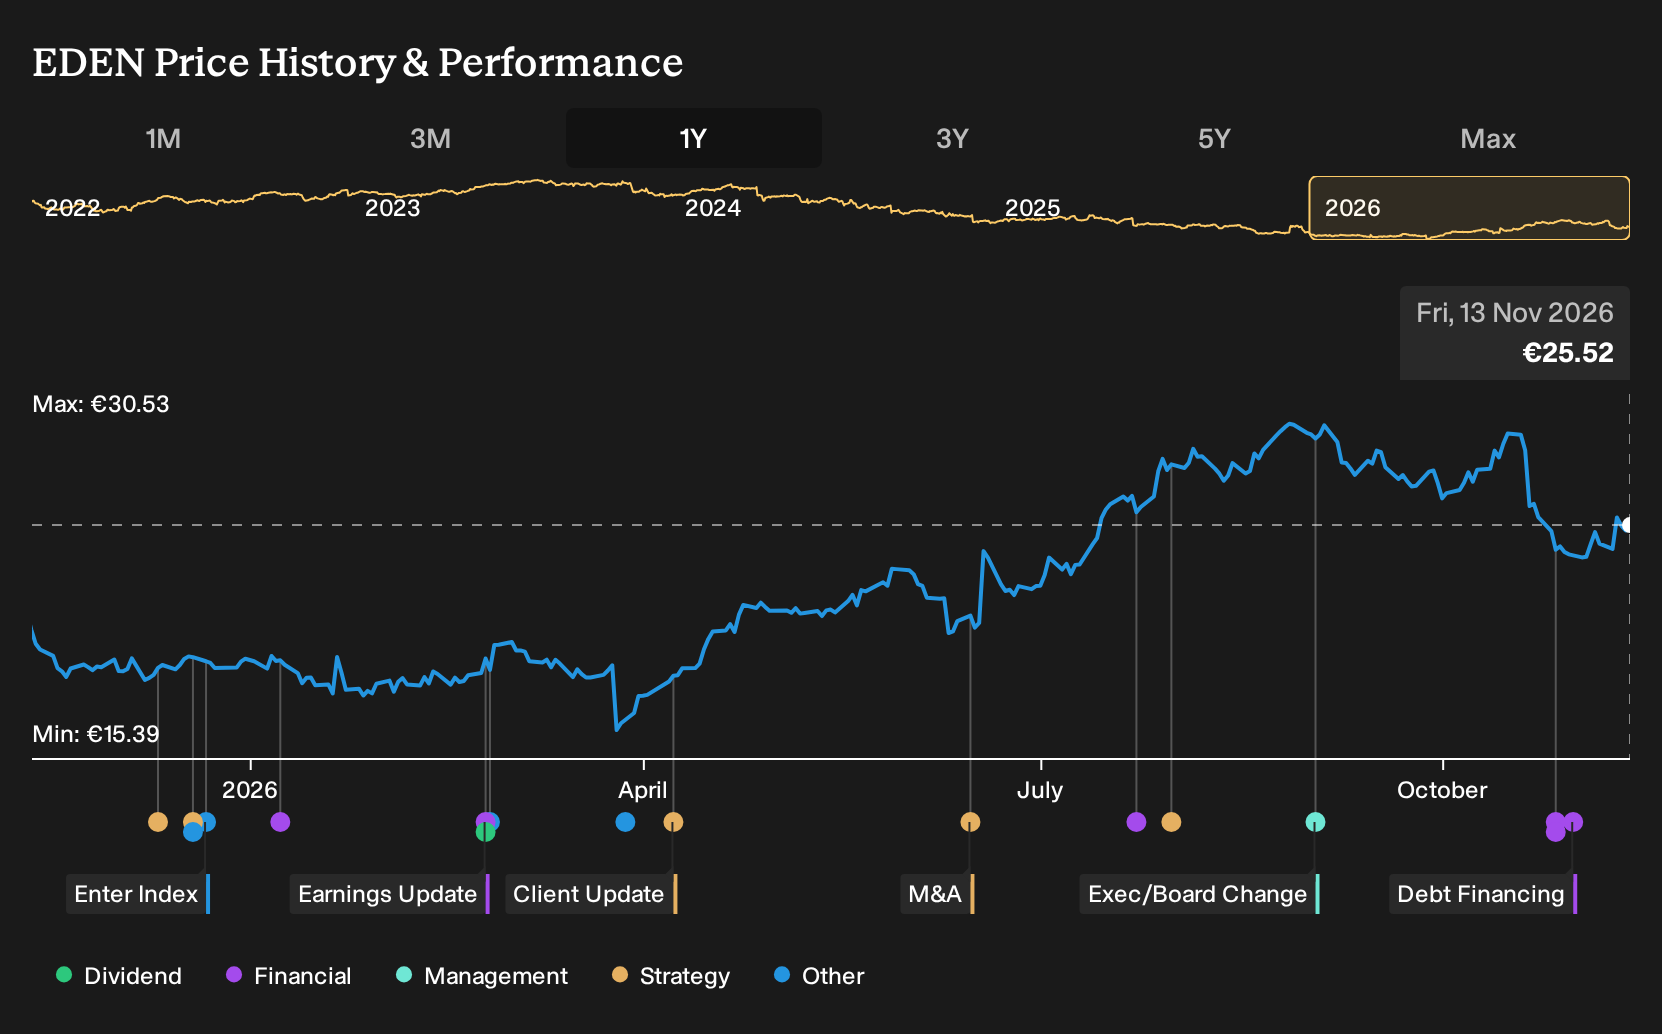
- Edenred completed a dual tranche bond issue in October 2026, raising €800 million through a 2 year floating rate note and a 7.25 year fixed rate bond, with coupons tied to three month Euribor plus 75 basis points and 4.75% respectively.
- The debt issue drew solid demand from international investors, which supports Edenred's A- credit rating and extends its average bond maturity to 4.4 years after upcoming repayments.
- Now the focus shifts to how Edenred's extended debt maturity profile could influence the existing investment narrative and balance sheet flexibility.
Scan how Edenred's funding move compares with peers by reviewing 210 resilient stocks with low risk scores built around balance sheets that prioritise resilience and liquidity discipline.
Edenred Investment Narrative Recap
Owning Edenred means believing its digital benefits and mobility platform can keep adding clients and usage even as regulation in Brazil and Italy compresses 2026 EBITDA and keeps margins under pressure. The analyst consensus Narrative on Simply Wall St still leans on earnings growing about 7.8% a year and revenue about 6.6% a year. That hinges on the Amplify 25 to 28 plan, Beyond Food and Beyond Fuel expansion, and SME wins offsetting the hit from regulatory resets.
Right now, the key near term swing factor is whether efficiency gains from data and AI investment actually show up after a period where operating expenses rose 6.6% and H1 2026 EBITDA fell 4.6% like for like. The recent €800m bond issue looks more like plumbing for the balance sheet than a direct catalyst for operating trends. It reduces refinancing noise rather than changing the demand or regulatory story.
The October 2026 bond deal matters most because it interacts with an already leveraged structure and negative shareholders equity. Edenred now has longer dated funding, with average bond maturity moving to 4.4 years after the 2026 and 2027 repayments. For you as a shareholder, that can reduce near term refinancing risk while the firm works through the Brazil and Italy reset and the Middle East slowdown.
That extra breathing room can help management stay focused on catalysts such as growing Beyond Food and Beyond Fuel, where offerings already account for more than 40% of revenue, and pushing deeper into SME and mid market segments. Execution on the Amplify 25 to 28 efficiency targets, including lower acquisition cost and higher lead conversion, remains the core operational test. The bond issuance simply gives Edenred more time to prove that thesis without needing to rely on fresh equity or rushed asset sales.
Edenred's current analyst narrative points to €3.4b revenue and €610.3m earnings by 2029, based on revenue expanding at 7.6% a year and consensus earnings rising by about €110m from €500.0m today.
Discover how Edenred's fair value suggests a potential 20% upside to its current price before the gap closes.
Exploring Other Perspectives
Some of the most optimistic analysts see Edenred’s heavier AI and software style push as the real catalyst, not the bond issue itself. They were already pencilling in €3.6b of revenue and €652.9m of earnings by 2029. This fresh funding move can be treated as a new test of whether that upbeat script still holds or needs a rewrite.
Explore 4 other Edenred fair value estimates, including one that suggests a potential upside of up to 291% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Edenred research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Edenred. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Edenred's overall financial health at a glance.
Looking For More Ideas Beyond Edenred?
Once you have a view on Edenred, it can help to compare that thesis with other opportunities that line up with your own risk tolerance, time horizon, and balance sheet preferences.
- If capital preservation sits high on your priority list, consider starting with a 210 resilient stocks with low risk scores that keeps volatility and financial fragility in check.
- For readers hunting for mispriced opportunities with strong fundamentals, a focused 198 high quality undervalued stocks can surface candidates that might warrant a place on your watchlist.
- Income driven investors who prioritise stability from cash distributions may want to review a hand picked set of 220 dividend fortresses that clear a 5% yield hurdle.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com