
What Haemonetics Stock's Raised Guidance Means For Shareholders
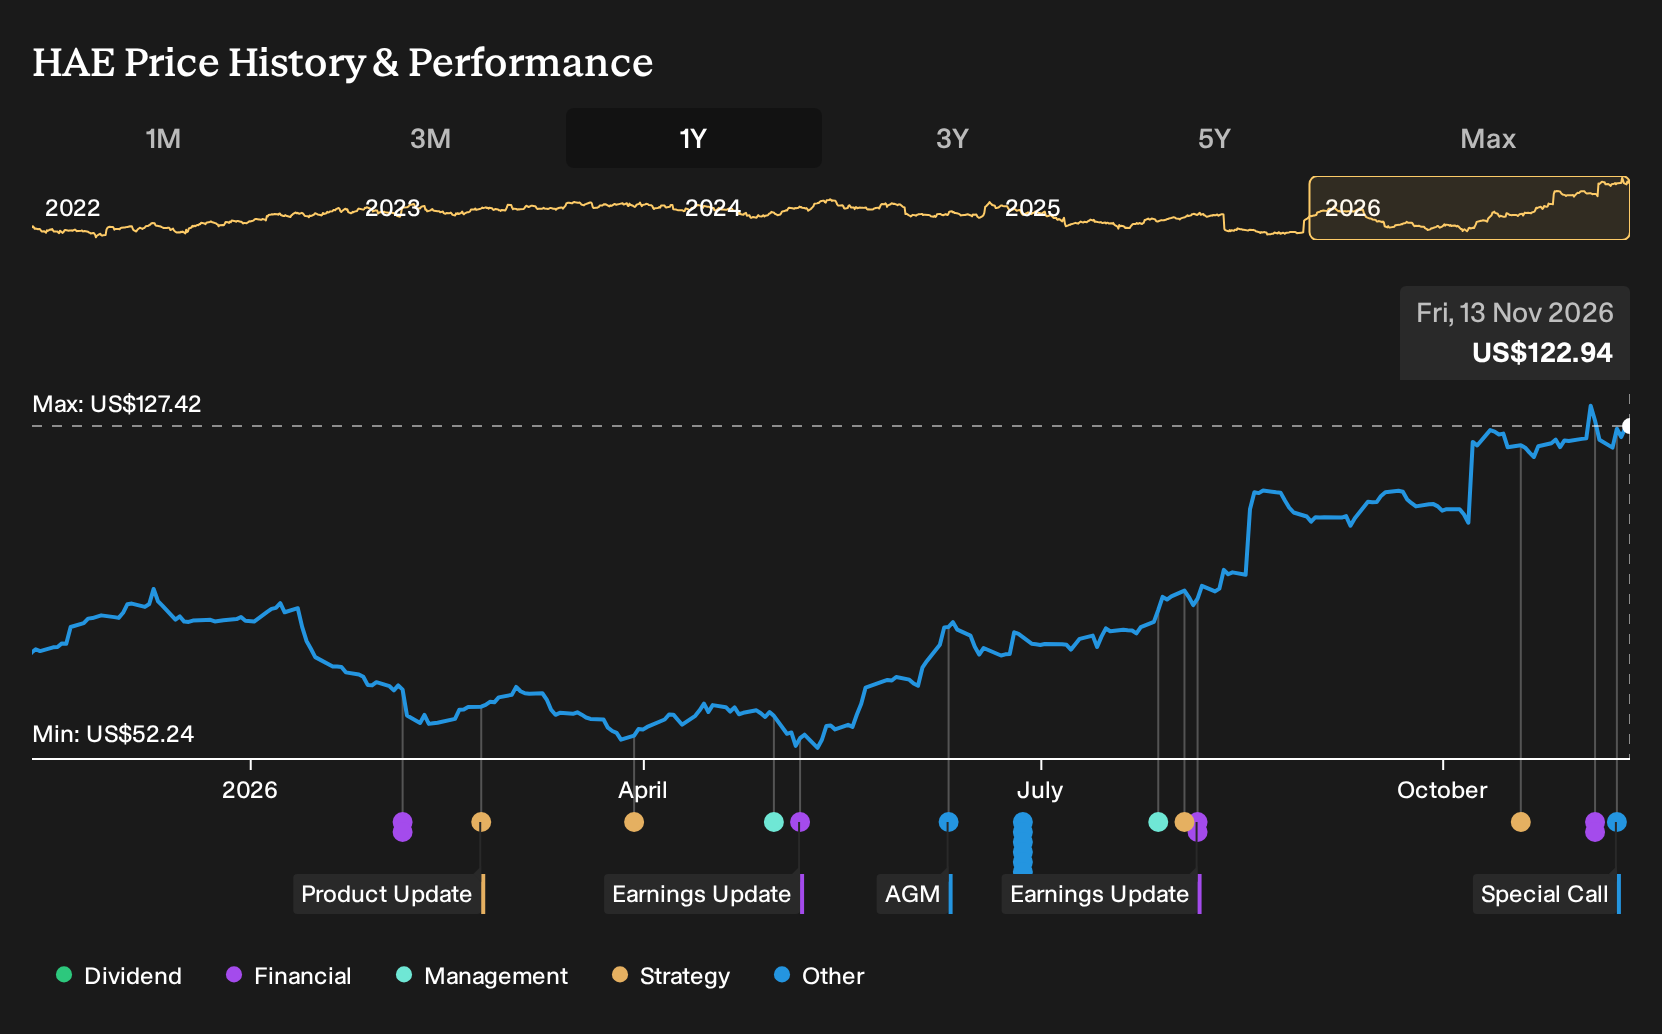
- Haemonetics reported second quarter fiscal 2027 sales of US$357.76 million and net income of US$46.31 million, raised full year 2027 revenue guidance to 8% to 11% growth, and outlined its story to investors through recent earnings, guidance and upcoming R&D and conference events.
- The combination of higher revenue guidance and stronger earnings per share from continuing operations indicates that Haemonetics is running its model with tighter execution and a clearer view on demand and cost control.
- We will now see how Haemonetics' investment narrative could be reshaped by the raised 2027 revenue guidance and stronger quarterly profitability.
Haemonetics Investment Narrative Recap
To own Haemonetics, you need to believe the plasma systems, TEG hemostasis tools and vascular closure products can keep gaining share while margins stay resilient despite tariffs and higher self-insured medical costs. The raised 2027 revenue outlook to 8% to 11% growth, alongside firmer earnings, supports that operating thesis but does not eliminate existing cost and leverage concerns.
The key near term catalyst remains execution on NexSys with Persona PLUS and higher margin hospital disposables converting into steady cash generation. This matters with roughly US$1.2b of debt and net leverage near 2.7x EBITDA. The biggest current risk is that competition and tariff headwinds compress margins faster than the analyst consensus Narrative on Simply Wall St assumes.
The most relevant update for this story is the November 5 earnings release, which showed second quarter fiscal 2027 sales of US$357.76 million and net income of US$46.31 million, with basic earnings per share from continuing operations at US$1.02. Those numbers, together with the six month figures, give investors fresher evidence on how Haemonetics is handling mix, pricing and operating costs.
Viewed against the catalysts in the analyst consensus Narrative on Simply Wall St, the stronger profitability profile supports the idea that a richer disposable and software mix can help fund R&D, withstand tariffs and service debt. It also frames the upcoming R&D day and UBS Global Healthcare Conference appearance as checkpoints on whether plasma, TEG and vascular closure can keep offsetting competition and financing risk.
Haemonetics' current earnings are US$103.9 million. Analysts project US$258.2 million of earnings and US$1.6b of revenue by 2029, which implies 5.7% yearly revenue growth and roughly a 2.5x earnings increase from today.
Uncover how Haemonetics' fair value indicates a 9% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
One alternate view puts Haemonetics’ cost inflation risk front and center. The most cautious analysts already had 2029 earnings closer to US$248.0 million on roughly US$1.6b of sales before this guidance hike. That reflects a more muted margin story. You can use that tougher stance to pressure test your own reaction to the new outlook and upcoming R&D and UBS events.
Explore another Haemonetics fair value estimate, including one that suggests it could be worth just $134.00.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider doing your own research and forming your own view.
- A great starting point for your Haemonetics research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Haemonetics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate Haemonetics' overall financial health at a glance.
Looking For More Ideas Beyond Haemonetics?
If Haemonetics has sharpened your interest in healthcare and quality fundamentals, it can be useful to widen your watchlist with stocks that share solid financial traits but sit in very different corners of the market.
- For investors focused on durable businesses first and price action second, start with a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions without stretching their finances.
- If resilience is your priority and you prefer businesses with steadier risk profiles, consider scanning a 31 resilient stocks with low risk scores that scores well on volatility, leverage and earnings quality.
- For those who like to hunt for lesser known opportunities that still have strong fundamentals, browse a 20 high quality undiscovered gems that are not yet widely followed but already post solid financial markers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com