
Why Aptiv Bears Were Right Before The Drop
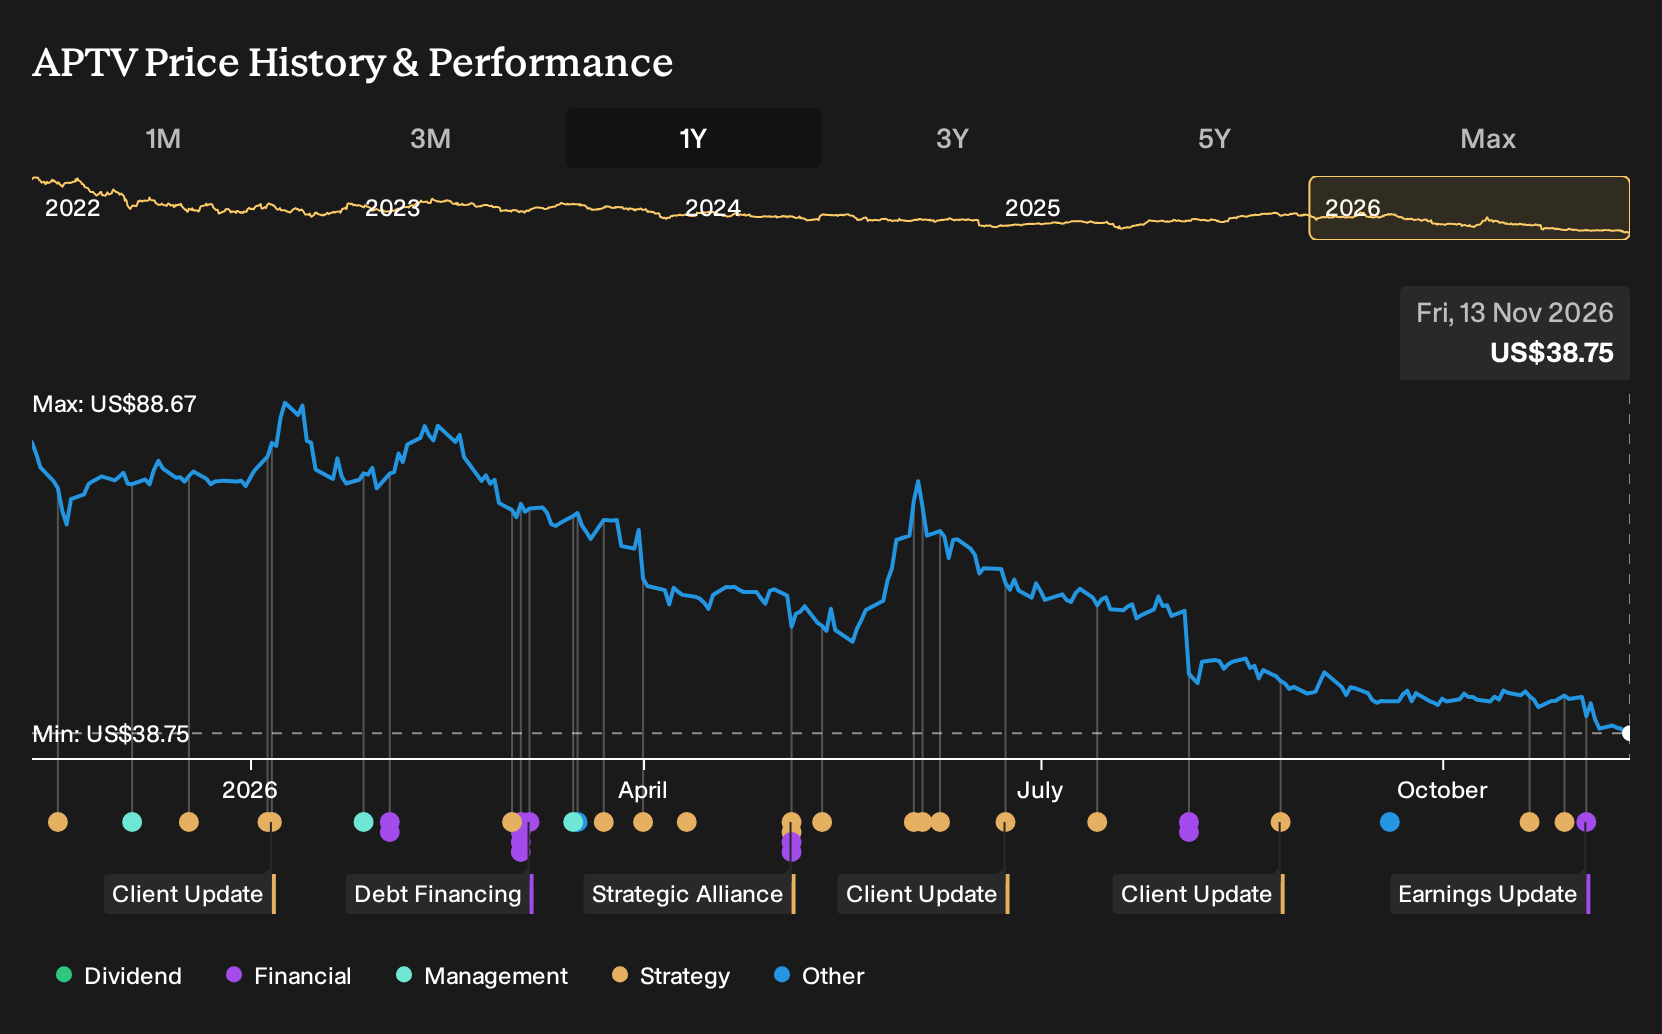
If you had paused before buying Aptiv in late 2025, watching analysts argue over spin offs, ADAS growth and urban mobility risks instead of pulling the trigger, your portfolio would look different today. Investors who held Aptiv over the past year are down 42.0%, including dividends. The backward step is clear. The harder question is which assumption on record then, from China demand to OEM insourcing, deserved closer scrutiny before committing capital?
This theme extends beyond Aptiv. See which of 88 robotics and automation stocks may still merit a closer look.
The Argument You Would Have Been Weighing On Aptiv
The shares cost US$81.05 at the start of the period, and Aptiv sat between two well constructed stories about where its auto electronics franchise might head next.
The bullish narrative saw spin offs and ADAS scale creating a reshaped business. It pointed to a Fair Value of US$88, described as the price those growth assumptions implied, built on revenue rising 5.5% a year and profit margins reaching 8.2%.
The bearish script focused on margin pressure from shared mobility and OEM insourcing. It anchored on a Fair Value of US$55 and warned that rising input costs and customer concentration could compress earnings even if headline demand held up.
What The Results Changed For The Aptiv Thesis
The clearest development came from Aptiv’s reported turnaround in profitability. Management moved from a net loss of US$491 million in Q3 2025 to net income of US$194 million in Q3 2026, with net margin shifting from a loss of 15.7% to a 6.1% profit. This supported parts of the bullish margin story, while still leaving long run ADAS and spin off expectations unproven.
The lesson is simple. When a thesis leans on future margin expansion, you test it by watching net margin and absolute profit in the filings, not by leaning on guidance soundbites or short term share moves.
What Aptiv’s Lower Price Asks You To Believe
Today Aptiv trades at US$38.75, well below where it started a year ago. The bullish analyst Narrative on Simply Wall St places its Fair Value above the current share price, based on a shift toward higher margin non automotive work and heavier use of buybacks.
The Narrative leans on robotics, drones and edge AI to reshape earnings power. For the recent fall to look like an opening rather than a warning, a buyer today would need to believe those newer programs scale while China auto volatility stays manageable.
"Acceleration of Aptiv’s robotics and drone pipeline, including partnerships with three leading robotics manufacturers and a first commercial drone award with over US$500 million of lifetime revenue, creates a fresh non automotive earnings stream that could re rate the mix of consolidated revenue and EBITDA margins toward the higher levels seen in Engineered Components."
The price and this Narrative do not agree. → Uncover what this Narrative says Aptiv is actually worth
Where Aptiv’s Story Connects Outward
Aptiv is wrestling with what mobility looks like once software takes the wheel. You can also look one step away from its wiring and controllers.
Some engineers are chasing a different angle. Instead of upgrading cars, they are trying to automate the physical work around them.
The focus is a general purpose robot that can be taught new tasks. Skills are sold like software modules, which turns labor into recurring subscriptions.
If that model gains traction, the discussion around vehicles and electronics broadens quickly. Your question becomes how far the value may shift toward whoever owns the robot’s operating system.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 71% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com