
Schrödinger (SDGR) Dropped, But What Is Really Driving Attention Now?
Schrödinger (SDGR) just put fresh third quarter numbers on the table, giving investors a closer look at how its software and drug discovery efforts are translating into revenue and ongoing losses.
The fresh earnings update landed alongside a US$29.53 share price that pulled back 4.28% on a 1-day share price return. However, the 90-day share price return of 67.88% and 1-year total shareholder return of 67.40% point to strong recent momentum despite weaker 3 and 5-year total shareholder returns.
Spot fresh momentum in Schrödinger’s niche, then scan a curated set of 36 healthcare AI stocks that are also leaning on software, modelling and AI to drive their pipelines.Schrödinger’s share price has already risen significantly over the past quarter, yet the business is still posting sizeable losses. Does it make more sense to commit capital now or wait for a cheaper entry point as the numbers evolve?
Most Popular Narrative: 5% Undervalued
On the analyst consensus Narrative on Simply Wall St, Schrödinger’s fair value of $31.14 sits modestly above the latest $29.53 close, framing the recent rally as still slightly short of that modelled outcome.
Strong pipeline advancement and early clinical progress, alongside over US$750 million of realized economics from partnered programs and updated guidance for about US$150 million of drug discovery revenue over the next three years, reinforces the case that Schrödinger’s discovery engine can keep generating milestones and royalties that support future revenue and earnings.
See why 29 investors see Schrödinger as 5% undervalued.
Result: Fair Value of $31.14 (UNDERVALUED)
Still, compressed software margins and continuing net losses mean the Schrödinger story can change quickly if hosted adoption or partnered economics disappoint.
Find out about the key risks to this Schrödinger narrative.
Another View On Schrödinger’s Valuation
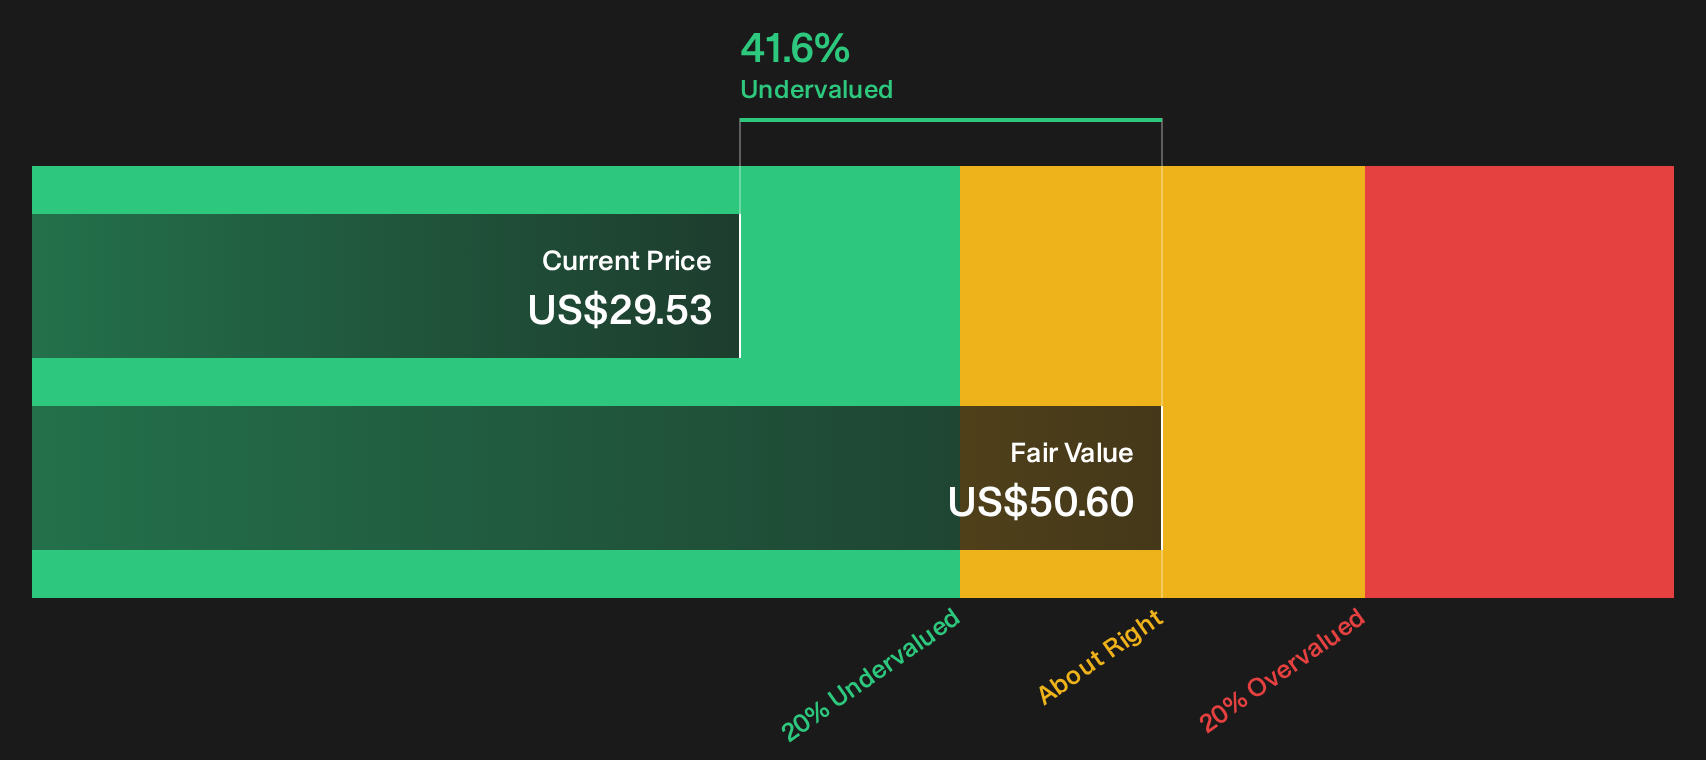
That 5% gap to the fair value from the analyst narrative is only one lens. The SWS DCF model paints a very different picture, with Schrödinger at $29.53 compared with an estimated future cash flow value of $50.60, which screens as materially undervalued. Which signal do you trust more when the earnings profile is still loss making?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on Schrödinger’s value story so far? Use that tension as a prompt to move quickly. Review the data for yourself and weigh both the potential upside and the open questions highlighted in the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Schrödinger?
Do not stop with Schrödinger. Use this as a starting point, then cast a wider net with focused stock ideas built from the Simply Wall St screener tools.
- Target potential value opportunities by scanning a curated 32 high quality undervalued stocks that combine quality fundamentals with attractive pricing signals.
- Strengthen portfolio resilience by reviewing a list of solid balance sheet and fundamentals (24 results) that can help you prioritise financial sturdiness when conditions get tougher.
- Get ahead of the crowd by checking a 20 high quality undiscovered gems that highlight lesser known companies with strong underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com