
Does Offshore Wind Progress Change The Bull Case For SSE Shares (LSE:SSE)?
- SSE has recently highlighted progress on its offshore wind pipeline, including UK job creation linked to the Berwick Bank B project, alongside guidance for upcoming half year results supported by stronger renewable output.
- The company is also funding a £470,000 STEM programme in the Highlands, which links classroom learning to future roles in renewable energy and power networks.
- Attention now turns to how SSE's investment narrative could be shaped by offshore wind progress and the upcoming half year earnings update.
Scan how SSE fits into the broader transition by weighing it up against hand picked 44 power grid technology and infrastructure stocks shaping the future of electricity networks and grid resilience.
SSE Investment Narrative Recap
To own SSE, you need to believe its heavy investment in electricity networks and contracted renewables can translate into more predictable, index linked earnings over time, as outlined in the analyst consensus Narrative on Simply Wall St. The near term focus sits on the 18 November half year update, where delivery against the 64p to 68p adjusted EPS guidance and progress on spending in networks will be front of mind.
The biggest operational risk still lies in executing large projects without fresh delays or extra costs, while keeping a high debt load within the stated net debt to EBITDA ceiling. The recent news around renewables output and project execution looks directionally helpful for that short term catalyst, but does not fundamentally change the risk profile.
The Berwick Bank B announcement is the most relevant piece of news here. SSE has confirmed Siemens Energy as preferred supplier and linked more than 3,000 UK jobs to the project, including 130 new Scottish roles. For you, the key angle is not the job count; it is whether another large offshore project can move from plan to build while staying inside return hurdles.
This project sits within a roughly £33b investment plan running to 2030 that the analyst consensus Narrative on Simply Wall St frames as central to SSE’s long term earnings mix. Progress at Berwick Bank B can support the story that big offshore schemes, such as Dogger Bank and this one, are advancing, which matters for confidence around future contracted cash flows, especially given existing concerns about prior onshore wind impairments and project cost inflation.
SSE's narrative projects £12.7b revenue and £3.0b earnings by 2029. This assumes 7.8% yearly revenue growth and an earnings increase of about £1.8b from the current £1.2b level.
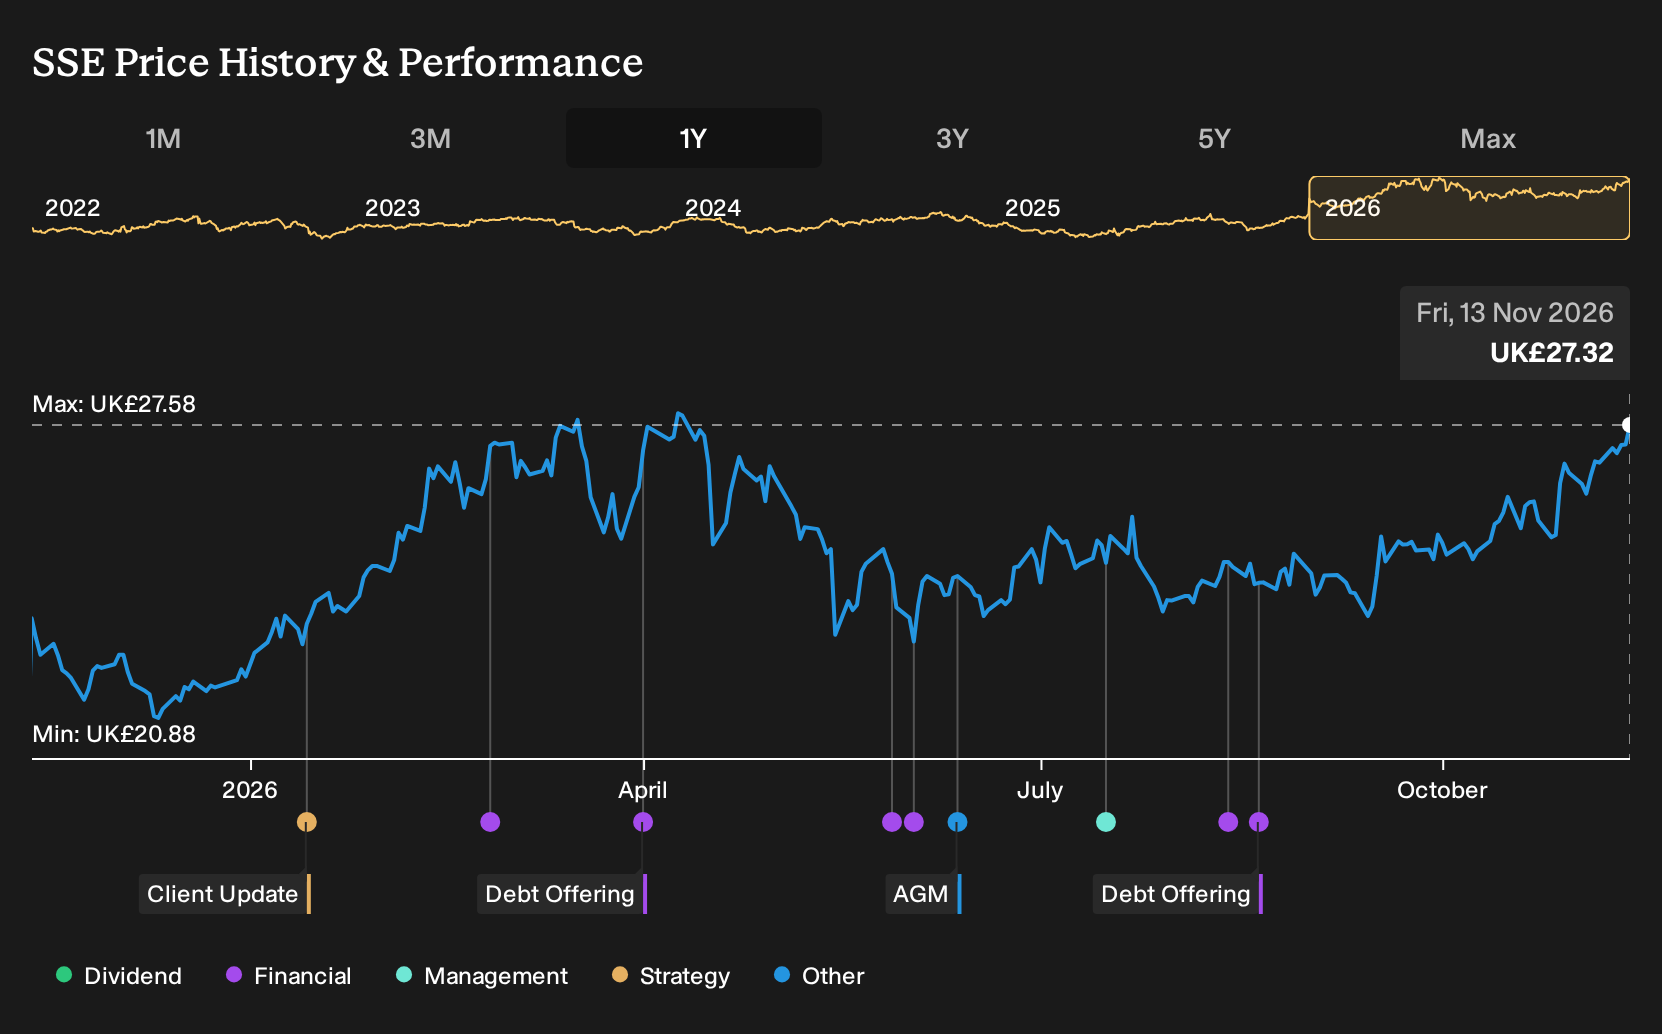
Uncover why SSE's fair value indicates SSE is roughly in line with its current price.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster between £20.24 and £31.76, which shows how far opinions on SSE can stretch. Some members see limited upside, others much more. When you layer in leadership change, big offshore projects and record capex, you get plenty of moving parts. Explore those competing views.
Explore 3 other SSE fair value estimates, including one that suggests up to 16% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your SSE research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for SSE. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SSE's overall financial health at a glance.
Looking for more investment ideas beyond SSE?
Once you have a view on SSE, it can help to compare it with other companies that share similar qualities or offer a very different risk profile. The Simply Wall St Screener is a quick way to build that wider watchlist without getting buried in noise.
- If you want potential mispricing with quality in mind, start by scanning a focused set of 15 high quality undervalued stocks that clear both cash flow and balance sheet checks.
- For steadier income and capital discipline, check out companies in the 4 dividend fortresses that meet a minimum 5% yield while still targeting durability of payouts.
- When capital preservation sits higher on your list than pure upside, filter for resilience through a 5 resilient stocks with low risk scores that screens for lower risk scores and stronger financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com