
Full Year Results Preview Altering The Investment Case For Imperial Brands Stock?
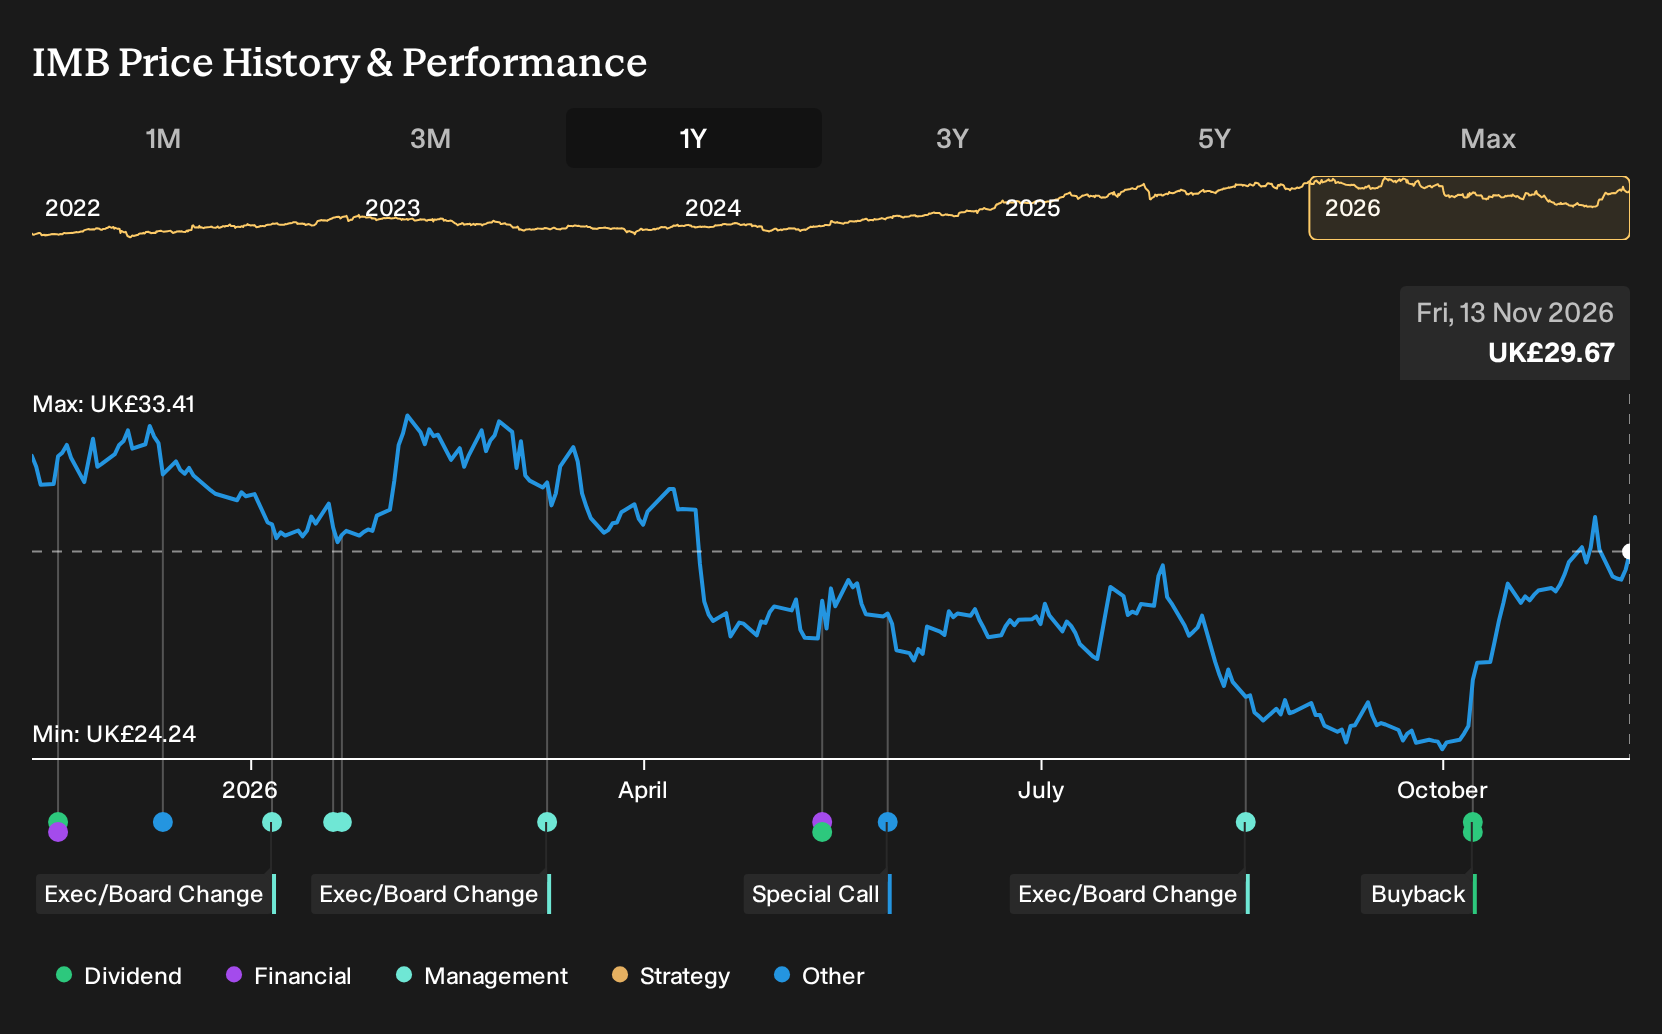
- Imperial Brands recently confirmed that full year results, released after 17 November 2026, are expected to show 3% to 5% adjusted operating profit growth, high single digit earnings per share growth, and outline a planned £1.5b share buyback for the coming year.
- The key question for Imperial Brands now is whether pricing power, market share in the US and Germany, and next generation products like heated tobacco and vapes can collectively counter falling cigarette volumes while still supporting cash returns.
- Next, the focus shifts to how Imperial Brands' investment narrative could be reshaped by profit expectations and the planned £1.5b buyback.
Compare Imperial Brands' setup to other tobacco and dividend-heavy plays by scanning our hand picked 4 dividend fortresses that may also be leaning on buybacks and resilient cash flows.
Imperial Brands Investment Narrative Recap
To own Imperial Brands, you need to be comfortable with a slow shrinking cigarette market and trust that price mix, market share in the US and Germany, and cost savings can keep earnings and cash flow resilient. The analyst consensus narrative on Simply Wall St leans on that mix of disciplined pricing and factory and digital efficiencies as the core of the thesis.
The upcoming full year numbers, with guided adjusted operating profit growth of 3% to 5%, look important mainly as a check that this engine is still running smoothly. The near term swing factor is whether pricing and mix can keep offsetting volume declines. The key operational risk is that next generation products stay loss making while promotions and regulation weigh on margins.
The planned £1.5b share buyback for the coming year is the headline announcement that ties closest to this update. It sits on top of an evergreen repurchase program that has already retired roughly 20% of the share count since 2021, and it keeps Imperial Brands tightly linked to a capital return story alongside its dividend profile.
For you as an investor, that buyback only really helps if the core business keeps throwing off strong free cash and the high level of debt remains manageable. Execution on the five year plan, progress on next generation product losses, and the impact of any fresh tax or regulatory moves will decide whether this new repurchase round ends up reinforcing the current investment narrative or highlighting its limits.
Imperial Brands' current analyst narrative points to revenues of £10.7b and earnings of £2.5b by 2029, built on an assumed 18.1% yearly revenue decline and an earnings increase of about £800m from earnings of £1.7b today.
Uncover why Imperial Brands' fair value indicates a 7% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on Imperial Brands leans heavily on regulatory risk. In that story, tougher rules and excise shifts could pressure the £10.8b revenue and £2.3b earnings that the most cautious analysts were pencilling in for 2029. Those estimates came before this latest update, so you should expect opinions to move and you should explore several angles yourself.
Explore 5 other Imperial Brands fair value estimates, including one that suggests as much as 9% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Imperial Brands research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Imperial Brands. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Imperial Brands' overall financial health at a glance.
Looking for more investment ideas beyond Imperial Brands?
Once you have a view on Imperial Brands, it can help to cross check that thesis against other companies with different risk and income profiles using the Simply Wall St Screener.
- If you want potential growth with a small starting size, scan 19 elite penny stocks with strong financials that already show stronger balance sheets and cash discipline than many peers.
- If value and quality matter most to you, filter for 15 high quality undervalued stocks that pair healthier cash flows with sturdier financial positions.
- If capital preservation is your priority, focus on 5 resilient stocks with low risk scores that Simply Wall St scores as more resilient on key risk factors.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com