
DraftKings (DKNG) Cuts EBITDA Outlook, Is The Stock Still Undervalued?
DraftKings (DKNG) is back in focus after management sharply increased planned spending on its Predictions business, which cut adjusted EBITDA guidance and contributed to softer expectations for 2026 and 2027.
Over the past year, momentum in DraftKings has faded, with the share price down 47.0% year to date and the 1 year total shareholder return declining 36.1%. Heavier Predictions spending, weaker 2026 and 2027 guidance, analyst downgrades and a paused buyback are reshaping how investors price both growth potential and risk.
Pace your exposure to gambling risk by scanning a curated set of operators and adjacent plays screened for 31 resilient stocks with low risk scores.Bulls see DraftKings buying future cash flow at a discount. Bears see a Predictions spending binge deepening losses. The valuation section tests which side current pricing respects more.
Most Popular Narrative: 9.9% Undervalued
DraftKings last closed at $18.89, while the most followed narrative on Simply Wall St pegs fair value at $20.97, which points to a modest discount that still assumes the business can turn scale into durable profitability. According to CentryResearch, an investor in the Simply Wall St Community who wrote the narrative, the key question is whether DraftKings can earn through heavier taxes, regulation, and new forms of betting.
As legalization slows, competition intensifies, state tax rates rise, and new prediction market platforms such as Kalshi and Polymarket begin competing for users, DraftKings may find sustaining its growth increasingly difficult. We believe the market may be underestimating the structural headwinds that could emerge over the coming years.
See why 8 investors see DraftKings as 10% undervalued.
The fair value estimate in that narrative is built using a discount rate of 8.63% and assumes DraftKings can eventually support a 9% profit margin on revenue that grows 9% per year. Those inputs leave room for execution, but they also bake in the idea that the current loss making profile and tax pressure do not permanently cap returns on capital.
For readers weighing Bulls versus Bears on the Predictions spend, the valuation signal here is clear. The narrative still treats today’s price as implying weaker cash generation than the discounted cash flow model behind that $20.97 fair value suggests, even after a 47.0% share price decline year to date and a 36.1% fall in total return over one year.
Result: Fair Value of $20.97 (UNDERVALUED)
Still, the narrative can unravel quickly if state tax hikes bite harder than expected or if prediction markets drain higher-value bettors away from DraftKings.
Find out about the key risks to this DraftKings narrative.
Another View: DraftKings on Sales-Based Valuation
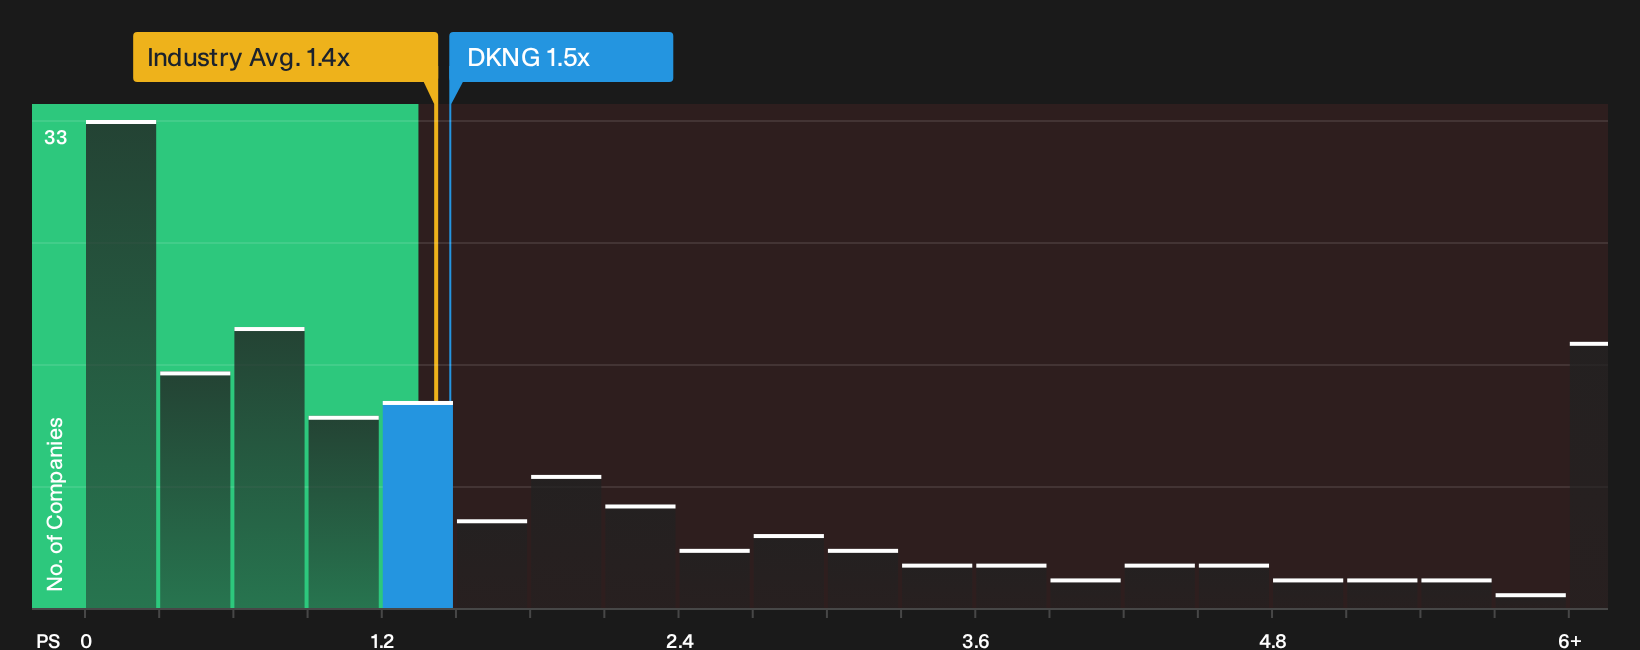
The DCF narrative presents DraftKings as modestly undervalued, while the current P/S ratio of 1.5x suggests a more cautious perspective. The stock trades at a higher multiple than the US Hospitality industry at 1.4x and above the peer average of 1.2x, even though the fair ratio implied by Simply Wall St data is 2.9x. Is that a margin of safety, or an indication that the market is still pricing in more execution risk than the DCF implies?
See what the numbers indicate about this price in the fuller valuation breakdown, starting with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With sentiment this mixed around DraftKings, the fastest way to cut through the noise is to check the underlying evidence yourself and move quickly while others hesitate. To see what the market is optimistic about right now, start with 2 key rewards.
Looking for more investment ideas beyond DraftKings?
If DraftKings has sharpened your focus on risk and reward, you can use that momentum to widen your opportunity set with a few targeted screens built for thoughtful investors.
- Spot potential mispricings early by scanning a curated pool of under-the-radar opportunities using 20 high quality undiscovered gems.
- Strengthen your core holdings by focusing on resilient businesses with conservative finances through the list of solid balance sheet and fundamentals (24 results).
- Explore market pessimism as a potential source of ideas by examining quality companies trading at attractive valuations via the 32 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com