
OptimizeRx Fell 52%, But The Story Isn't Over
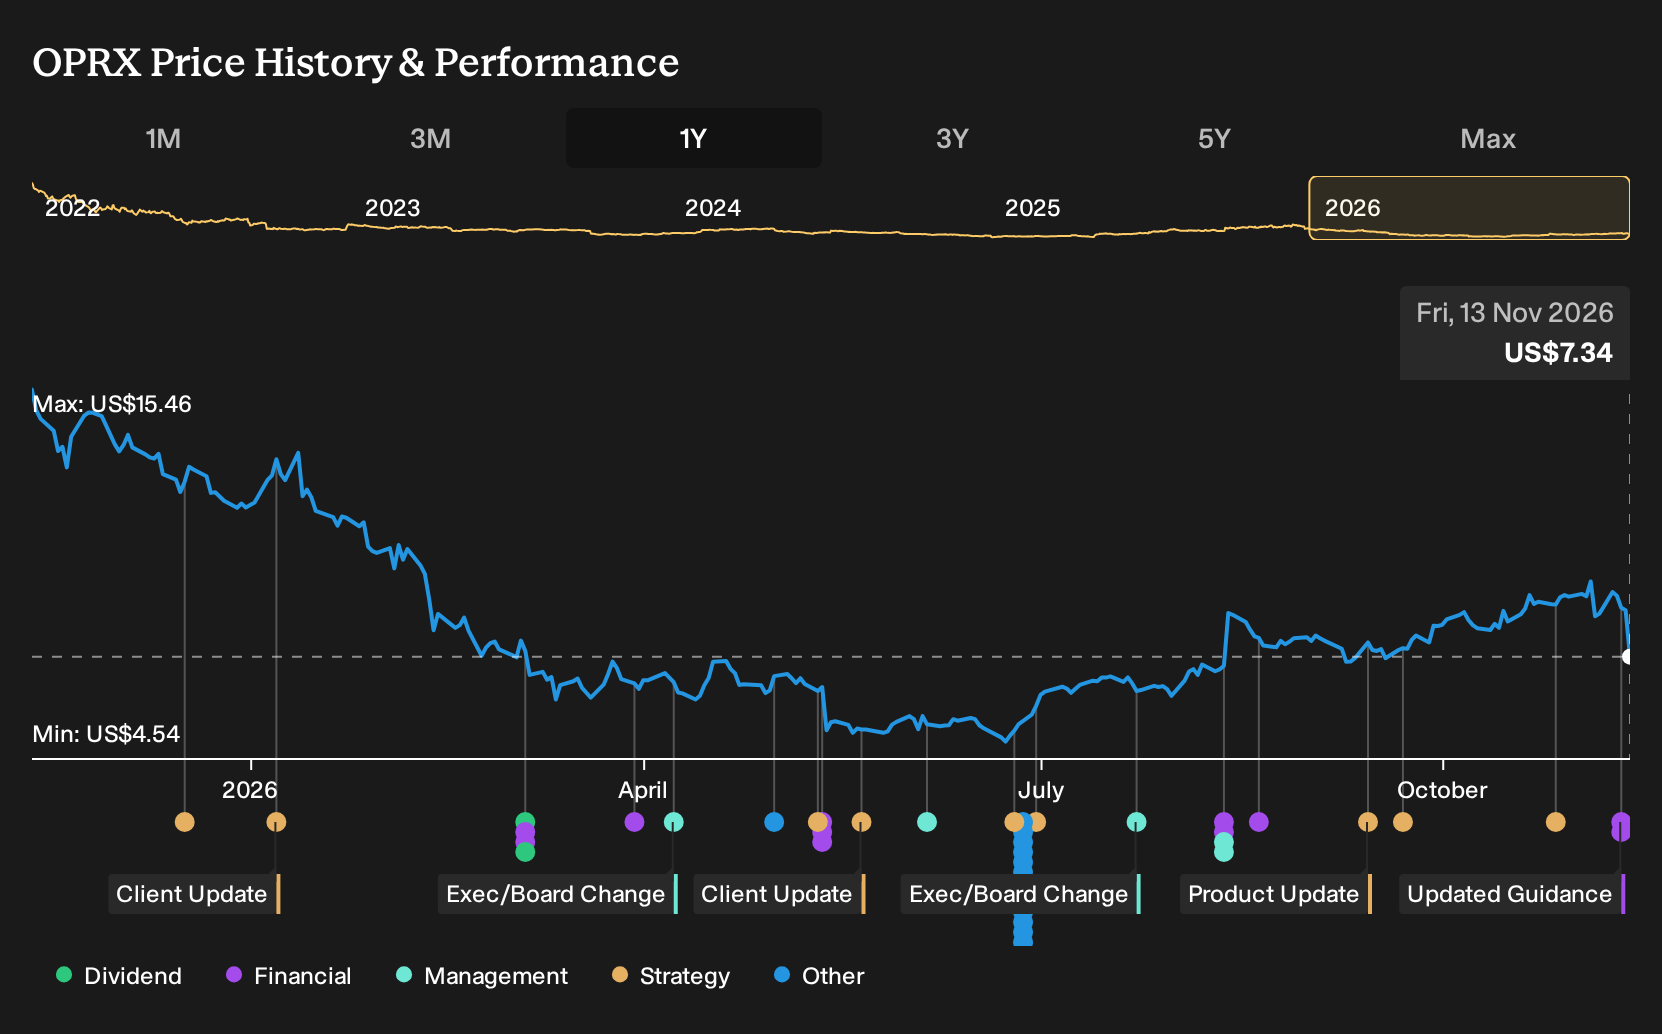
OptimizeRx has informed the market that its authenticated EHR and e-prescribing inventory will plug directly into PulsePoint, in a move aimed at tightening the link between digital media and the moment a clinician writes a script. Holding OptimizeRx over the past year would have meant a 51.6% loss, including dividends. If that decision sat in your portfolio, the key question now is whether this kind of deeper workflow integration can genuinely reset the business story from here.
OptimizeRx has already moved. Pinpoint other ways to investigate the theme among 36 healthcare AI stocks.
The Two OptimizeRx Stories Investors Had To Weigh
The shares cost US$15.46 at the start of the period, and anyone looking at OptimizeRx then had to choose between two very different stories about what that price meant.
On the optimistic side, one narrative pointed to pharmaceutical digital engagement as a long runway and argued for a Fair Value of US$19, a price that reflected assumptions like 8.0% annual revenue growth and profit margins rising toward 4.2% over roughly three years.
The more cautious view focused on data privacy pressure and provider fatigue, and suggested a Fair Value of US$11 based on beliefs such as 7.2% yearly revenue growth but a future P/E nearer 23.3x if margins eventually reached 8.8%.
What The Results Changed For The OptimizeRx Debate
The PulsePoint integration and CopayCue launch pushed OptimizeRx further into point of care engagement, which supported the optimistic story about deeper workflow access and pharmaceutical demand. The latest figures pulled in the other direction. Revenue moved from US$26.067m in Q3 2025 to US$21.615m in Q3 2026, while net income and net margin both improved. Overall, the evidence cut both ways.
The key assumption under review was that tighter EHR integration would pair with steady top line expansion. When you assess another healthcare tech stock pitching similar workflow access, track whether new product launches coincide with both rising revenue and a sustained net margin, rather than only one of those lines improving.
What The Fall In OptimizeRx Now Asks You To Believe
OptimizeRx trades at US$7.34 today, well below where it started over the past year, and the analyst consensus Narrative on Simply Wall St sees its Fair Value above that level based on how AI tools, authenticated EHR inventory and DSP links might reshape the revenue mix.
The fall only looks like a potential opening if you think OptimizeRx can turn DSP integrations, AI DAAP usage and a broader client base into steadier, higher margin software and subscription income that offsets recent revenue pressure. That is the core bet a buyer at today’s price would be testing.
"The main factor that has to go right is the company successfully converting DSP integrations, AI-enabled DAAP growth, and expanding mid-tier and medtech relationships into durable, higher-margin software and subscription revenue, while managing customer concentration risks."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Which Company Could Surprise You Next?
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 44% below our estimate - sells large LED display systems as advertisers and transport projects upgrade signage.
- Company 2 - 47% below our estimate - expands an asset-light hotel network while adding a complementary branded retail footprint.
- Company 3 - 33% below our estimate - grows coconut-based beverage volumes through branded lines and retailer private-label partnerships.
Those are three of them. See every one of the 32 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com