
How Investors May Respond To Friedrich Vorwerk Group (XTRA:VH2) Strong Quarterly Earnings
- Friedrich Vorwerk Group SE reported third quarter 2026 revenue of €247 million, net income of €47.94 million and basic EPS from continuing operations of €2.40, alongside nine month revenue of €606.81 million and net income of €97.89 million.
- The earnings release points to higher profitability per share over both the quarter and the first nine months, which gives investors more concrete data on how Friedrich Vorwerk Group is converting its project pipeline into bottom line results.
- We will now look at how Friedrich Vorwerk Group's investment narrative is affected by this increase in net income.
Scan Friedrich Vorwerk Group's latest results against hand-picked peers by jumping into the 199 high quality undervalued stocks that combine robust cash flows with balance sheet strength.
Friedrich Vorwerk Group Investment Narrative Recap
To own Friedrich Vorwerk Group, you need to believe that the energy transition in Germany and Europe keeps translating into complex grid, gas and hydrogen projects that suit its capabilities. The latest quarterly figures, with €247 million in revenue and €47.94 million in net income, point to strong project execution and a healthy conversion of the backlog into earnings.
The near term swing factor is whether this profitability level holds as large projects roll through and the mix shifts away from legacy electricity contracts like A Nord over time. The main risk flagged in the analyst consensus Narrative on Simply Wall St remains margin compression if pricing tightens or profitability drifts more quickly toward management’s 20% to 22% long term EBITDA range.
The key announcement tied to this catalyst is the reported JV inclusive backlog of €1.4b that the analyst consensus Narrative on Simply Wall St highlights as central to revenue visibility. With nine month revenue of €606.81 million and net income of €97.89 million, that pipeline gives you concrete context for how much work is already on the books relative to current output.
Hydrogen contracts such as H2CoastLink 1 and hydrogen ready metering at meterQ are another operational lever because they link Friedrich Vorwerk Group directly to future energy infrastructure spending rather than only today’s gas and power projects. The recent earnings strength makes it easier to track whether these hydrogen activities start to show up more visibly in reported revenue and earnings over the next few reporting periods.
Friedrich Vorwerk Group's current analyst narrative points to revenue of €998.7 million and earnings of €116.7 million by 2029, based on expected yearly top line growth of 10.5%. That profile assumes earnings today of €108.2 million and an earnings increase of about €8.5 million by the 2029 forecast year.
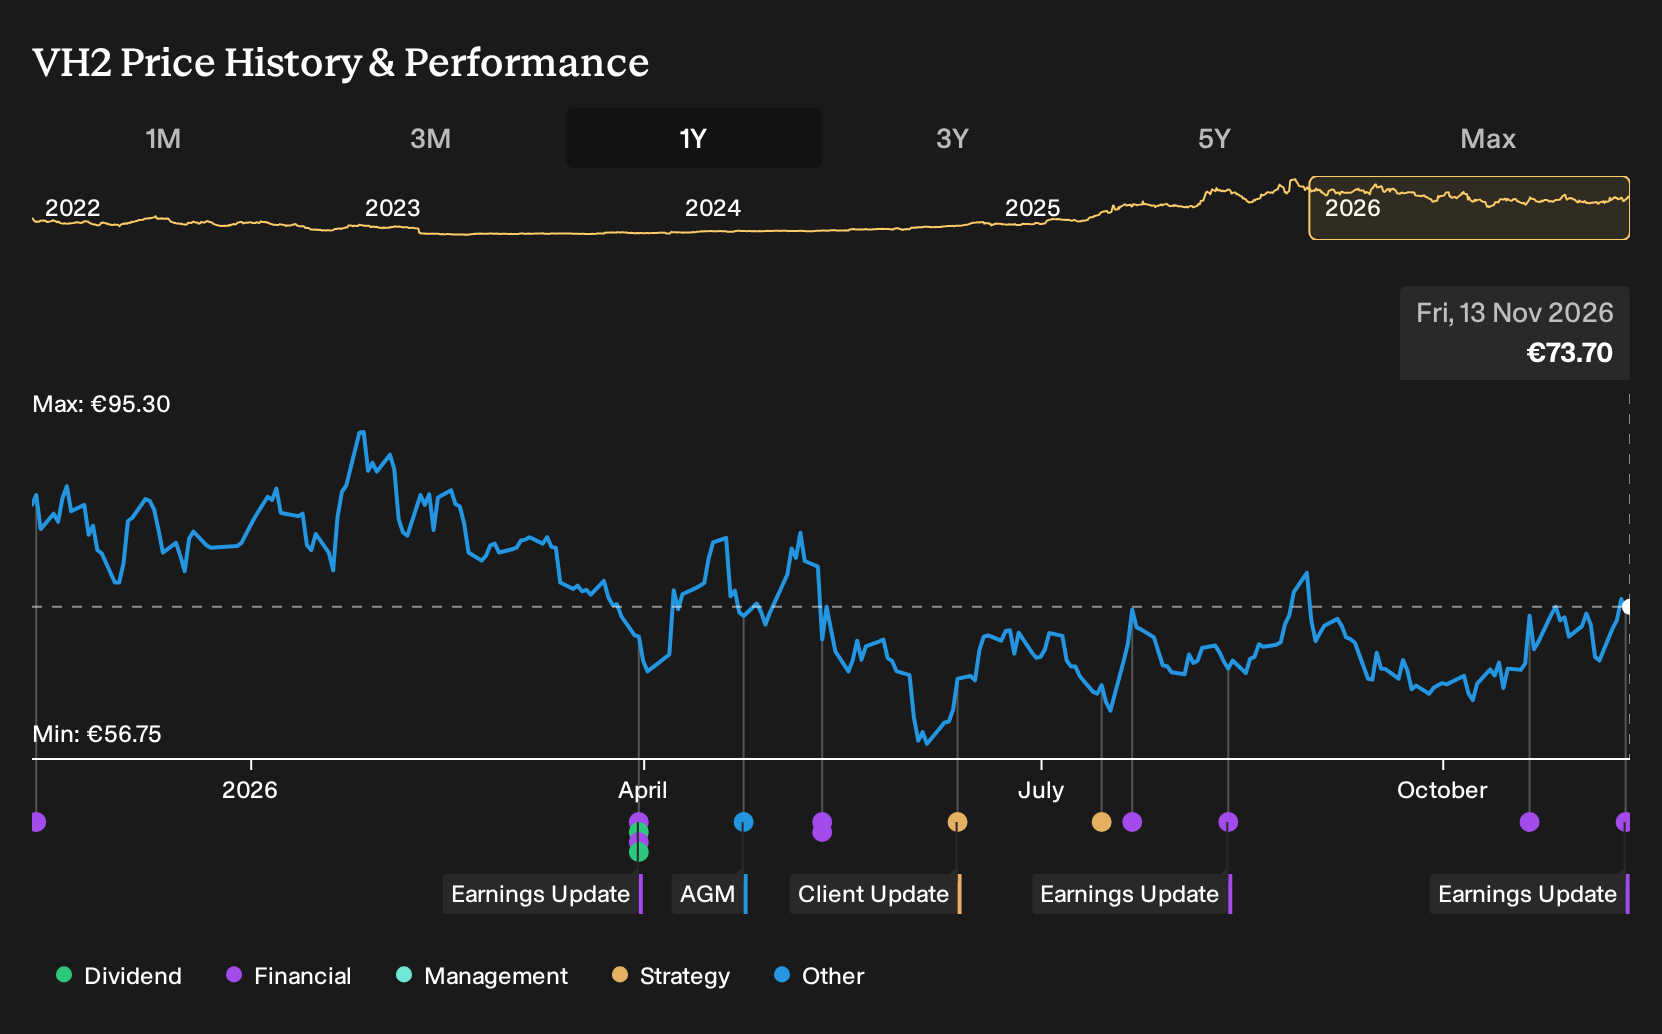
Uncover why Friedrich Vorwerk Group's fair value indicates a 24% potential upside to its current price. This reflects a valuation gap that could close faster than many expect.
Exploring Other Perspectives
One optimistic angle around Friedrich Vorwerk Group focuses on the potential of 5C Tech welding robots and meterQ to lift earnings beyond consensus. Before this earnings release, the most bullish analysts were pencilling in roughly €1.0b revenue and €117.1 million profit by 2029. You now have fresh results those forecasts did not yet reflect, so it makes sense to compare several viewpoints rather than rely on a single narrative.
Explore 3 other Friedrich Vorwerk Group fair value estimates, including one that suggests as much as 60,536,905% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Trust your own research and judgment.
- A great starting point for your Friedrich Vorwerk Group research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Friedrich Vorwerk Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Friedrich Vorwerk Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Friedrich Vorwerk Group?
If the Friedrich Vorwerk Group story has sharpened your thinking, use that momentum to scan a wider set of businesses that match the risk and return profile you prefer. The Simply Wall St Screener lets you filter by balance sheet strength, income potential or mispriced quality so you can build a watchlist that actually reflects your own criteria.
- For investors who want stability first, start with companies that prioritise resilience and capital protection through the 211 resilient stocks with low risk scores.
- If dependable income is your priority, check out higher yielding businesses with robust payout profiles through the 219 dividend fortresses.
- When you want something off the beaten path, focus on under-followed quality by running the 566 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com