
Alector Holders Are Up 105% And Here Is What They Saw
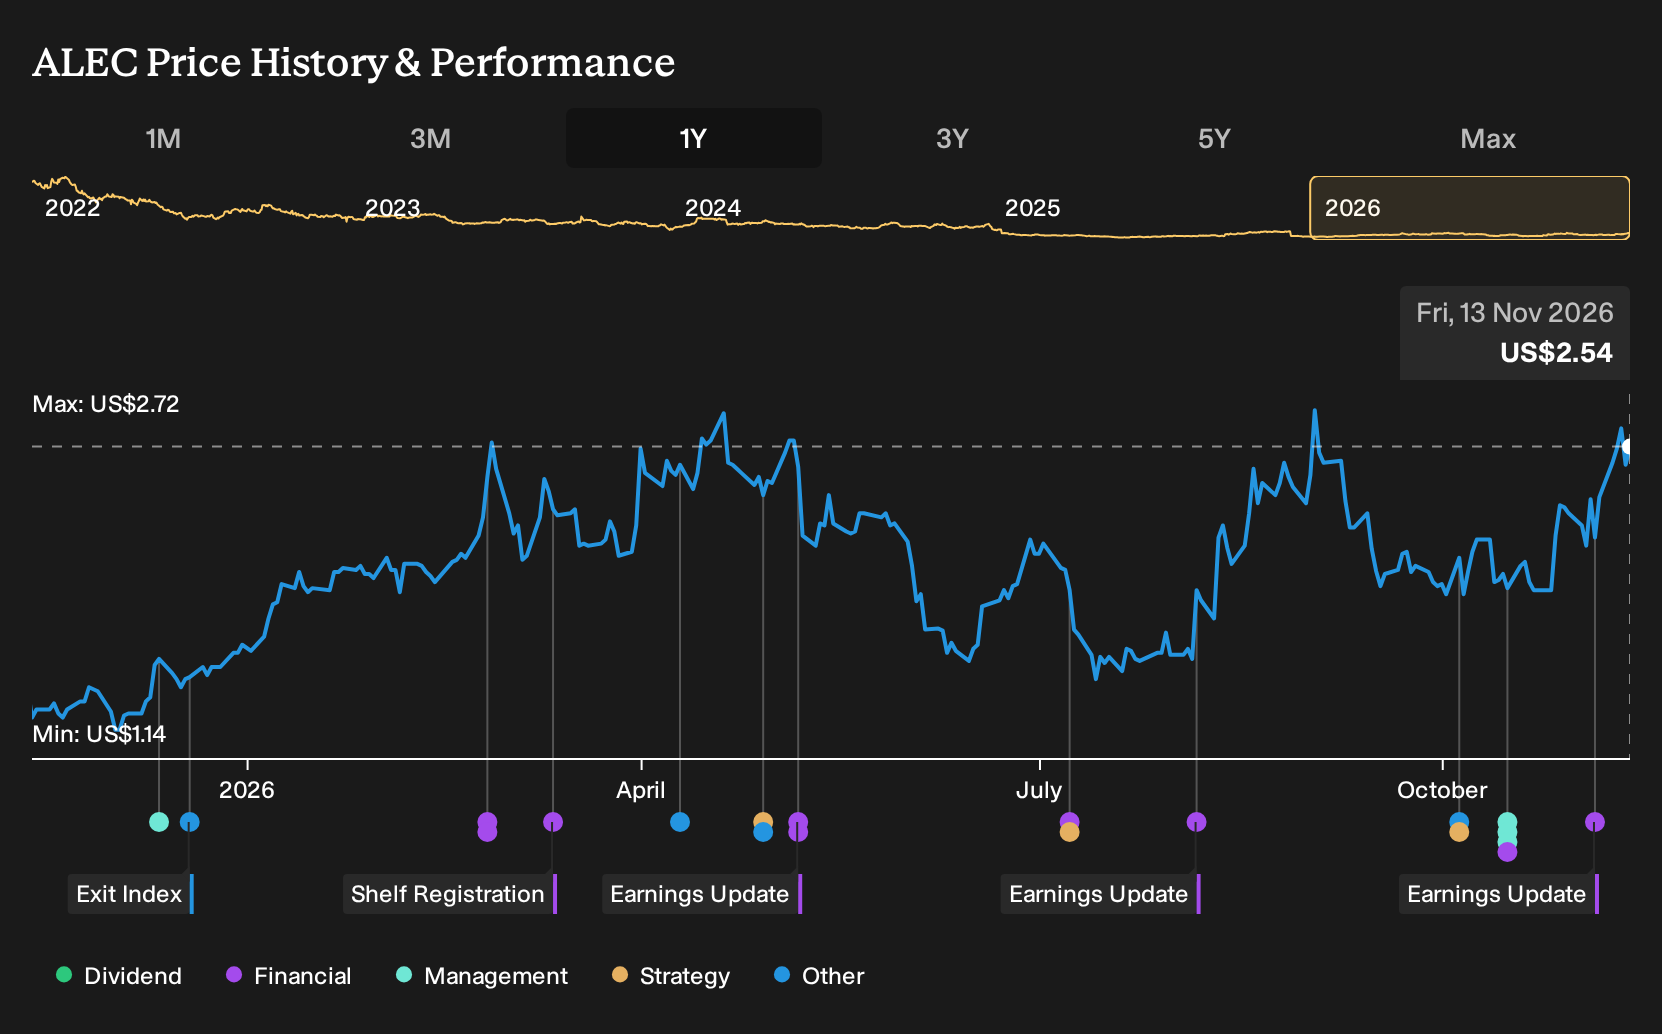
Alector looked risky on paper when analysts were arguing over whether its shares were worth closer to US$1 or nearer US$10. For Alector shareholders, the return over the past year was 104.8%, including dividends. If you had bought at the 2025 decision point, you would now be looking at a very different portfolio line. With results now on record, what did the early data really signal about this business?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind Alector. Zero in on 32 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing Up On Alector
The shares cost US$1.2 at the start of the period, and Alector sat between two very different stories about what might come next.
In the bullish narrative, the Fair Value was set at US$3.83, based on the assumption that revenue could climb 64.8% a year and profit margins could rise to 18.8% within three years.
The bearish case pointed to a Fair Value of US$1, assuming revenue would decline 43.3% a year and that Alector would still not be profitable over the same horizon.
What The Results Changed For Alector
The clearest new fact was the swing in Alector’s reported net income, from a loss of US$34.667 million in Q3 2025 to a profit of US$124.6 million in Q3 2026. Revenue for the same quarter moved from US$3.26 million to US$162.866 million. That shift gave more support to the optimistic case, although the short three year profitability target still remains unproven.
The key assumption here was not just growth, but the path to positive earnings. For any similar biotech, you would want to track the move from losses to recurring profit and compare that against the margin and P/E expectations used in your own fair value range.
What Alector’s Recent Run Now Prices In
Alector now trades at US$2.54, after a 104.8% gain over the past year. The analyst consensus Narrative on Simply Wall St places its Fair Value above that level, based on a thesis that leans more on the ABC platform than on any single drug.
That Narrative’s view hinges on Alector using the Brain Carrier technology and partnerships to turn today’s pipeline into future licensing and milestone income. The key question for anyone paying today’s price is whether ABC enabled programs like AL137 can keep showing the kind of biomarker data that sustains that belief.
"The current valuation suggests the market is pricing Alector cautiously despite the Genentech/Roche AL050 deal, the extended cash runway to around 2029, and research firms highlighting the company as a platform story rather than a single asset stock."
The price and this Narrative do not agree. → Uncover what this Narrative says Alector is actually worth
Looking One Step Beyond Alector
Alector is one way to approach new neuroscience drugs. You could instead step back and consider a broader healthcare engine.
Large pharma groups are working to refresh aging product portfolios. Rather than depending on a single blockbuster, they are spreading bets across oncology, vaccines and cardiometabolic treatments.
One of those giants focuses on a deep late stage pipeline. It is advancing next generation cancer drugs, oral cholesterol treatments and longer acting infectious disease regimens.
The goal is clear. Replace expiring products with a wider mix of therapies and longer treatment durations.
Investors are left watching whether that shift truly holds up in practice.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 26% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com